How to Actually Pull a Rental History Report
You want to find out rental history on a tenant, co-tenant, or prospective roommate. The standard approach is running a credit report through a residential tenant screening service. Equifax, TransUnion, and Experian all offer rental payment data now, but that alone won't give you a full picture. You need evictions, landlord references, and sometimes prior address verification. Most people skip steps here and end up with incomplete information. Start with a dedicated tenant screening platform. My go-to has been Checkr, RentPrep, and MyRental over the years. They aggregate data from county court records, credit bureaus, and specialty databases like CoreLogic and LexisNexis. The key is understanding what each source actually covers. County eviction records are public but inconsistently reported. Some jurisdictions purge records after seven years. Others never delete them. A screening company might show an eviction from 2014 that technically expired locally but still shows up in aggregators because they pull nationally. Here is the part nobody tells you: credit report rental data is usually just payment history. It tells you whether rent was paid on time. It does not tell you if the tenant destroyed the unit, didn't give proper notice, or had a dispute with the landlord. For that, you need actual eviction court records and landlord references. I learned this the hard way about three years ago when a screening report came back clean on a property I was evaluating. Six months later, the tenant was three months behind on rent and had no forward address. I dug into the county records myself and found a prior eviction in another county that the screening service had missed because the records were filed under a slightly different name variation. The workaround was pulling the tenant's SSN authorization and running a manual search across the three nearest counties where they could have lived, not just the one they currently listed.
If you are doing this on a tight budget, you can go direct to the credit bureaus. TransUnion's Rental Insight program is the most useful of the three. It pulls payment data from about 10,000 property management companies directly. Equifax has something similar but covers fewer landlords. Experian RentBureau is decent but has less coverage. None of these give you eviction records on their own. You would still need a separate service for that, which kind of defeats the cost savings. County clerk searches are another route. Go to the civil division of the courthouse in any county where the person has lived. Most courts now have online search portals. You search by name and sometimes by SSN or date of birth. This is slower but more complete than what any commercial aggregator will show you. The problem is that it takes hours if the person has lived in multiple counties. I usually limit this to cases where a screening report looks suspiciously clean for someone with a long rental career. One thing that catches people off guard: many screening reports only show the most recent two to three addresses. If the tenant has been moving around every year, you are getting an incomplete story. Request a full address history. Some services charge extra for this. It is worth it. A tenant who lists only their current address and nothing else is either new to renting or hiding something. Both scenarios warrant a deeper look.
Here is another nuance. Eviction judgments and eviction filings are different things. A filing means someone started the process. A judgment means the court ruled. Some landlords settle before judgment or the tenant pays in full during the process. These dismissed or settled cases often still appear on reports. Don't treat every eviction entry as a red flag without checking the disposition. I once passed on a tenant who had an eviction filing from six years ago. When I pulled the court document myself, it turned out the landlord never actually served proper notice and the case was thrown out. The screening report listed it as an active eviction. The difference mattered. If you are a landlord managing a small portfolio, just subscribe to a screening service. Pay the per-report fee. It saves you from piecing together data from three different sources. If you are a property management company running dozens of applications, negotiate a volume discount. The per-check price drops significantly once you are above fifty reports a month. I was paying about $40 per screen until I pushed for a bulk rate and got it down to $22. The biggest mistake I see is relying solely on a credit score to predict rental behavior. A 720 credit score means nothing if the person has no rental history. Conversely, a 640 score with three years of on-time rent payments on a credit report is often a better signal than a higher score with only credit card debt. Payment history matters more than total debt when it comes to predicting whether someone will pay rent.
Get the Full Details
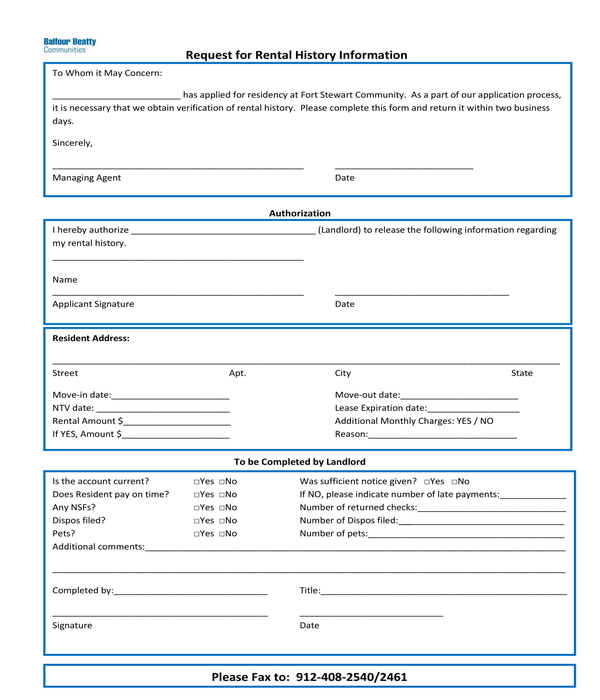
If you need something free, the National Multi Housing Council has an eviction registry, but it is incomplete and mostly contains cases where judgment was already entered. It is better than nothing for a quick check, but it will miss a lot. Don't use it as your only source. For landlords in states like California or New York, there are additional legal requirements around what you can and cannot ask for. The FCRA governs adverse action notices if you deny based on a screening report. You have to provide the screening company's contact information and tell the applicant they have the right to request a free copy of their report within sixty days. This is not optional. Skipping it opens you to liability regardless of whether the tenant actually has a legitimate complaint. What about personal references from previous landlords? They are useful but unreliable on their own. Landlords often refuse to give detailed feedback because of liability concerns. Many will just confirm dates of tenancy and rent amount. I recommend asking specific questions if you do get a reference. Was the unit left in acceptable condition? Did they provide proper notice? Were there any disputes? Vague answers like "they were fine" usually mean something was wrong but the landlord didn't want the hassle of explaining it.
One final thing. Background screening services vary in how often they update their data. Some pull fresh county records on every request. Others rely on cached data that might be months old. Check what the service actually does before you pay for it. I switched providers once because I noticed their eviction data was lagging by about eight months on average. That delay meant I was approving tenants with recent filings that hadn't shown up yet. That is a costly mistake to make twice.