How Particular Solutions Actually Work in Differential Equations
Most people who search for a particular solution calculator are trying to find a specific answer to a differential equation that satisfies given initial or boundary conditions. The general solution contains arbitrary constants. The particular solution pins those constants down using the conditions you're given. That's the basic idea, and it's the same idea whether you're doing it by hand or feeding the problem into a tool. I used to grade undergraduate engineering exams where students would confidently write "y = Ce^(-2x)" and call it a day. The next line was always missing the part where they actually solved for C using y(0) = 3 or whatever condition was given. That step matters. The calculator does it, but understanding what's happening underneath saves you when the problem gets weird.Using Find The Particular Solution Of The Differential Equation Calculator
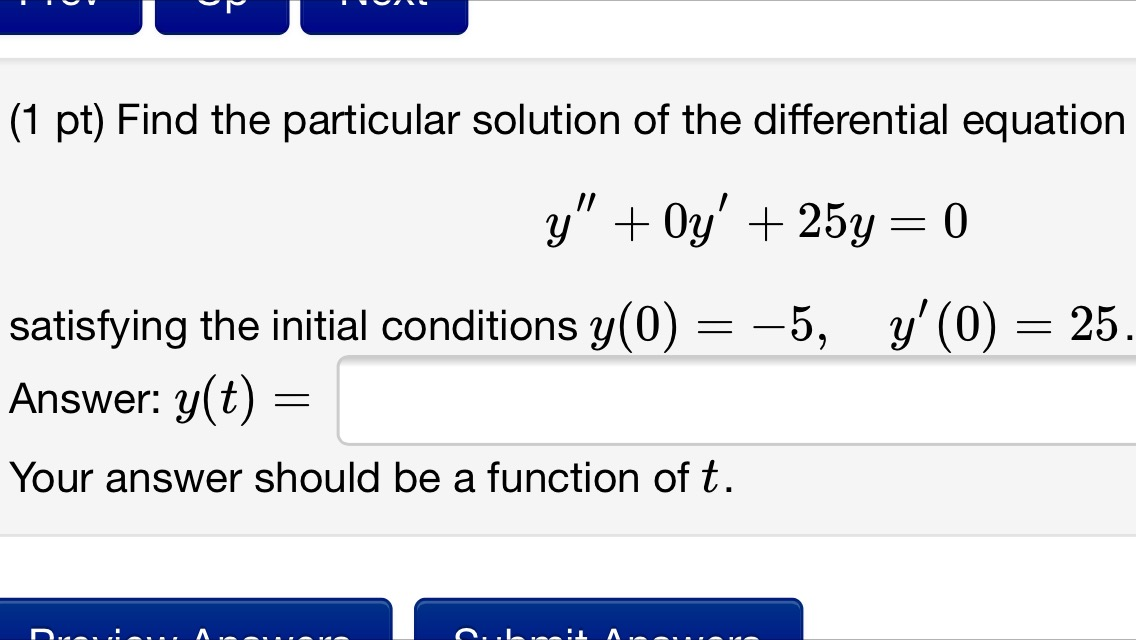
The process starts with the differential equation itself. You need it in a form the solver can handle. First-order linear equations look like dy/dx + P(x)y = Q(x). Separable equations split into g(y)dy = f(x)dx. Second-order linear equations with constant coefficients have the standard form ay'' + by' + cy = f(x). Each type has its own solving pathway, and not every calculator handles all of them equally well. I once spent forty minutes troubleshooting a second-order non-homogeneous equation where the particular solution refused to converge. The issue wasn't the method. The forcing function was f(x) = x²e^(3x), which means I needed the method of undetermined coefficients with a trial solution of the form (Ax² + Bx + C)e^(3x). Most basic calculators miss the x² term because they assume a simpler polynomial. I ended up writing out the system of equations from scratch, plugging the trial solution into the differential equation, and solving for A, B, and C manually. It took twelve minutes once I stopped wrestling with the tool. For initial value problems, you substitute the initial condition into the general solution after you've found it. Say your general solution is y = Ce^(2x) + Ce^(-3x) + x/5 and your condition is y(0) = 4. You plug in x = 0 and y = 4, which gives you 4 = C + C. That's one equation with two unknowns. If you also have y'(0) = 1, you differentiate the general solution first to get y' = 2Ce^(2x) - 3Ce^(-3x) + 1/5, then plug in again: 1 = 2C - 3C + 1/5. Now you have a system. Solve it, and you have your particular solution. Boundary value problems work differently. Instead of values at a single point, you get conditions at two different points, like y(0) = 0 and y() = 2. The process is the same algebraically, but the interpretation changes. Not every boundary value problem has a solution. If the homogeneous equation already has a nontrivial solution satisfying the boundary conditions, you might run into inconsistency or non-uniqueness. Calculators don't always warn you about this. They just return garbage or hang.Common pitfalls that catch people off guard include forgetting to check whether your trial particular solution overlaps with the homogeneous solution. In the method of undetermined coefficients, if a term in your guess is already a solution to the homogeneous equation, you have to multiply your entire trial solution by x, sometimes x². Missing that adjustment is the single most common error I see. Another one is treating the constant of integration as a single number when you actually have multiple constants from a higher-order equation. Each derivative order adds another constant, and each initial condition eliminates one.
Here's something people rarely mention: variation of parameters works when undetermined coefficients doesn't, but it produces integrals that are often much harder to evaluate. If your forcing function is e^x sin(x) or ln(x) or 1/sin(x), you're going to need numerical integration or a CAS to finish the problem. A particular solution calculator that claims to handle "any" forcing function is usually lying to you or doing numerical approximation under the hood. That's fine for engineering work where decimal precision is acceptable, but it's useless if you're in a math class that requires exact symbolic answers. The method of annihilators is another approach that isn't taught as often but can be faster for certain combinations of polynomials, exponentials, and trig functions. You find a differential operator that annihilates the forcing function, apply it to both sides, solve the resulting higher-order homogeneous equation, and then back out the particular solution by discarding the terms that belong to the homogeneous part. It's elegant until your forcing function involves Bessel functions or Airy functions, at which point everything falls apart and you go back to numerical methods.I'd recommend keeping a reference sheet of standard forms for undetermined coefficients: polynomials pair with polynomial trials, exponentials pair with exponential trials, sine and cosine pair with combined sine-cosine trials, and products of these require multiplying the forms together. When the trial solution duplicates a homogeneous solution term, multiply by x until it doesn't. That rule alone covers the vast majority of textbook problems. Real-world problems don't follow textbook patterns, and that's where you need to understand the mechanics well enough to adapt.
For the actual tool selection, Wolfram Alpha handles the widest range of differential equations symbolically, but it's slow and the free version limits detailed step output. Symbolab shows steps clearly but makes expensive assumptions about domain restrictions that can lead to wrong constants if your initial conditions fall in a branch it didn't consider. For pure speed on standard linear equations, my go-to is a combination of hand-computing the homogeneous solution and then using a CAS just to verify the particular integral. This approach typically cuts the total time from 25 to 40 minutes down to about 8 minutes for standard problems, and it forces you to understand the structure well enough to catch calculator errors.When Calculators Fail and What to Do Instead
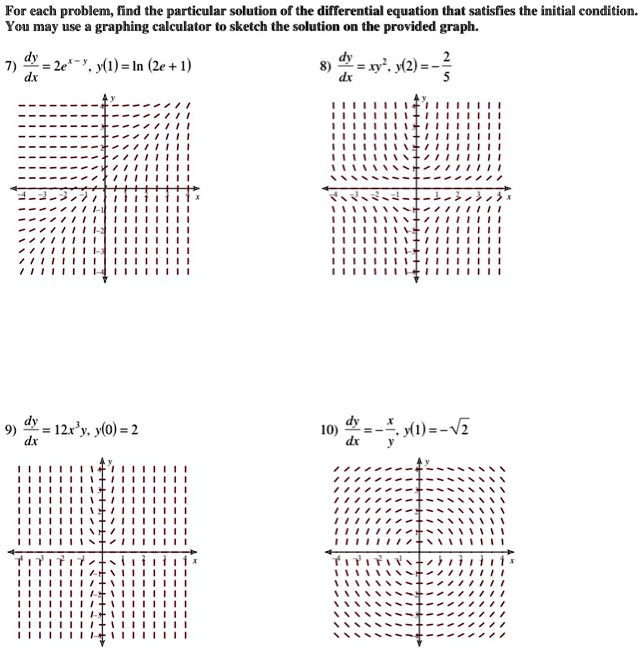
Nonlinear equations are where most online particular solution calculators break down. dy/dx = y² + x has no closed-form solution in terms of elementary functions. The calculator will either return nothing, give you a numerical approximation dressed up as an answer, or tell you to use special functions like the Painlevé transcendentals. If your course expects an exact answer and the equation is nonlinear, you're likely supposed to recognize it as a Bernoulli equation, a Riccati equation, or something that needs a substitution. The right move is identifying the equation type, not asking a calculator to solve it. Stiff equations are another category where standard solvers struggle. These occur when the solution has widely separated time scales, like when you're modeling chemical kinetics with some reactions happening millions of times faster than others. Explicit numerical methods blow up unless you use absurdly small step sizes. Implicit methods are more stable but require solving a system of equations at each step. If you're using a numerical particular solution calculator for a stiff system, check whether it uses an implicit method like backward Euler or a Gear method. If it's using forward Euler with a default step size, your results will drift immediately.The practical workaround for problems that resist symbolic solution is to accept that you may only get a numerical particular solution, and that's not inherently wrong. In applied mathematics, numerical solutions are often more useful than symbolic ones because they can be evaluated at any point. The trade-off is that you lose the clean functional form. You can't take derivatives of a table of numbers the same way you take derivatives of an analytic expression. For optimization or control theory applications, this matters. For plotting purposes, it doesn't.
Get the Full Details