Using the Fine Print Checking Account Statement Answer Key
I spent years helping people navigate bank statements before I got tired of watching the same mistakes repeat. The Fine Print Checking Account Statement Answer Key is one of those resources that shows up everywhere in financial literacy courses, but most people treat it like a cheat sheet instead of a learning tool. It works fine if you actually read through it properly, though. The answer key covers topics like monthly fees, interest calculations, overdraft protections, and direct deposit verification. These are the things banks bury in the fine print and most customers never look at until they get hit with a $35 charge for something they didn't expect. I've seen people miss a fee structure for months because they never checked their statements against the terms.
What the Fine Print Checking Account Statement Answer Key Actually Covers
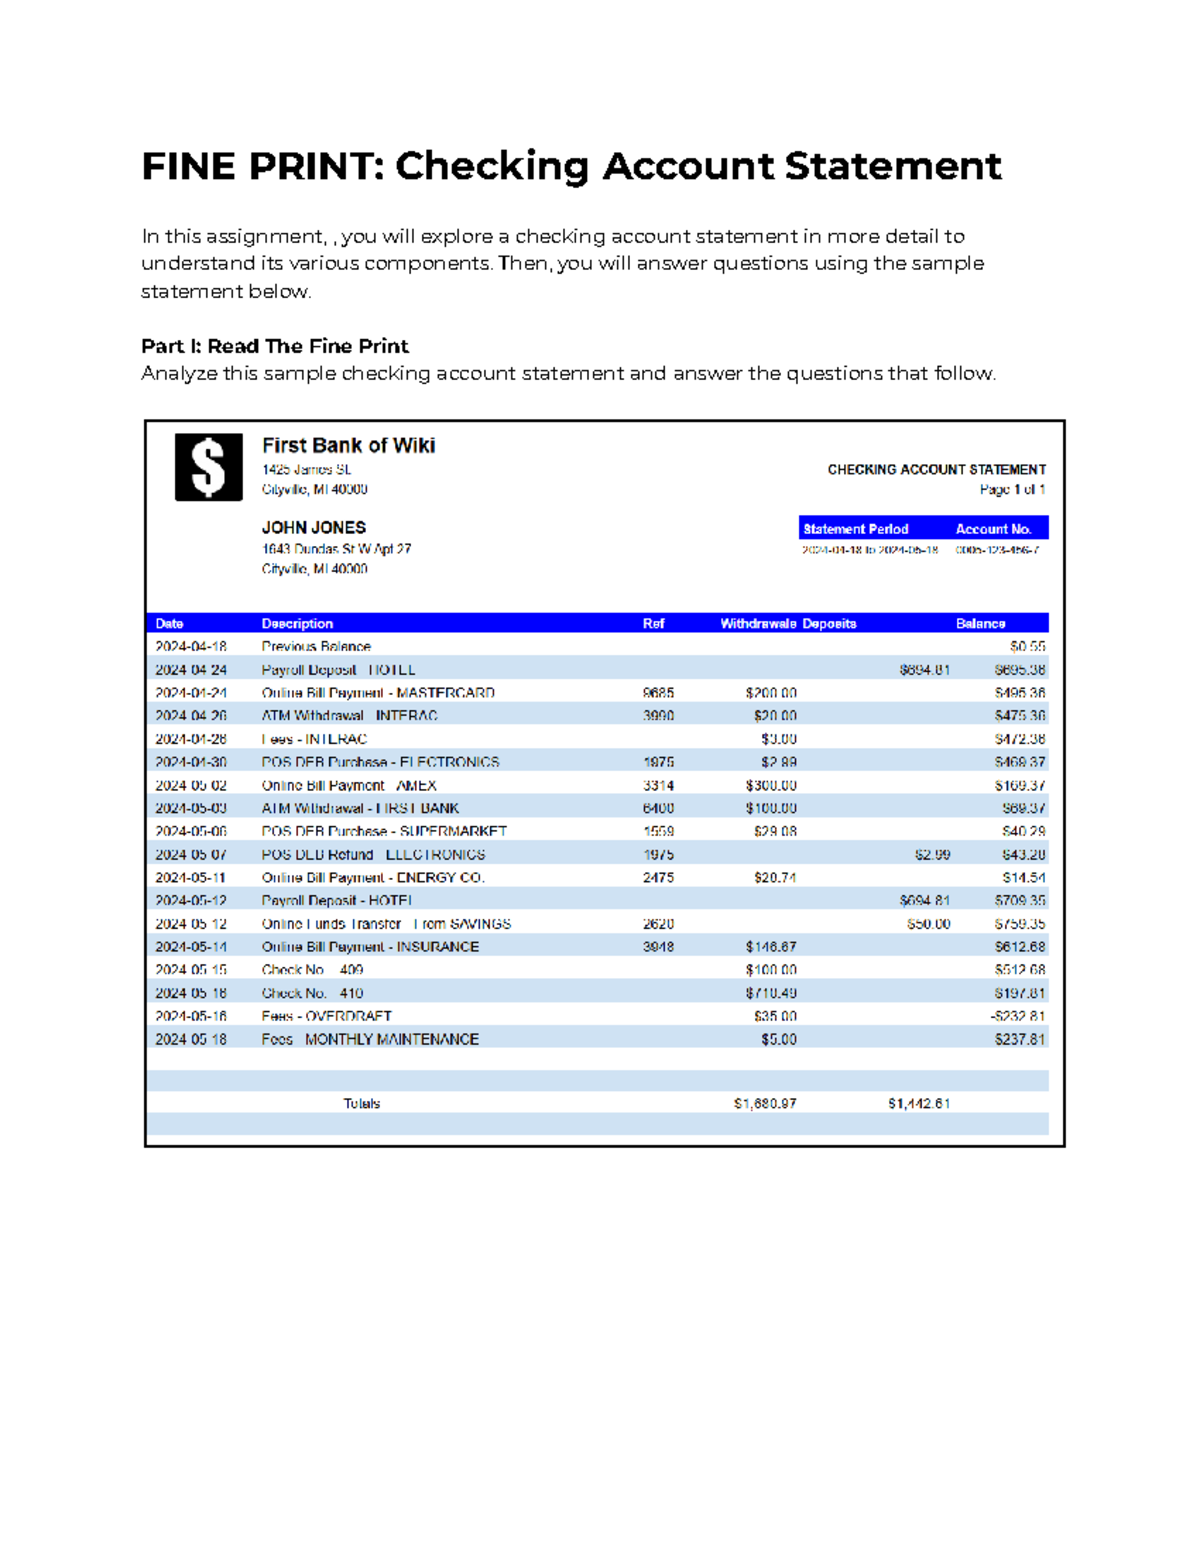
The document itself breaks down into sections: balance reconciliation, transaction verification, fee identification, and interest accrual. Each section has sample problems with step-by-step solutions. The format is straightforward — you get a hypothetical bank statement with several discrepancies built in, and the answer key walks you through finding them. Here's something most guides don't mention: the answer key assumes you already know basic arithmetic and can read a bank statement layout. If you don't know what a clearing number is or how ACH transfers appear on a statement, you'll get stuck at section one and move on frustrated. I've had students come to me with blank stares after working through the first few problems because they'd never actually looked at a real bank statement before. Buy yourself a printed statement from your own bank first — even an old one from six months ago — and go through it line by line before touching the answer key. That alone takes about twenty minutes and saves you from wasting the entire document. The fee identification section is where most people find real value. Banks charge for things they don't prominently advertise: maintenance fees that trigger if your balance drops below a threshold, out-of-network ATM fees, paper statement delivery charges, and overdraft protection transfer fees. The answer key walks you through calculating whether you actually owe a monthly service charge by comparing your average daily balance against your account terms. It's not complicated, but it requires patience.
How to Use It Properly
Don't just flip to the answers. Work through each problem on a blank piece of paper or in a spreadsheet. Write down your calculation, then check against the key. If you get the wrong answer, figure out where your logic diverged before looking at the solution. This habit alone will save you money because it trains you to look at your own statements critically rather than assuming everything is correct. I ran into a specific issue last year with a student who was using the answer key for a community college personal finance class. The problem set included a scenario with a variable daily interest rate that compounded monthly. The answer key showed the correct final balance, but when he plugged the numbers into a calculator, his result was off by about fourteen dollars. He came to me because he thought the answer key was wrong. It wasn't. The trick was that the bank statement he was working from listed transactions in chronological order, but the interest calculation required sorting them by date because there was a backdated correction entry — a NSF refund that posted three business days after the original transaction. Once we identified that entry and re-sorted the timeline, the numbers matched perfectly. The answer key never mentioned the sorting step because it assumed you'd catch it. That's the kind of thing you only learn through practice. Another thing worth knowing: the answer key's interest calculation examples use simple interest formulas for clarity, but most checking accounts that pay interest use daily compounding. If you want to apply these lessons to your actual account, you'll need to adjust the math. A quick formula is Balance × (Annual Rate ÷ 365) × Days in Period. It takes about thirty seconds per calculation and gives you a more accurate picture than what the simplified examples show.
Get the Full Details
Where This Resource Falls Short
The answer key is based on standard checking accounts from major banks. It doesn't cover credit union accounts, which often have different fee structures and rounding methods. It also doesn't address overdraft opt-in policies that changed after the 2010 regulation, so some of the older example scenarios might reference rules that no longer apply. If you're studying for a current certification exam, check the publication date on the material. Versions from before 2021 sometimes include outdated fee caps and disclosure requirements. For people who need to understand their own specific account terms, the answer key is a starting point, not a replacement for reading your actual account agreement. I always tell people to open their bank's terms of service document alongside the key. You'll spot discrepancies quickly, like a bank that charges a $12 monthly fee instead of the $8 shown in the examples. Those small differences matter when you're doing real budgeting. If you want something more current than the standard answer key, the FDIC's consumer guide to bank fees is free and updated regularly. It's less detailed on the math side but covers the regulatory landscape more accurately. Pairing both sources gives you roughly two hours of study time and leaves you better equipped to handle an actual bank statement than either resource alone.