Why Most People Fail the Series 65 on the First Try
The exam is 130 questions, two hours, and a 73% passing score. That last number is where people get confused. They think they need to get 95 questions right. You don't. You need 95. Coping mechanisms kick in during those two hours, and suddenly you are second-guessing easy questions because you are mentally exhausted. I learned this the hard way back in 2013 when I was helping a junior analyst prep for his licensing exam. It breaks down into five main content areas, and they are not weighted equally. Foundations of compensation and professional conduct is about ten percent. Client investment recommendations and financial advisory services is the biggest chunk at twenty-eight percent. Client obligations, rights, and fiduciary duties comes in at twenty percent. Economic forces and investment products and institutions is twenty percent, and the remaining twenty percent covers portfolio management strategies and techniques. The distribution is not random. Finra puts the most weight where real fiduciary disputes actually happen. Investment company products and employee investment trusts take up a noticeable portion of that second domain, which is where most people bleed points. Variable contracts, municipal fund securities, and retirement plan arrangements are not intuitive unless you have worked them. Textbooks describe them in sterile definitions. The exam tests whether you can spot when a variable annuity is being inappropriately compared to a money market fund inside a client presentation.
How to Structure Your Study Without Burning Out
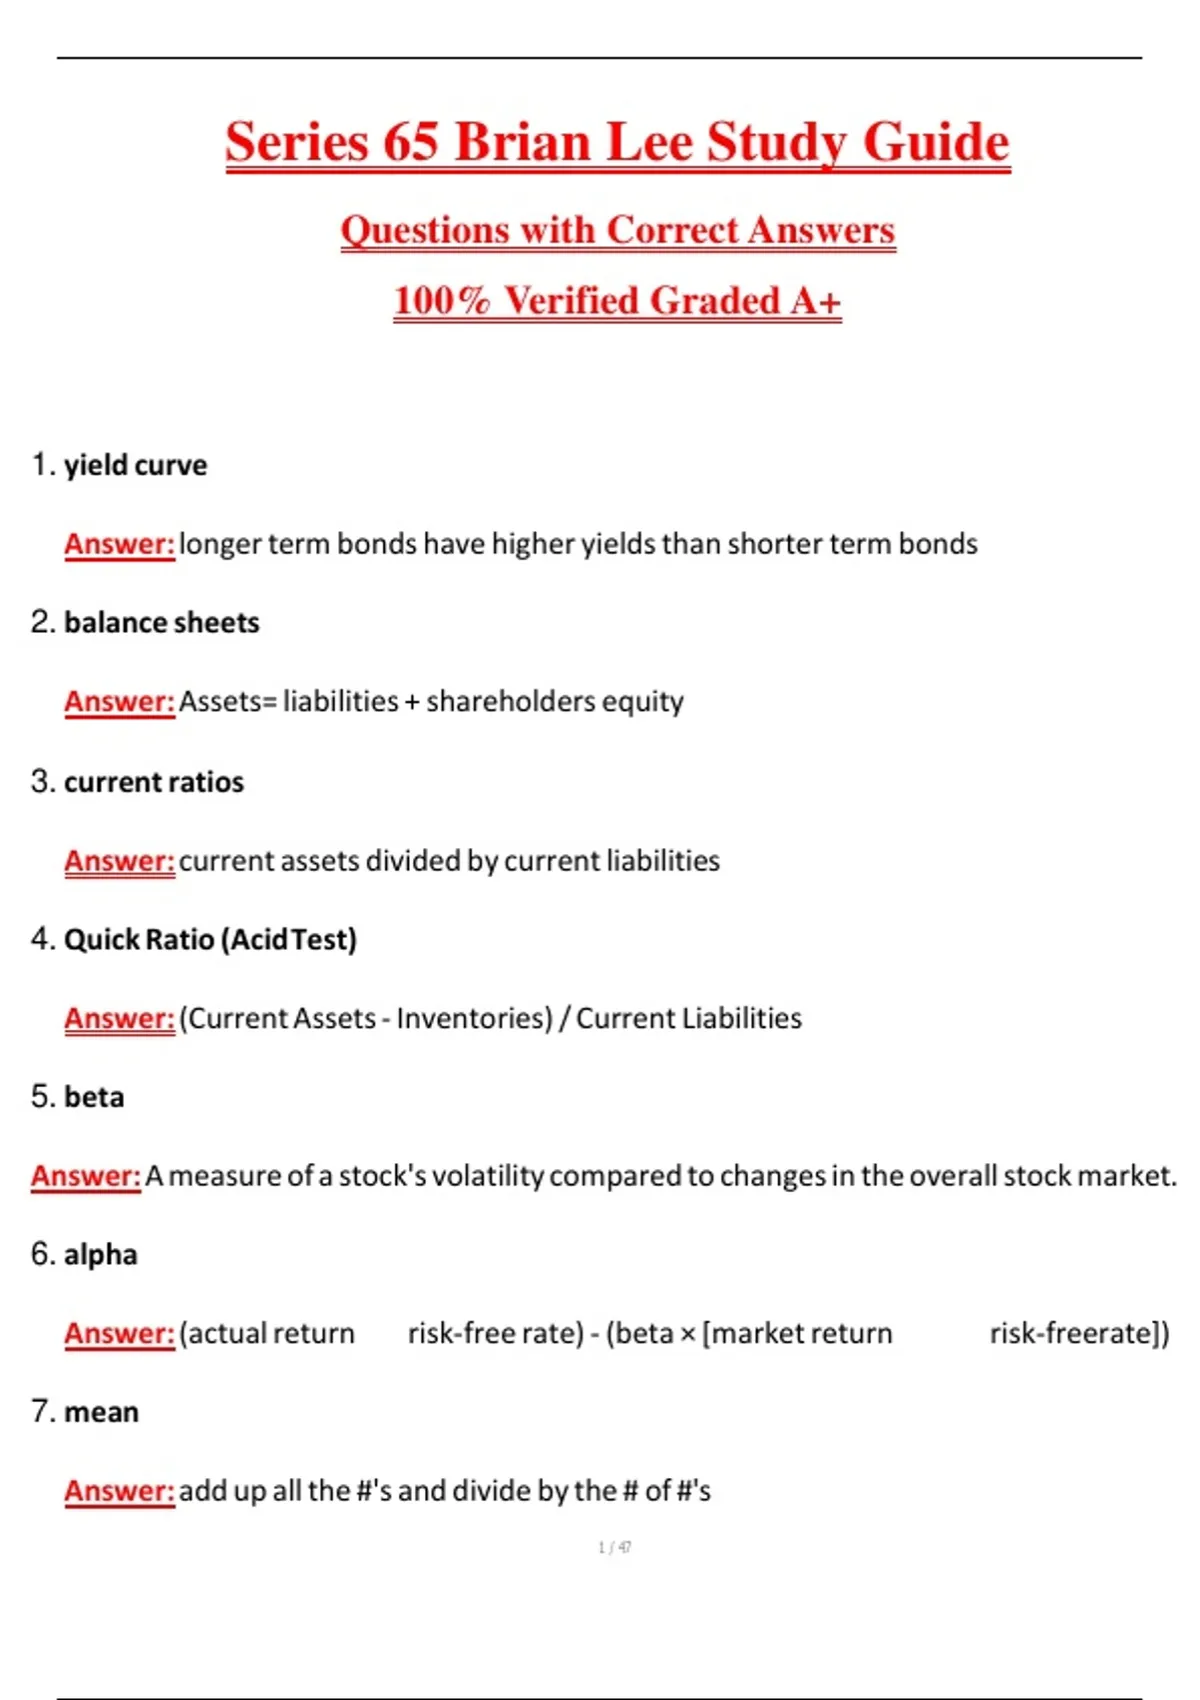
I recommend starting with the material you will rarely use in practice. The professional conduct section, ethics questions, and jurisdictional coverage are straightforward but easy to ignore until the last week. That is backwards. It is also the highest yield per hour you can invest. Three days covering the North American Securities Administrators Association model acts, state registration exemptions, and the uniform securities act definitions takes less time than most people expect and gives you a free buffer of twenty-five to thirty points on exam day. Then you move into the heavy math. Time value of money calculations, present value and future value problems, bond pricing with yield-to-maturity, and the fundamentals of portfolio beta. These are mechanical. You either know how to punch them in or you do not. The exam allows a basic financial calculator, and you should arrive knowing exactly which buttons to press without looking at the manual. I spent a full weekend drilling calculator shortcuts using a TI BA II Plus before my own exam. That alone cut my calculation time per question by roughly forty percent.
A Real Edge Case That Almost Got Me
Here is something most guides skip. The fiduciary duty question that hinges on the distinction between suitability and suitability under the fiduciary standard. On the Series 65, you are being tested on the investment adviser standard, not the broker-dealer standard from the Series 7. That means you must evaluate recommendations through the lens of best interest to the client, not merely whether the trade was suitable. I ran into a mock question during practice where both the suitability answer and the fiduciary answer looked correct because the recommendation was honestly a good fit. The trick was that the adviser had failed to disclose a material conflict of interest tied to a third-party payment. The answer was not that the trade was unsuitable. The answer was that the disclosure requirement was violated. Most students marked the trade outcome instead of the disclosure failure. That question style shows up roughly four to six times on the actual exam, and it is easy to miss if you are thinking like a broker rather than an adviser. The first is that the exam does not reward reading comprehension as much as it rewards pattern recognition. The questions are deliberately wordy. They bury a key fact about a client's risk tolerance or a product's fee structure inside three paragraphs of narrative. I started underlining the client's age, income, net worth, and liquidity needs in every practice question. That simple habit raised my mock exam scores from a shaky low sixty-something percentile to roughly eighty-five within two weeks. The second pitfall is over-studying the math and under-studying the code. The uniform securities act sections feel dry, but they dominate the professional conduct portion. You need to know the difference between the registration requirements for agents, brokers, and investment adviser representatives, and you need to understand exemptions like the covered securities under NSVOA versus state-level exemptions for small offerings. The math is fast to learn and easy to retain. The regulatory text is dense, repetitive, and easy to forget. Spending only a day on it is a mistake.
Get the Full Details

Tools and Resources That Actually Work
A solid Finra Series 65 Study Guide should include at least two thousand practice questions, not the usual five hundred that come bundled with cheap materials. I used a combination of a structured textbook and a separate question bank that mimics the computer-adaptive pacing of the real exam. The timing matters. The real test gives you roughly ninety seconds per question. If you are practicing without a timer, you are not actually preparing for the exam environment. Free resources exist, but they are scattered. The Finra website provides the candidate brochure and sample questions, which are useful but thin. State securities authority websites publish the model rules, which are worth reading if you want to understand the source material rather than just memorizing answers. I also found that reviewing the actual investment adviser act of 1940 sections referenced in the exam outline helped me connect dots that rote memorization never cleared up.
When the Study Guide Approach Fails
The main limitation of self-study is that you cannot simulate the exact cognitive load of the real room. You are taking practice tests in a quiet space with no time pressure and the ability to pause and check notes. The actual exam is timed, proctored, and unforgiving of hesitation. If your mock exam scores plateau below seventy percent, the problem is usually not knowledge. It is stamina and question management. I know this because I hit that wall myself. The workaround was switching to full-length, timed practice exams back-to-back for five days straight, treating it like a dress rehearsal. My accuracy dropped on the second exam of each day due to fatigue, but by the fifth day, my score consistency improved dramatically because I had trained my brain to maintain focus through the second hour. Another scenario where study guides fall short is for candidates who work full time in advisory roles. You already deal with compliance questions, client presentations, and product selection all day. Adding exam study on top of that is brutal. The practical workaround is front-loading the topics you encounter daily. If you spend your days working with retirement accounts, start with that section while it is fresh in your mind. Do not force yourself to study employee benefit plans at midnight when you are already mentally drained from a day of client meetings.
The Bottom Line on What You Need
You need a structured plan, a quality question bank, calculator fluency, and enough self-awareness to recognize when you are burning out rather than studying harder. The exam is manageable if you respect the weighting and do not get seduced by the easier-seeming topics at the expense of the fiduciary-duty nuances. Most people pass because they study smart for six to eight weeks. A smaller group passes because they cram with the wrong emphasis and get lucky on the random question distribution. I would rather be in the first group.