How Marginal Analysis Actually Works in Production
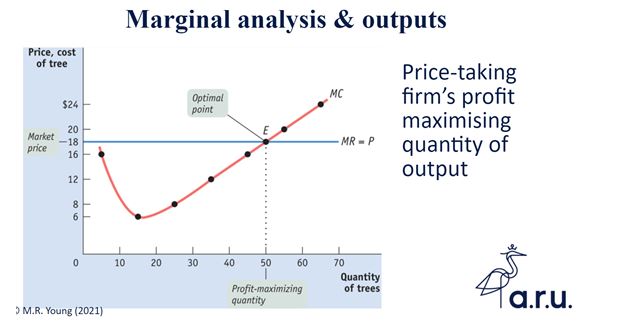
Marginal analysis is the process of comparing the additional revenue from producing one more unit against the additional cost of making it. That is it. Most businesses figure out their optimal output level by finding where marginal cost equals marginal revenue. If MR is higher than MC, you keep producing. If MC crosses MR, you stop. The math is straightforward. The execution is where people screw it up. The core idea here is simple enough. You look at each additional unit and ask two questions: can I sell it for more than it costs to make? Is there still demand at that price point? When the answer to both becomes no, that is your production ceiling. In practice, companies don't just look at a single data point. They model it across a range of quantities, usually with a spreadsheet or some kind of cost accounting system. They track variable costs per unit, fixed costs spread over volume, and then estimate the price they can realistically charge at each volume level. From that, they derive marginal revenue and marginal cost curves. The intersection gives them the quantity where profit per unit stops improving.
I have seen this go wrong in manufacturing settings where people used last month's cost data without adjusting for capacity utilization. When you are running at 40 percent capacity, your marginal cost looks deceptively low because fixed costs are buried in overhead. Push output up and suddenly you need overtime, extra shifts, or new equipment. The MC curve is not a flat line, and treating it like one will make you overproduce and lose money on the margin. The workaround I learned the hard way was to build the MC calculation around actual incremental costs, not accounting averages. That means tracking the real variable cost of the next batch, including the step-up in labor rates when you hit overtime thresholds, the energy cost of running an additional shift, and the maintenance acceleration that comes from pushing machines harder. In one case, running a second shift added 18 percent to per-unit labor costs once you factored in shift differential pay. Ignoring that pushed our optimal output level about 12 percent too high and wasted roughly forty thousand dollars a quarter in margin compression.
The Theory Behind the Method
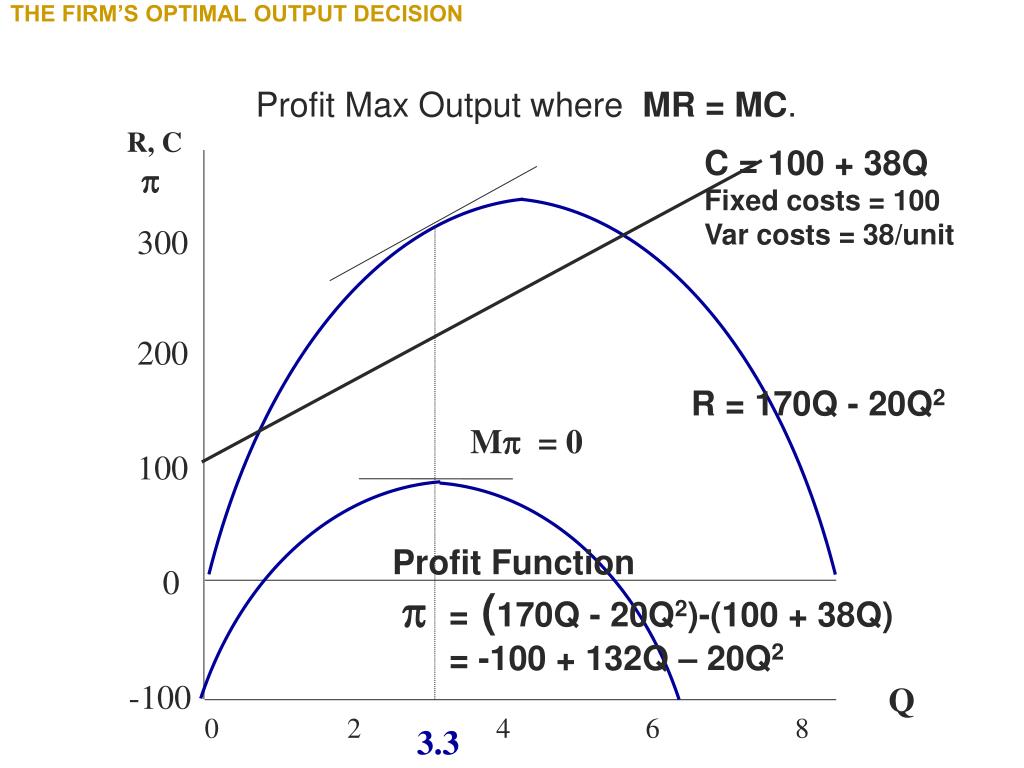
Microeconomics teaches that profit maximization occurs where MC equals MR. This comes from basic calculus. When the slope of the total cost curve equals the slope of the total revenue curve, any move away from that point reduces profit. It is a standard result. The problem is that real-world cost and revenue functions are rarely clean. Marginal revenue itself changes depending on your pricing strategy. If you sell at a single price, MR equals price only at the first unit. Every additional unit sold at the same price drops the average revenue across all units because to sell more, you often have to lower the price. That is the standard demand curve logic. In markets with price discrimination, like bulk discounts or subscription tiers, the MR calculation gets messier because each segment has a different willingness to pay. Marginal cost behaves similarly in ways textbooks simplify away. There are economies of scale that make MC fall as volume rises, then diseconomies that push it back up. The U-shaped MC curve is not just a drawing. It shows up when you deal with setup costs, learning curves, and capacity constraints. Understanding which side of the curve you are on matters more than most people realize.
Get the Full Details
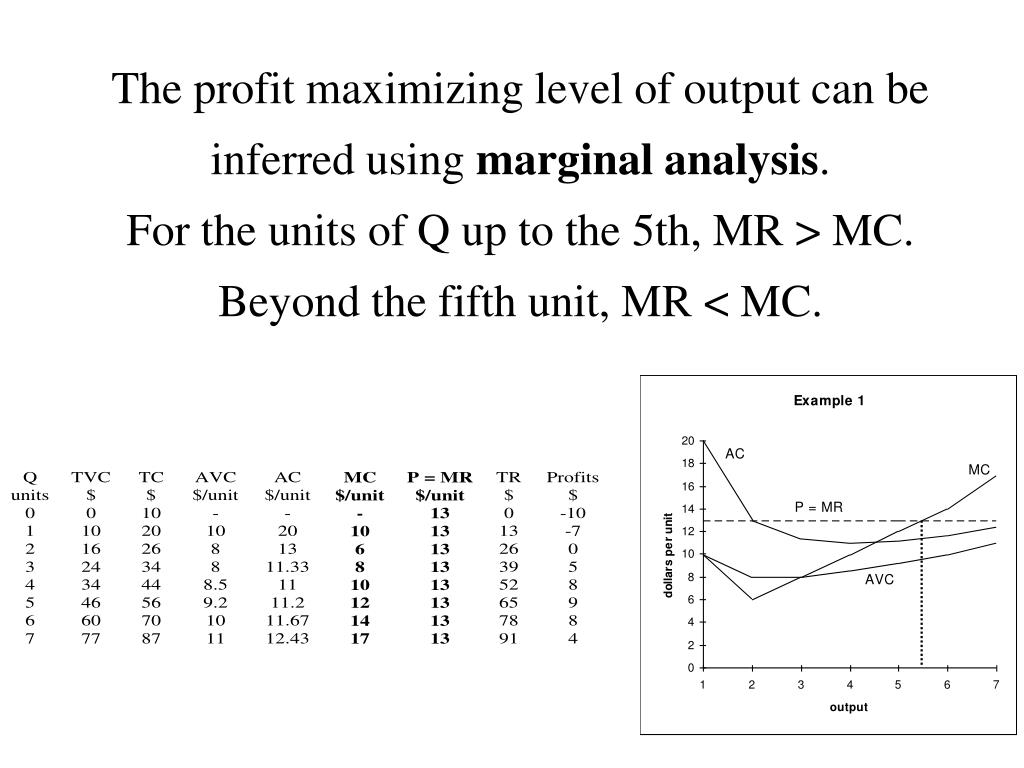
One counter-intuitive point that beginners consistently miss: producing below the MC equals MR point is not always wasteful. If demand is volatile and your marginal cost rises sharply near capacity, sitting slightly below that intersection can be the rational choice. You preserve optionality. You avoid the spike in costs that comes with scrambling to meet unexpected orders. In my experience, the firms that optimize purely for the theoretical maximum output often get crushed during demand swings because they optimized their cost structure to run flat-out at that exact point.
A Practical Example
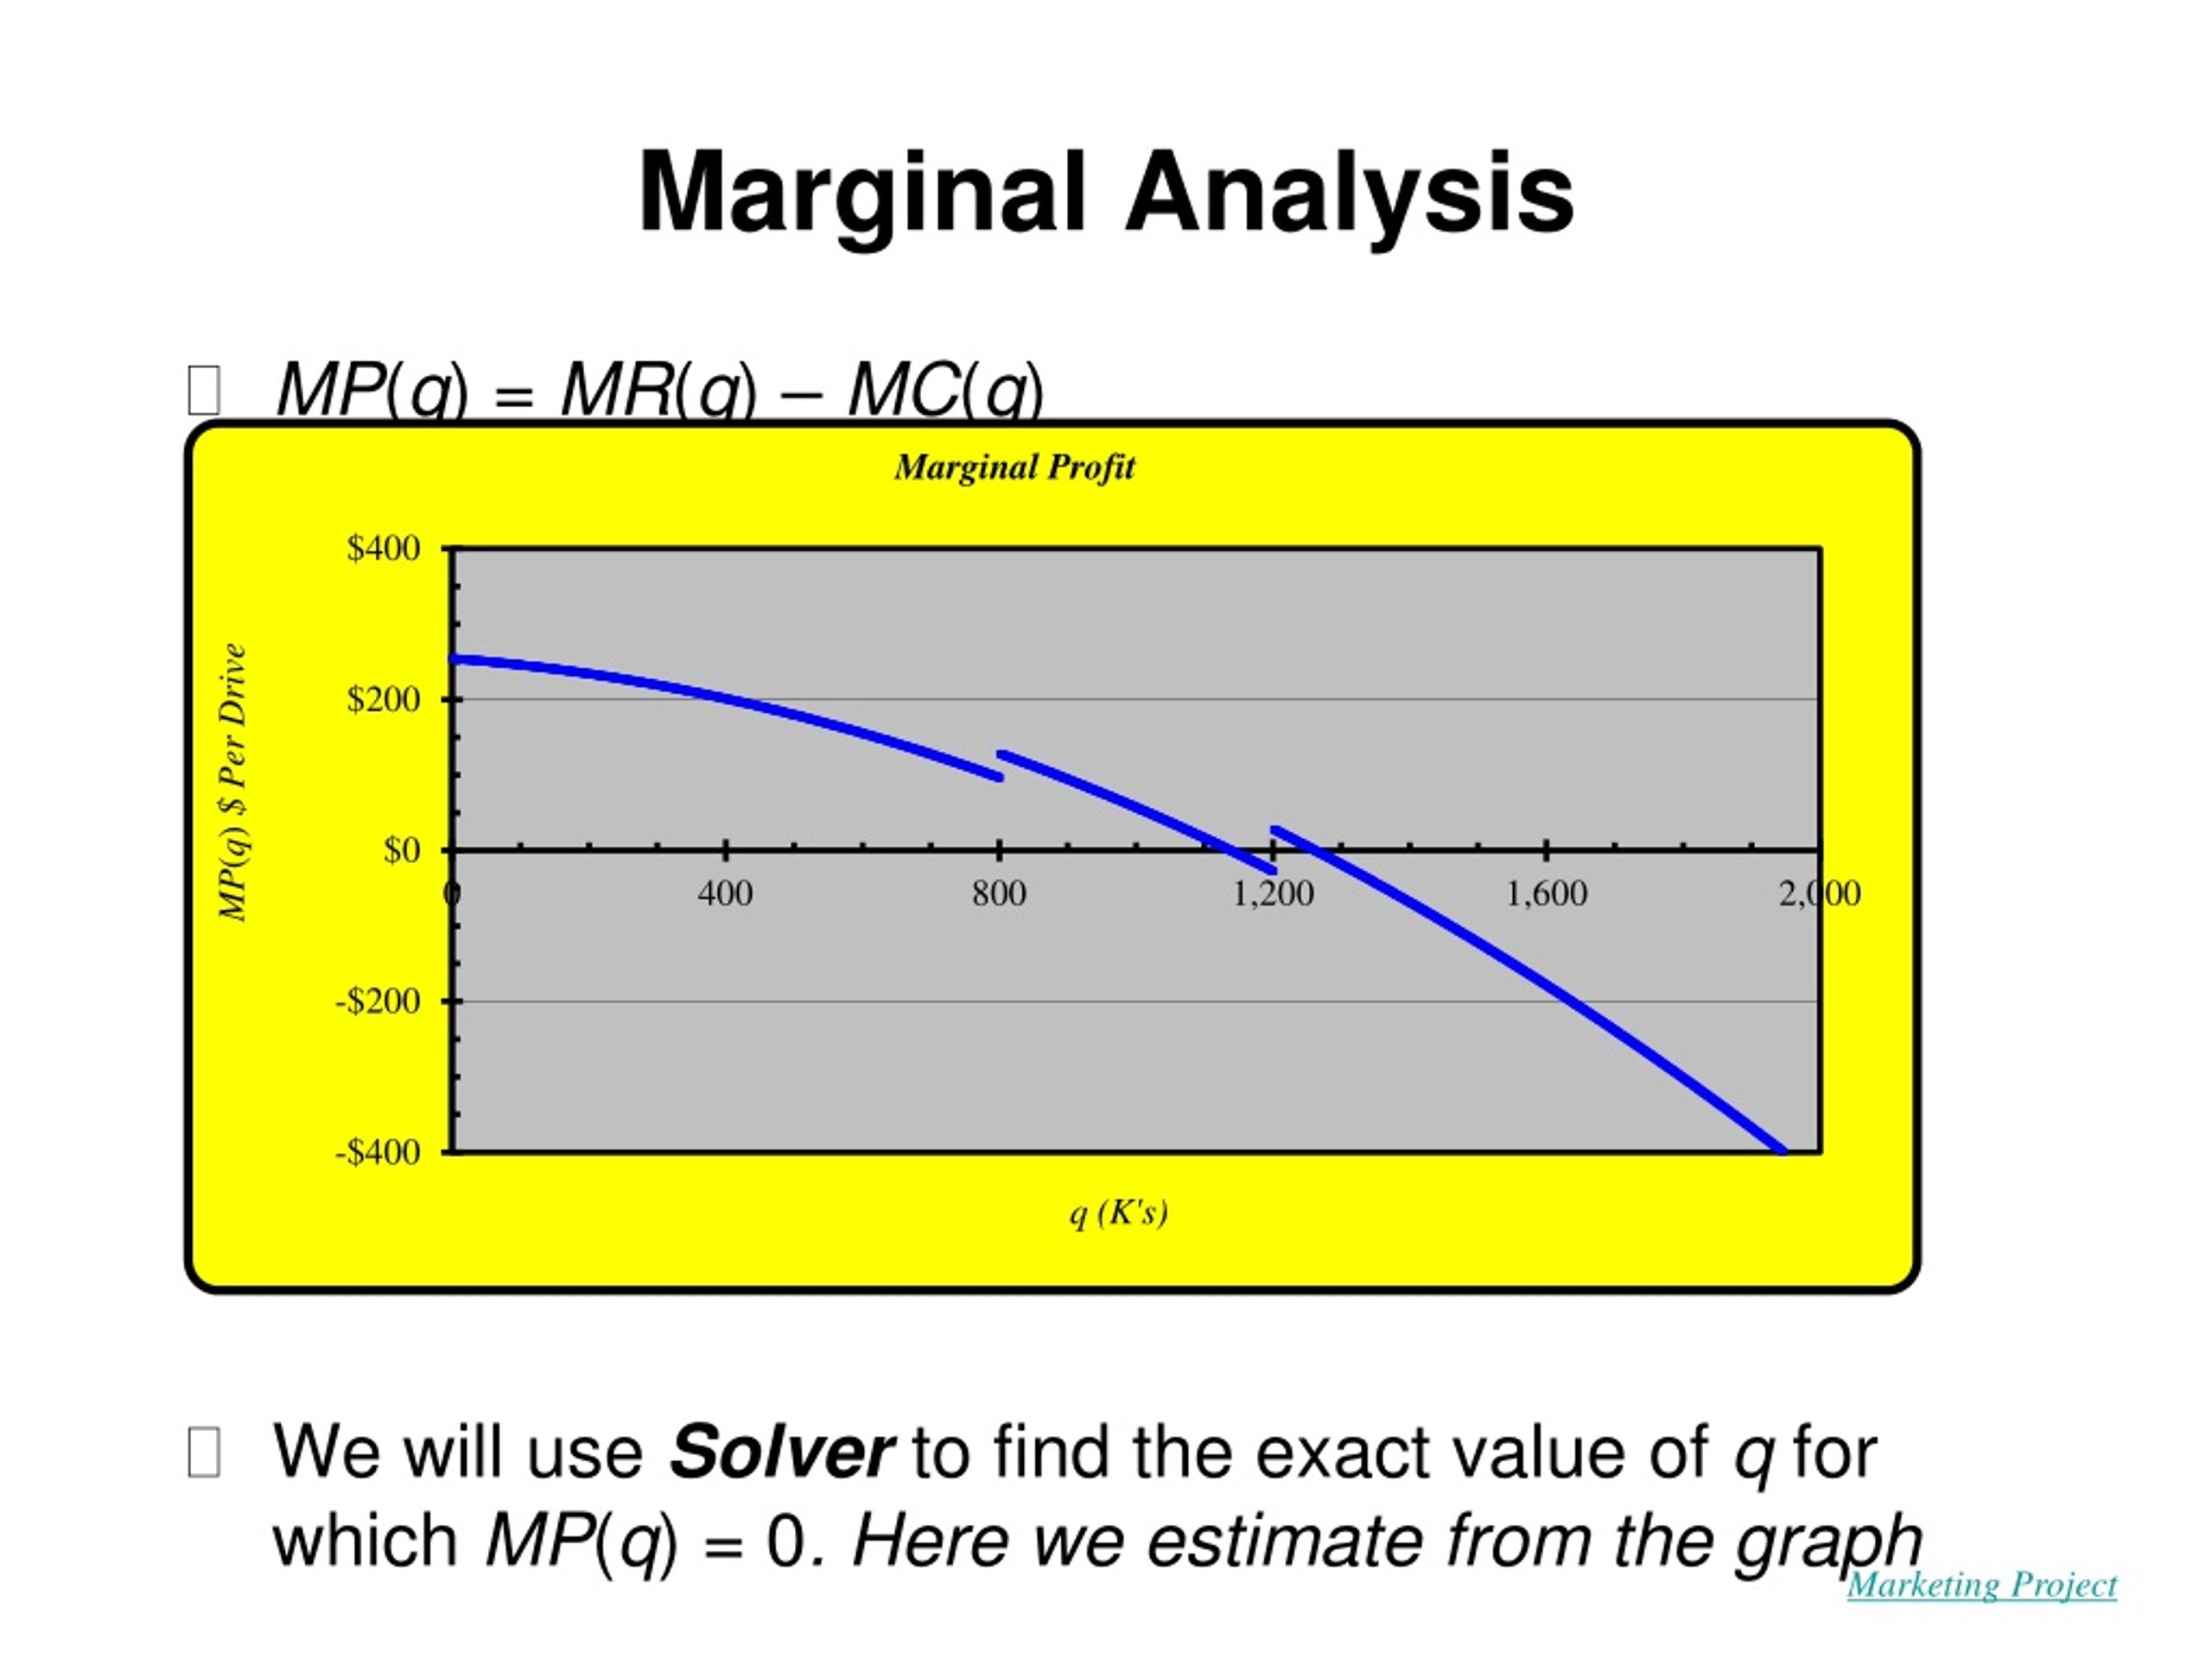
Let me walk through a concrete scenario. Suppose a manufacturer produces packaging film on a continuous extrusion line. The variable cost of raw polymer, energy, and direct labor works out to roughly $0.42 per meter at current volume. Each additional meter costs about $0.44 once you factor in the incremental energy draw and the slight quality reject rate that increases at higher line speeds. That is the marginal cost. The marginal revenue comes from the sales price. The current contract price is $0.71 per meter for high-volume buyers. So the marginal profit per unit is $0.27. At this price point, the company can sell another 15,000 meters per week before the buyer hits their own demand ceiling and starts negotiating harder on price. After that 15,000 meter threshold, the next batch of orders requires a price concession down to $0.68 per meter because the buyer has alternatives. That means MR drops to $0.68 for those incremental units. Now you recalculate. At $0.68 MR and $0.48 MC (because line speed increases raise the marginal cost), the profit per unit is only $0.20. The total marginal contribution from those extra units is smaller, but still positive. The firm should produce them because MR still exceeds MC. But once you push further and the MC climbs to $0.73 due to overtime labor and cooling system strain, you cross the threshold. MR is $0.68 and MC is $0.73. Every unit beyond that point loses money. That is your output limit.
The optimal production level in this example sits somewhere between 15,000 and 20,000 meters per week, depending on where the MC curve intersects the stepped MR. The exact number depends on how accurately you can forecast the buyer's willingness to pay at each volume bracket and how precisely you can measure the cost acceleration at higher line speeds.
Where This Method Breaks Down
Marginal analysis assumes you can reliably estimate both MC and MR. In many industries, that assumption falls apart. For service businesses with high fixed costs and near-zero variable costs, the marginal cost of one additional customer is almost meaningless. The MC curve is essentially flat near zero until you hit capacity, at which point it jumps vertically. The intersection with MR becomes a step function rather than a smooth curve, and the "optimal output" is either zero or capacity with no useful middle ground. In industries with long lead times, like capital equipment or construction, the marginal cost of a project decided today may not be incurred for six months. Price inputs change in that window. Currency fluctuations, commodity spikes, labor disputes. Your MC estimate from March is irrelevant by June. Firms that apply marginal analysis without building in a contingency buffer end up locking in projects that look profitable on paper but lose money in practice. Another failure mode is when markets are not competitive. In oligopolistic settings, marginal revenue depends on competitor reaction. If you increase output, rivals may cut price in response, making your MR lower than your straightforward demand calculation suggests. The math still works, but you need game-theoretic modeling rather than a simple demand curve to feed into it. Most small firms do not have that capability, and they treat the static MR estimate as truth.
If marginal analysis is giving you unreliable results because your cost structure is too lumpy or your market is too volatile, the alternative is to switch to scenario-based planning. Instead of looking for a single optimal point, you model three or four output scenarios with their associated cost and revenue distributions. You then pick the scenario that maximizes expected value or minimizes downside risk, depending on your tolerance. It is less elegant than the MC equals MR approach, but it is more honest about what you actually know.
Implementation Steps
Start by mapping your incremental costs. Not your average costs, not your full absorption costs. The costs that actually change when you produce one more unit. Raw materials, variable labor, energy, shipping, waste disposal. Track these at your current production level and at several higher levels to see how they behave as you approach capacity. Then map your incremental revenue. Look at your actual pricing data, not your list price. What do customers actually pay at different volume levels? Where do discounts kick in? What contracts expire and might get re-priced? Build a revenue schedule that reflects real transaction prices across a range of quantities. Plot the two schedules against each other. Identify the quantity where marginal cost first exceeds marginal revenue. That is your stopping point. Verify it by checking whether the profit contribution from units around that point actually turns negative. If your data is noisy, run the calculation quarterly and compare the results. Drift in the optimal output level usually signals a change in your cost structure or market conditions that you need to address.
Do not treat this as a set-and-forget exercise. Marginal analysis is a snapshot tool. It tells you where you should be right now given current conditions. It does not predict changes in input prices, demand shifts, or competitor behavior. The firms that use it well revisit the calculation regularly, usually monthly or quarterly depending on how fast their cost and revenue environments move.