Understanding the First Time Home Buyer Mortgage Calculator
A First Time Home Buyer Mortgage Calculator is simply a tool that estimates your monthly housing payment based on the purchase price, down payment, interest rate, and loan term you input. Most people treat it as a single number generator, but the output is really a breakdown of several moving parts. Principal and interest, property tax, homeowner's insurance, and possibly private mortgage insurance (PMI) all feed into that final monthly figure. Understanding what each piece contributes matters more than memorizing the final result. Enter the home price first. Then your down payment amount or percentage. Next, the interest rate and the loan term in years. Hit calculate. The tool will typically split your payment into principal and interest, escrow components (taxes and insurance), and PMI if your down payment is under 20 percent. That last part is where people get tripped up. Lenders often require PMI on conventional loans below 20 percent, but some government-backed programs like certain FHA or USDA loans have different structures. Make sure your calculator is factoring in what your actual loan type requires, not just a generic estimate. I ran into this exact problem last spring while helping a buyer who was comparing offers. She had two mortgages side by side. One showed a monthly payment of $1,850 from a standard calculator. The other came out to $2,100 because the first tool was missing HOA fees and the second included them. Both were technically correct based on what you fed them. The lesson here is that no calculator knows your HOA, your state tax rate, or your insurance premium unless you type it in. If you leave those fields blank or use defaults, you are looking at a fantasy number, not a realistic one.
The formula behind the principal and interest portion works like this. You take your loan amount, divide the annual rate by twelve to get the monthly rate, multiply the loan term by twelve to get the total number of payments, then apply the standard amortization formula. Most online calculators handle this instantly. The real skill is feeding it accurate data.
What People Usually Miss
Property tax variations by county are the biggest blind spot. Two homes on the same street in different school districts can have wildly different annual tax bills. If your calculator lets you set a flat percentage, research your specific county's effective tax rate before entering a number. Similarly, homeowner's insurance varies by construction type, location, and coverage level. A wooden frame home in Florida costs significantly more to insure than a brick home in Ohio. Plugging in generic averages will skew your results enough to make two very different scenarios look identical. Another thing that trips people up is the difference between the interest rate and the annual percentage rate, or APR. The interest rate is what you see advertised. The APR includes the interest rate plus closing costs and other fees rolled into the financing. When comparing two loans from different lenders, the one with the lower interest rate might actually cost more overall if it carries higher fees. A thorough First Time Home Buyer Mortgage Calculator will show you both numbers separately so you can see the full picture.
Get the Full Details
Common Pitfalls and Where These Calculators Break Down
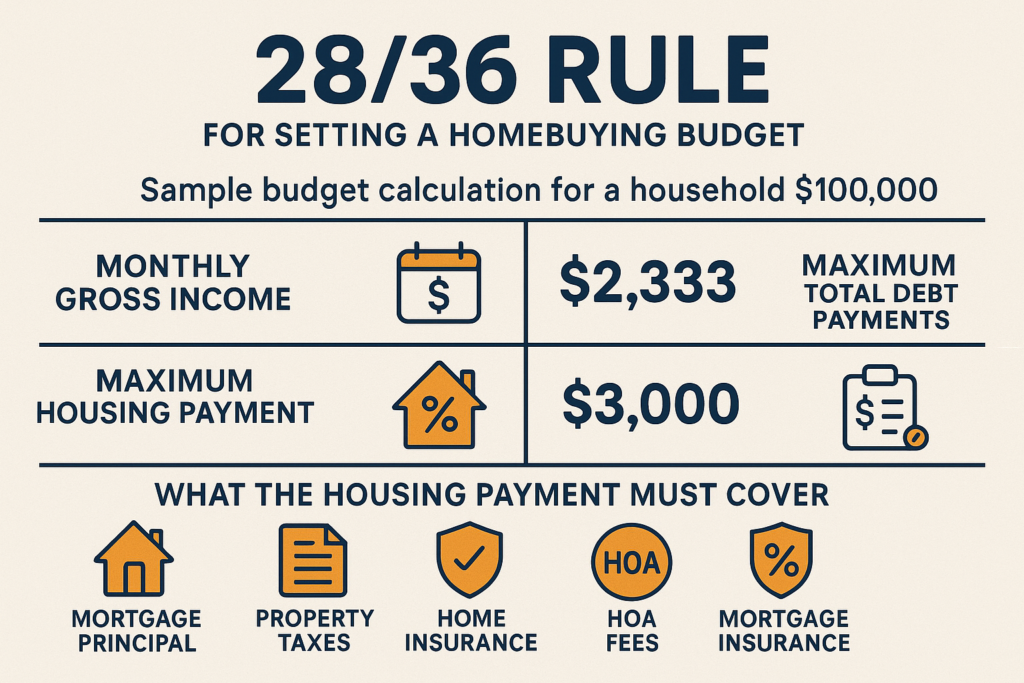
Online calculators assume your situation is static. They do not account for adjustable-rate mortgages changing over time, property tax reassessments, or insurance premium increases. If you enter a five-year fixed rate but plan to sell or refinance before that period ends, the calculator still projects the full thirty-year cost unless you adjust the inputs manually. This is not a flaw in the tool. It is a limitation you need to work around by running multiple scenarios instead of relying on a single output. Debt-to-income ratio is another area where calculators fall short. Your monthly mortgage payment is only one component of your DTI. Student loans, car payments, credit card minimums, and child support all factor into what a lender will actually approve you for. A calculator might tell you that you can afford a $350,000 home, but your lender could cap you at $280,000 because of existing debt obligations. Always run your numbers through both a standalone calculator and a lender's pre-approval assessment to get a realistic ceiling. There is also the issue of discount points. Paying points upfront lowers your rate but increases your closing costs. A basic calculator will show you the reduced monthly payment but will not necessarily highlight the break-even point. I once had a client who paid two points to drop her rate from 6.75 to 6.25 percent. The calculator showed savings of about $85 per month. She figured she would break even in twenty months. She ended up selling the house in fourteen. The points cost her more than they saved. Running a break-even analysis should be a separate step after you get the base calculation.
Practical Tips for Getting Useful Numbers
Start with three to five different calculators from reputable sources and compare the outputs. If they all land within a narrow range, you have a reliable baseline. If they vary by hundreds of dollars, dig into the assumptions each one makes. Look for calculators that let you toggle property tax rates, insurance costs, PMI requirements, and HOA fees independently. Those tend to produce more accurate results than the simplified ones that ask for only three inputs. Set aside a buffer in your own mental math. Add roughly 10 to 15 percent above whatever the calculator returns for principal, interest, taxes, and insurance. That buffer covers unexpected assessments, higher insurance premiums, or utilities that the calculator never accounts for. It also prevents you from stretching to the absolute maximum your payment would allow. Living inside your calculated budget leaves no room for mistakes or market changes. If you want to download a spreadsheet version for more control, search for Excel or Google Sheets templates built for mortgage amortization schedules. These let you adjust every variable and see how small changes compound over time. A $5,000 increase in down payment might reduce your monthly payment by $30, but it could also eliminate PMI entirely depending on your loan amount and type. Spreadsheets reveal those nonlinear effects better than a web form ever will.
One last detail that catches people off guard. Some calculators assume your property taxes are paid monthly through an escrow account. Others assume you pay them annually or semi-annually. The actual cash outflow is the same, but the monthly payment display changes. If you are comparing offers from different lenders, make sure you are looking at the same payment structure. Otherwise you are comparing apples to oranges and drawing the wrong conclusion about which loan is cheaper.