Getting Through the First-Time Purchase Without Losing Your Shirt
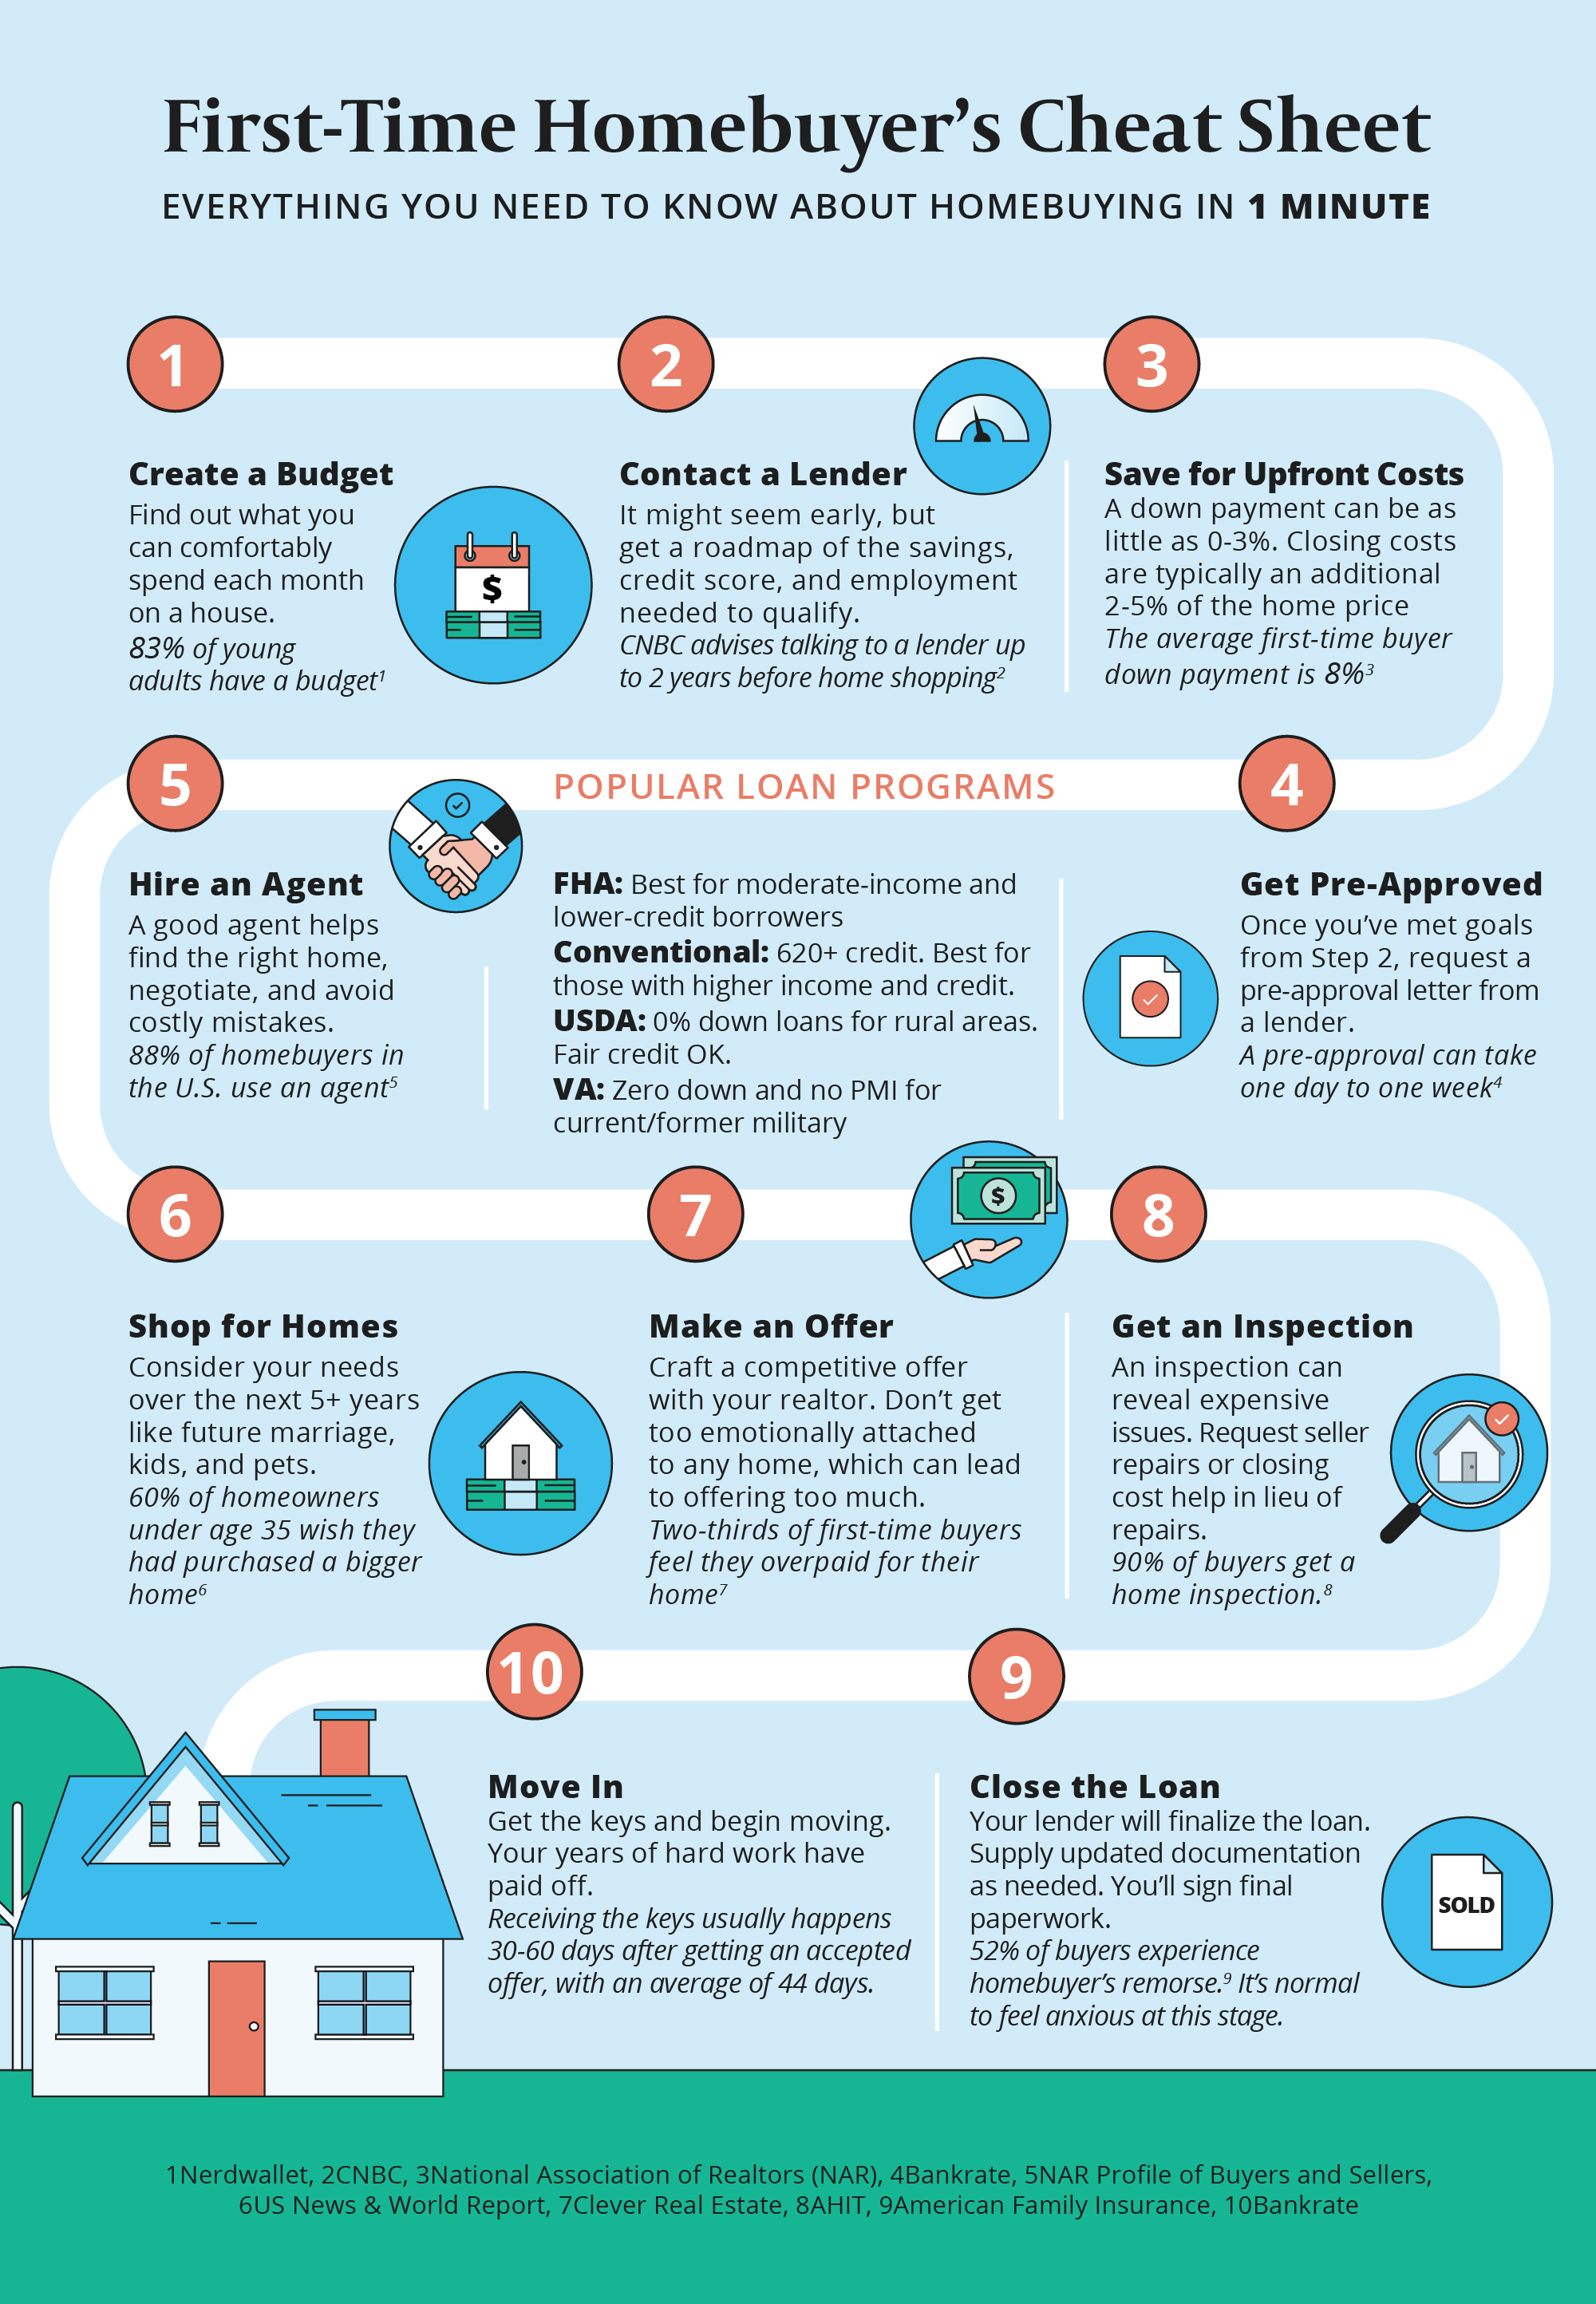
The pre-approval letter is the thing that actually matters. Not the Instagram-worthy open house, not the paint swatches, not the neighborhood you fell in love with. The letter from a lender telling a seller you have the financial capacity to close. Without it, your offer is basically noise. I learned this the hard way when I submitted what I thought was a strong offer on a condo in 2019. The seller rejected it outright. Turns out the buyer next in line had a pre-approval from a national bank with institutional weight behind it, while mine came from a local credit union nobody on the listing side had heard of. The difference was maybe a week's worth of processing time and a slightly different tone deck. But perception is everything in a bidding environment. So you start by finding a lender who moves fast and will give you a real letter, not some generic pre-qualification PDF. Then you lock your rate. Rate locks typically run 30 to 60 days. If your closing drags past that window, you either pay a float-down fee or eat a higher rate. I once watched a friend pay $800 for a float-down because his inspector found mold three days before close and the deal stumbled. That $800 kept his rate at 6.25% instead of jumping to 6.875%. Worth every penny in that scenario.
What a First Time Home Buyers Guide Actually Covers
A proper First Time Home Buyers Guide isn't just a list of steps you can skim. It has to address the gaps most beginners never see coming. Down payment assistance programs, for example. Every state has them. Most first-time buyers don't know they exist. Some offer forgivable loans that disappear after five years of occupancy. Others are deferred-payment second liens with zero interest. In Texas, the My First Texas Home program pairs a 3% down payment with a competitive fixed-rate mortgage and no monthly second-mortgage payment. In California, the CalHFA First Home Loan offers down payment help up to 6% of the purchase price. These programs stack with FHA or conventional loans depending on the state. A guide that skips this is doing you a disservice. Another thing usually glossed over is the appraisal gap. Lenders require the home to appraise at or above the contract price. If it comes in low, you're on the hook for the difference unless your contract has an appraisal contingency that lets you walk. I had a client once in a seller's market where every offer in the area was 10% over list. She bought at $425,000 against a $390,000 list price. The appraisal came in at $405,000. The gap was $20,000. Her contract had no appraisal gap coverage. She either brought $20,000 cash to close or cancelled. She cancelled and lost her earnest money deposit of $8,500. If the guide you're reading doesn't explain appraisal gap clauses and how to negotiate them into your contract, it's incomplete. Then there's the inspection contingency window. In competitive markets, sellers push for two-day inspection periods. Two days. You're scheduling a home inspector, a pest inspector, and sometimes a roof specialist all within 48 hours. That's tight. The workaround I use with my clients is to bring a generalist inspector on day one for a broad scan and a specialist on day two if something looks questionable. It costs more upfront but prevents the nightmare of discovering foundation cracks after you've already waived your right to negotiate.
The Numbers Nobody Talks About
Closing costs run 2% to 5% of the purchase price. On a $350,000 home that's $7,000 to $17,500 sitting outside your down payment. Title insurance, escrow fees, recording fees, transfer taxes, lender origination charges, credit report fees, flood certification, survey costs if required, HOA transfer fees if there's a homeowners association. Each line item is real. I keep a spreadsheet for every transaction and it never lies. One of my recent deals had a $1,200 HOA transfer fee that the buyer's agent didn't mention until three days before closing. That's a $1,200 surprise that doesn't show up in any standard first-time buyer checklist. Pmortgage insurance is another one. If you put down less than 20%, you're paying PMI on a conventional loan or MIP on an FHA loan. On a $300,000 conventional loan with 5% down, PMI runs roughly $125 to $200 per month depending on your credit score and loan terms. That's $1,500 to $2,400 a year. FHA MIP is worse because it's charged for the life of the loan if you put less than 10% down. I had a client who stayed in an FHA loan for seven years at 3.5% down and paid over $14,000 in MIP before she could refinance it out. A conventional loan at the same rate would have let her drop PMI once she hit 20% equity. That's a $14,000 difference that changes the math significantly. HOA fees also deserve real attention. Some communities charge $200 a month. Others charge $600. In Florida, certain condo associations have reserve requirements that trigger special assessments when the reserve fund runs low. I worked a deal in Naples where the condo association was six years behind on roof replacement. The monthly HOA was $450, which looked manageable until the special assessment hit for $18,000 per unit. The buyer backed out after the disclosure came to light. The seller had been vague during negotiations. Special assessments are legal obligations, not optional community enhancements.
Get the Full Details

Working with Real People
Your agent matters more than you think. I've seen good agents save buyers $15,000 to $30,000 through negotiation alone. Not on the purchase price always, but on concessions, repair credits, and closing cost assistance. A bad agent will push you toward the first house you see because it's an easy sale. A good agent will show you twelve houses and steer you away from five of them based on things you wouldn't notice on your own. Things like drainage patterns, neighborhood noise at odd hours, electrical panel upgrades that are due, water heater age. These are the details that compound over time. The title company is equally important. They're the ones doing the actual title search, clearing liens, and issuing the insurance policy that protects your ownership. I've encountered a title company in Georgia that missed a mechanics lien from a contractor who worked on the previous owner's addition ten years prior. The lien surfaced during escrow and held up the close for eleven days. The contractor was owed $8,400. The buyer had to cover the holdup costs in temporary housing while the title company scrambled to resolve it. A competent title search would have caught that. Shop around for your title company. Don't just accept the one your agent recommends without checking reviews and response times. Your home inspector should be independent. Never use an inspector recommended by the seller or the listing agent. I've seen too many cases where a friendly inspector overlooked obvious issues to keep the deal alive. Get a referral from someone who has no stake in the transaction. The inspection itself takes two to four hours for a typical single-family home. Don't rush through it. Show up. Walk the property with the inspector. Ask questions. The answers you get in person are worth more than the written report you receive later.
When the Process Breaks Down
Most deals fall apart for predictable reasons. Financing falls through because the buyer's employment changes mid-escrow. A self-employed buyer starting a new business gets denied because their tax returns don't align with the income they qualified on. A borrower gets a new car payment the week before closing and their debt-to-income ratio pushes them over the limit. These happen constantly. The workaround is straightforward: don't make any financial changes between approval and close. No new credit cards, no large purchases, no job changes. Keep everything exactly as it was on your application. Sometimes the home doesn't appraise and the seller won't budge on price. That's when you need to understand your exit options. If you have an appraisal contingency, you can walk with your earnest money intact. If you waived the contingency to make the offer competitive, you're in a tougher spot. The solution in those cases is often a second appraisal. Some lenders allow this for a fee of $300 to $500. A second appraiser might come in higher if they used different comparable sales. It's not guaranteed but it's a tool worth having in your pocket before you waive contingencies. There's also the issue of home warranties. They cost $400 to $600 annually and cover major systems and appliances for a year. Most buyers think they're a must-have. They're not. A well-maintained HVAC system, a roof under ten years old, and appliances with remaining manufacturer warranties make a home warranty largely redundant. I once had a client who spent $550 on a warranty and filed one claim for a leaky dishwasher that was denied because the installer hadn't followed code. The deductible was $75 and the claim was rejected anyway. So they paid $625 for nothing. Home warranties have limits and exclusions you need to read before buying one. The fine print matters more than the marketing brochure.
Building a Real Strategy
The best approach I've seen combine four elements working together. First, get pre-approved with a lender who understands your specific situation, whether that's self-employment, credit repair, or down payment assistance. Second, work with an agent who knows the micro-markets in your target area, not just the broader city. Third, budget for the full cost of ownership including insurance, taxes, HOA, maintenance, and utilities. Most first-time buyers forget maintenance. Set aside 1% to 3% of the home's value annually for repairs. A $350,000 home needs $3,500 to $10,500 per year for routine upkeep. That's not optional. Fourth, understand the timeline. A typical transaction runs 30 to 45 days from contract to close. But that's assuming nothing goes wrong. Delays happen. Inspections reveal issues. Appraisals come in low. Lenders request additional documentation. Weather disrupts deliveries. The holiday season slows everything down. Plan for the longest reasonable timeline and then add a buffer. If you need to be moved into by a certain date, start the process at least two months before that date. Rushing a purchase is how people make mistakes that cost them thousands. The bottom line is that buying a home for the first time is less about finding the perfect house and more about navigating a system designed to extract money from people who don't understand how it works. Know your numbers. Read every document. Ask questions even when you feel like you're bothering someone. The people you're working with have heard every question before. The ones who get annoyed are the ones you should avoid. The transaction will move at the speed of the slowest participant. Make sure you're not that participant by staying organized, staying proactive, and keeping your finances stable from pre-approval all the way to the closing table.