Flexible Budgets And Performance Analysis
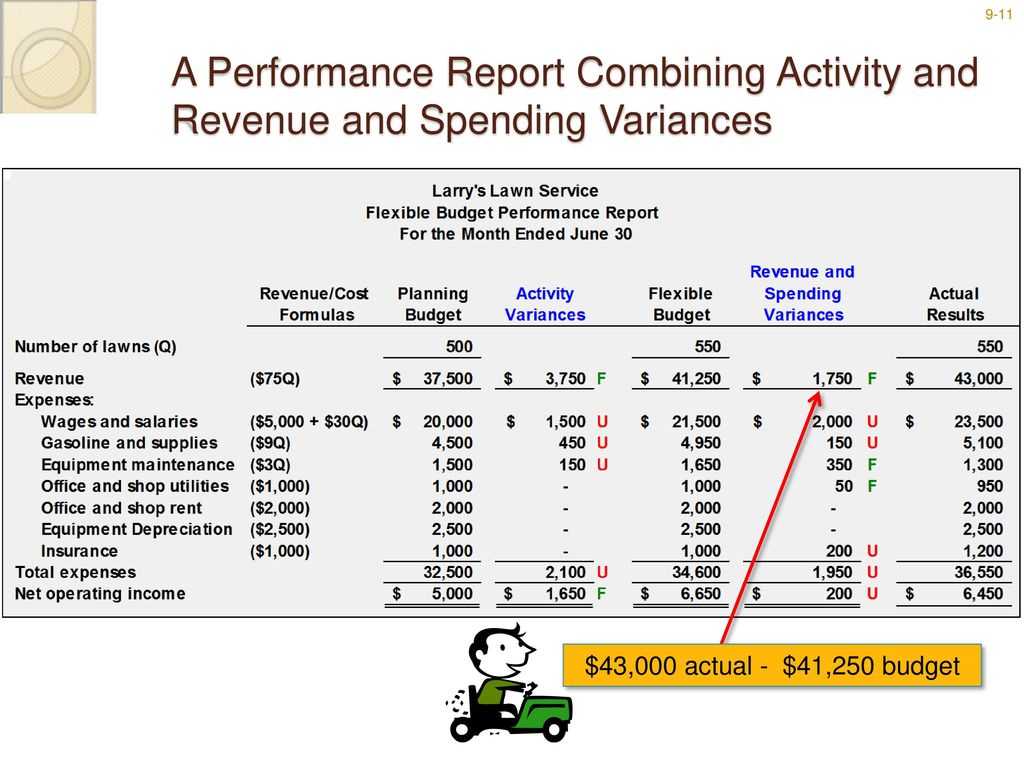
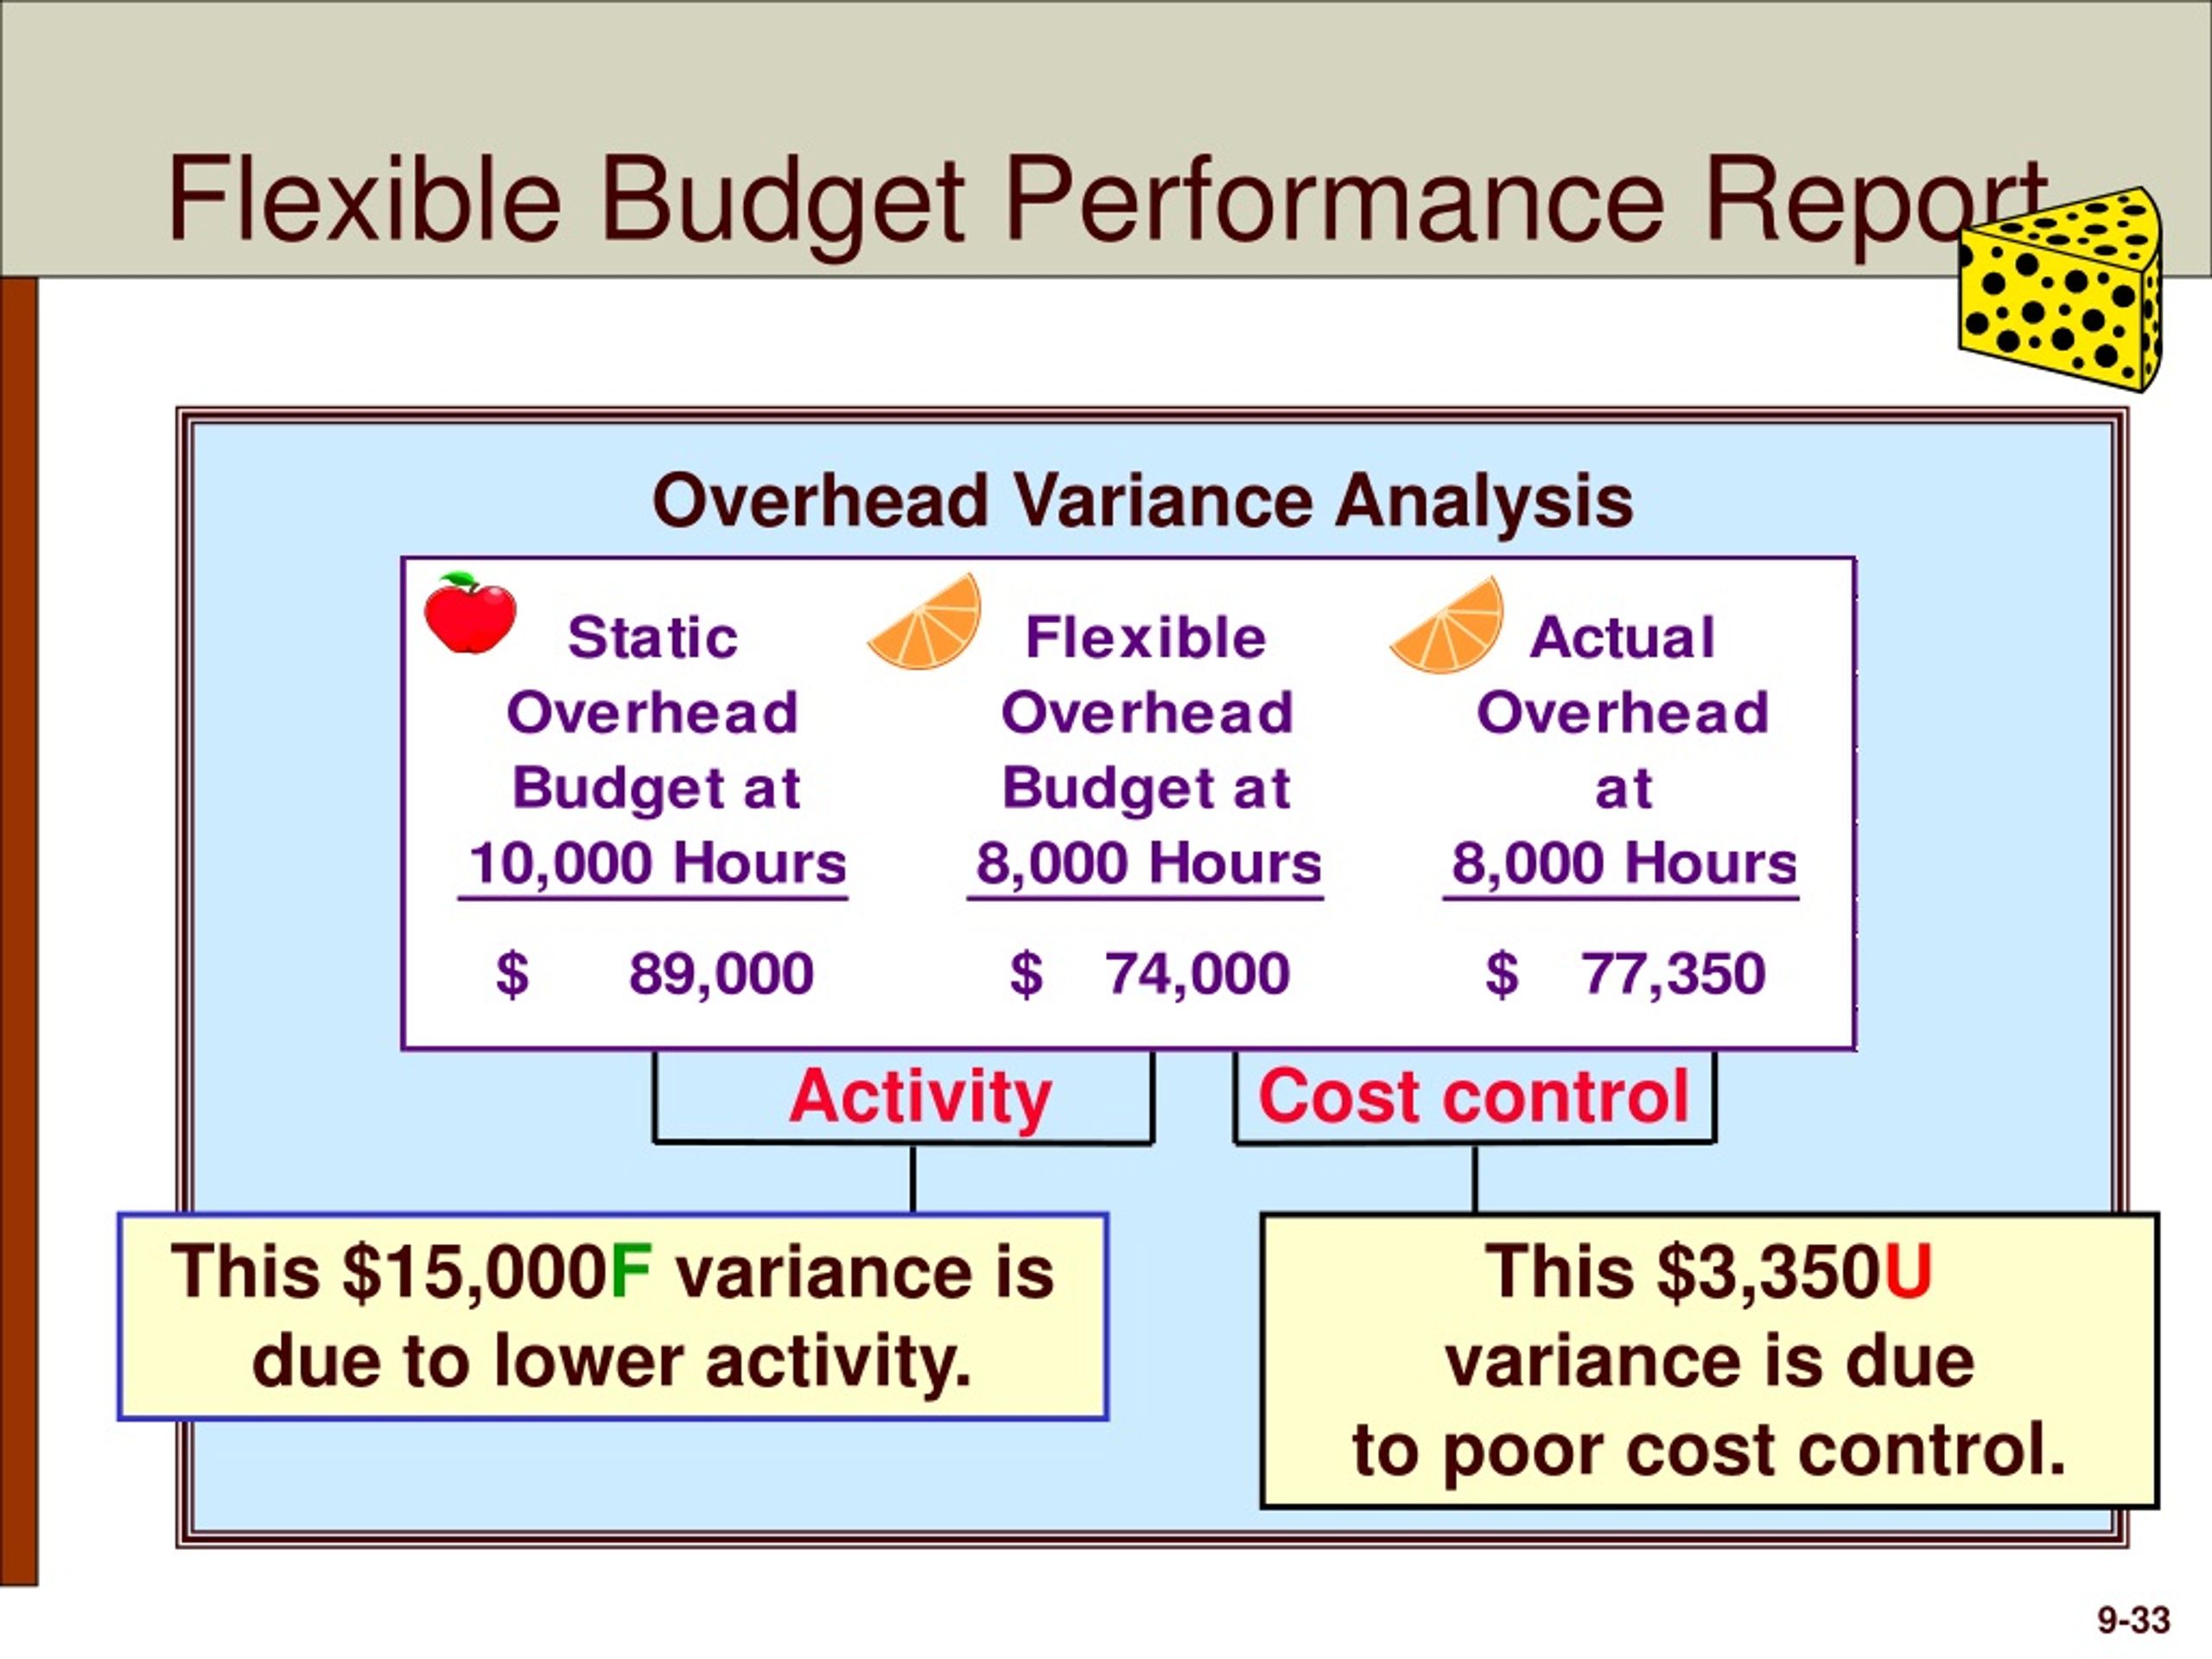
A flexible budget adjusts your expected costs based on what actually happened, not what you guessed would happen at the start of the year. That is the whole point. Static budgets let you compare apples to oranges. You planned for 8,000 units. You actually produced 10,400. Your revenue looks great, but your overhead looks overspent by half a million dollars on paper. The flexible budget fixes that by recalculating what your costs should have been at 10,400 units, then comparing that adjusted amount to your actual results. There are two separate comparisons happening here. The activity variance shows the impact of producing more or less than you originally planned. The revenue and spending variances show whether you actually spent more or less than the flexible budget allows for that level of activity. Most people lump these together and get confused about who is responsible for what. Operations usually owns the activity variance. Department managers own the spending variance.
The Practical Setup
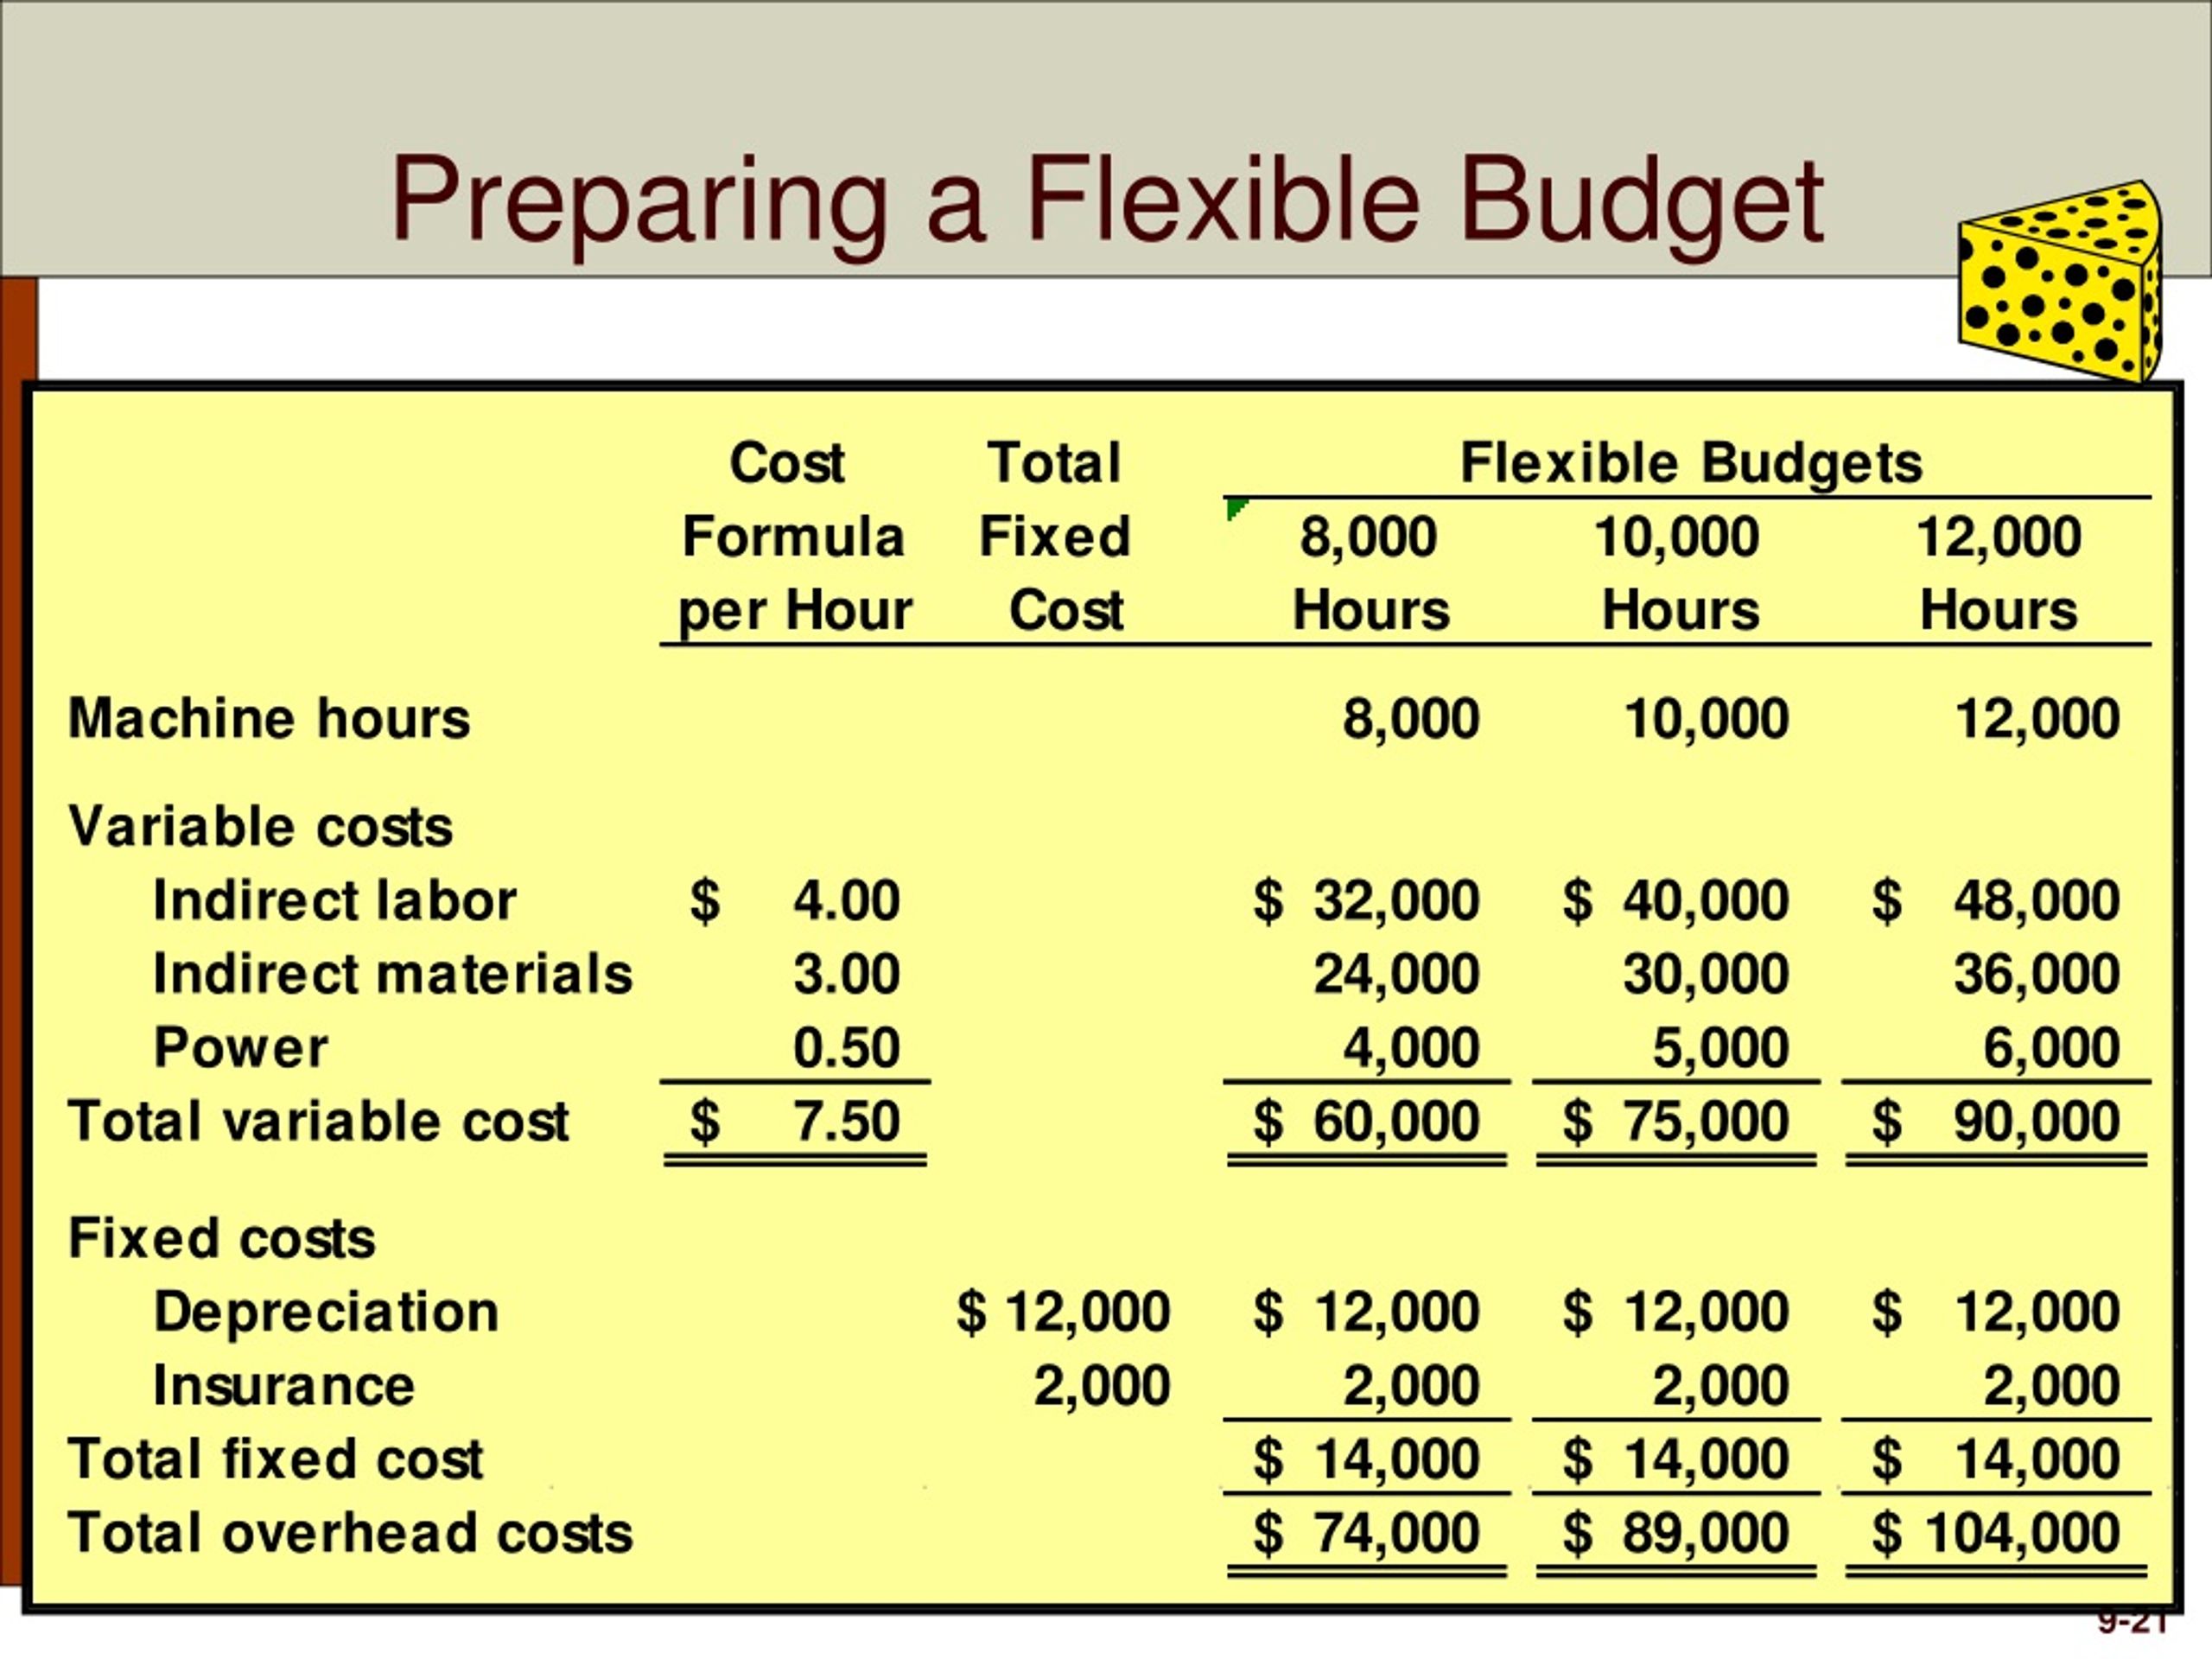
Start by separating your costs into fixed and variable. This is where most companies mess up because they use rough estimates instead of running regression analysis or reviewing historical data month by month. I have seen people categorize a cost as variable when it was actually fixed with a step function. The variance report then blamed the production manager for a cost that had nothing to do with output volume. Here is a straightforward method. Take each line item from your static budget. Identify the cost driver. For direct materials, it is units produced. For indirect labor, it might be machine hours. For utilities, it could be square footage or production time. Calculate the budgeted rate per driver unit by dividing the static budget amount by the expected driver volume. Then multiply each rate by the actual driver volume to build the flexible budget. The difference between the flexible budget amount and the actual cost is your spending variance. The difference between the static budget amount and the flexible budget amount is your activity variance. I spent three weeks on this once with a manufacturing client whose plant ran two shifts on some days and one shift on others. Their activity level swung wildly week to week. The standard flexible budget model assumed a straight linear relationship between units and overhead. It completely missed the reality that certain costs were step-fixed. They needed an extra supervisor on second shift. That supervisor did not show up as a variable cost in the model. The flexible budget kept blaming the shift supervisor for variance even though the budget never accounted for the second-shift premium in the first place.
The workaround was straightforward. I broke overhead into three buckets: pure variable, step-fixed at certain volume thresholds, and purely fixed. I then ran the flexible budget calculation with those step functions built in. Instead of one formula for all overhead, I used conditional logic based on shift count and volume bands. The variance report became legible. The shift manager finally had accurate accountability instead of being penalized for something the budget model ignored.
Get the Full Details

Common Mistakes That Wreck the Analysis
Using a single predetermined overhead rate across all product lines is a lazy shortcut that produces misleading variances. Different products consume overhead differently. A high-complexity custom part and a basic commodity part will both absorb overhead at the same rate in a traditional system, but the flexible budget will treat them identically even though their actual cost drivers diverge significantly. Activity-based costing principles applied to the flexible budget stage actually solve this without requiring a full ABC system overhaul. You just need multiple cost pools with their own drivers. Another mistake is treating the flexible budget as a one-time exercise. It should be updated whenever there is a material change in your cost structure. If you renegotiated a supplier contract in March that changed your direct material price by twelve percent, your flexible budget needs to reflect that new rate going forward. If you keep using the old rate, your spending variance will be consistently and incorrectly negative, making it look like the purchasing team is doing great when they are actually barely keeping pace. Revenue variances also get mishandled. People often calculate the sales volume variance using standard prices instead of separating it into a price variance and a quantity variance. The correct approach uses the difference between actual selling price and standard selling price multiplied by actual quantity sold to isolate the price effect. Then you take the difference between actual quantity and flexible budget quantity multiplied by the standard price to capture the volume effect. Mixing these together obscures whether you sold more units at a worse price or fewer units at the right price.
Where This Method Falls Apart
Flexible budgets assume cost behavior is predictable and linear within a relevant range. That assumption breaks down fast in industries with high fixed costs and volatile demand. A hotel during a pandemic or a semiconductor fab during a demand collapse will show enormous variances that the flexible budget cannot meaningfully explain because the cost structure itself is being forced to adapt in ways the model does not capture. In those situations, scenario-based budgeting or zero-based budgeting gives you more useful signals than a standard flexible budget variance report. The method also requires actual cost data to be tracked consistently. If your AP department codes expenses to the wrong cost center, or if labor hours are estimated rather than recorded from time cards, the flexible budget is comparing garbage to garbage. You will get clean-looking variance reports that are completely wrong. I walked into a company where the flexible budget showed favorable labor variances for six consecutive quarters. The issue was that labor was being allocated based on headcount estimates submitted by department managers who had no incentive to report accurate numbers. The real variance was deeply unfavorable. Fixing the data collection process took four months. The variance analysis became useful only after that.
Building the Report Step by Step
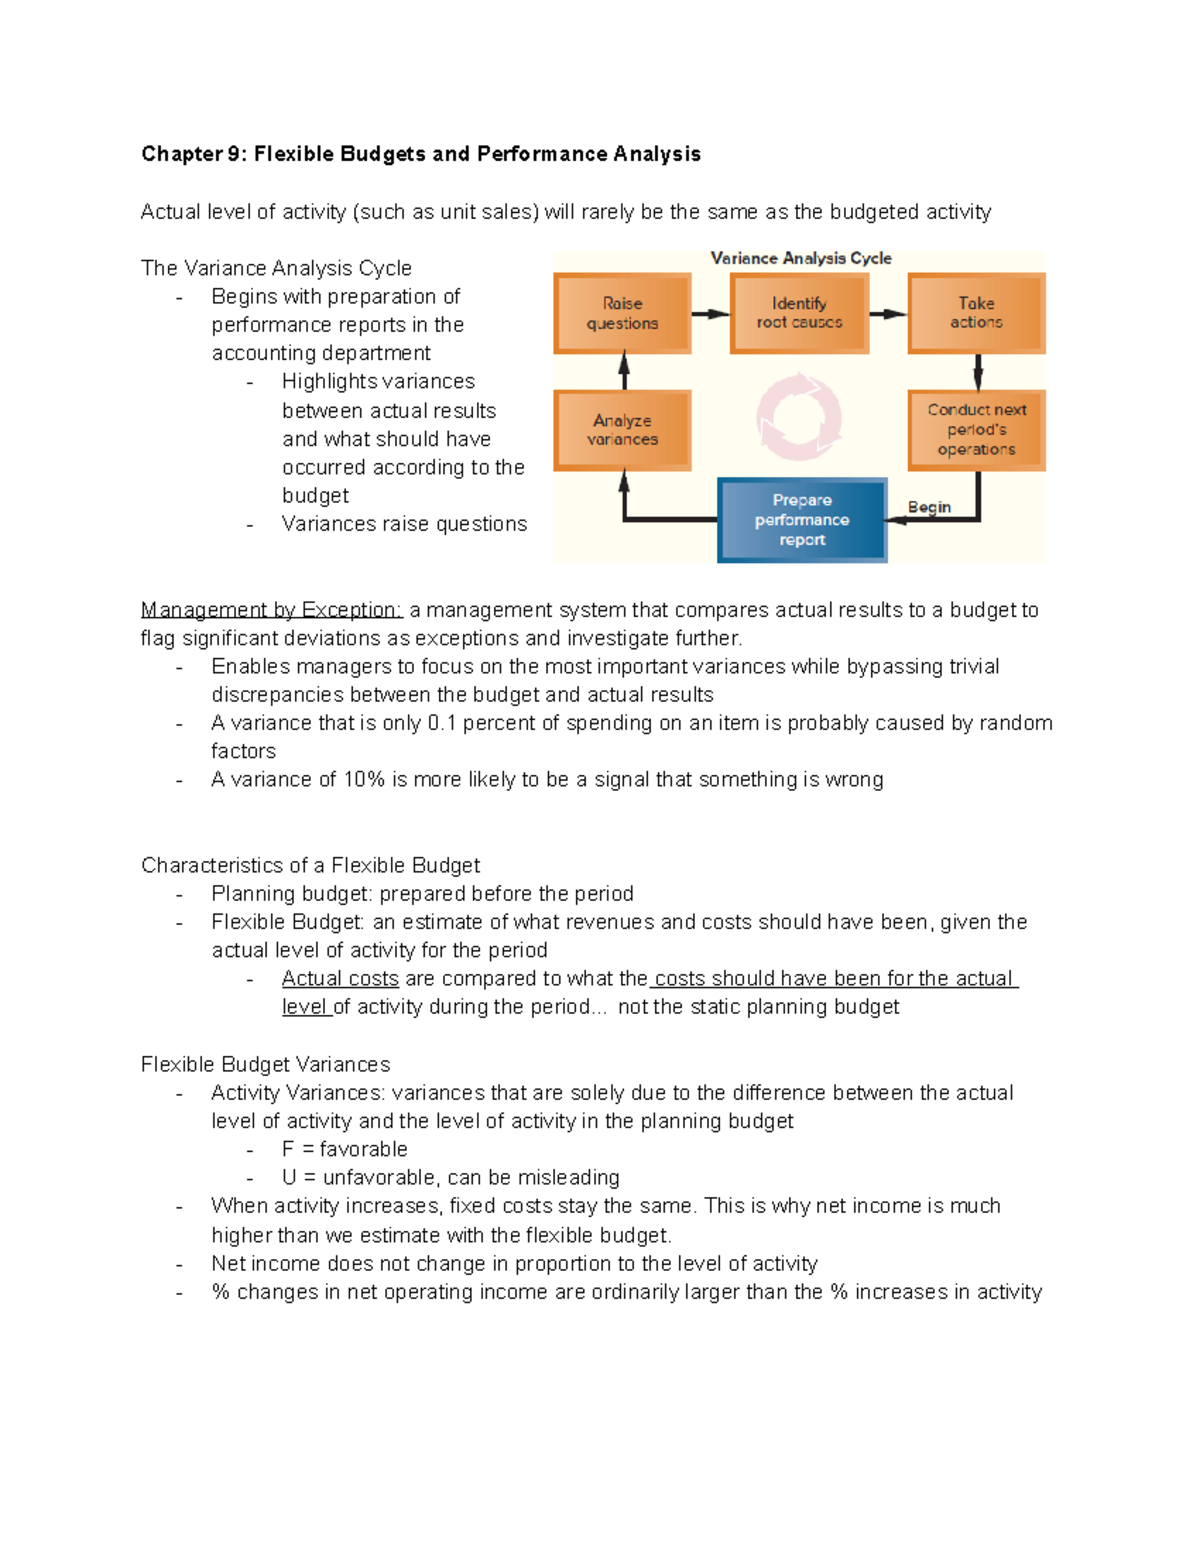
Open your general ledger. Pull the actual costs for the period by account and cost center. Pull the static budget figures for the same accounts. Identify the primary activity driver and pull the actual driver volume. Rebuild the budget at actual activity levels using the standard rates. Compare the rebuilt flexible budget to actual results line by line. Flag any variance that exceeds your materiality threshold. The threshold should be based on both absolute dollar amount and percentage relative to the budget. A five percent variance on a minor expense line is noise. A five percent variance on your largest cost category is worth investigating immediately. Document the root cause for each significant variance. Not just the number. What drove it. Was it a price increase, a volume change, an efficiency issue, or a structural change in the cost? The documentation is what makes the next period's budget cycle faster. Without it, you are starting from scratch every month. With it, you have a running log of what actually moves your costs. That log is worth more than the variance report itself.