What This Guide Actually Covers
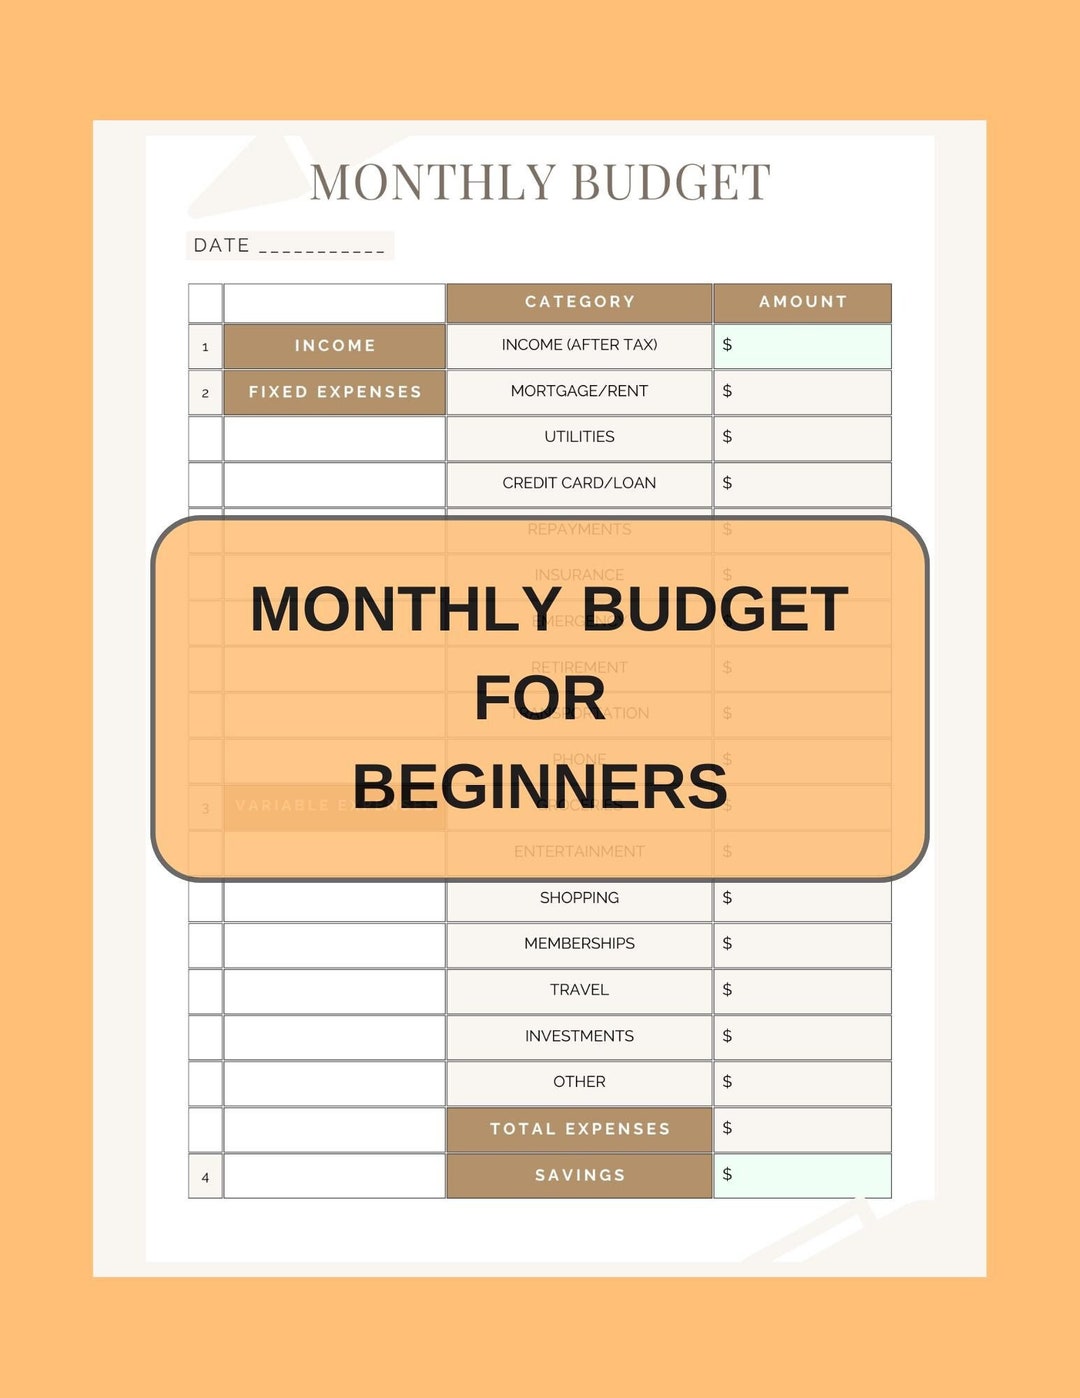
I used to hand out the beginner monthly finance guide to anyone who asked. Most people read through it once, bookmark it, and never come back because they got overwhelmed by the spreadsheets. The guide itself is solid, but it assumes you have time to set everything up properly. You don't. Here is what actually happens when someone picks it up cold. The current version is available as a free download from the personal finance resource hub at pfrhub.org. It is an 84-page PDF with worksheets, not a textbook. There is also a paid companion that adds a Google Sheets dashboard template, but you do not need it to follow along. The core material is in the free version. Start with the net worth tracking sheet. Not the budget. The net worth one. People skip it because it feels passive, but it is the only page in the entire guide that forces you to confront the gap between where you think you are and where you actually are. I learned this the hard way. Back in 2019, I had a client who swore he was saving money because his checking account never went negative. His net worth sheet showed he was two thousand dollars underwater when you factored in his credit card debt and his car loan. We stopped looking at budgets for a full month and just filled out that one page every Sunday. He caught his spending problem faster than any envelope system ever would have.
After that, move to the monthly cash flow tracker. It is deliberately simple. Income minus expenses equals freedom or lack thereof. The spreadsheet has no conditional formatting tricks or color coding designed to motivate you. That is intentional. The guide is built around the idea that boring tools are sustainable tools. Bright colors make you feel productive while doing nothing.
One Counter-Intuitive Thing Nobody Tells You
Most beginners try to budget every single dollar before they know their actual monthly expenses. This is backwards. You need three months of real spending data before any budget will stick. I put this in the guide because it saved me from recommending zero-based budgeting to dozens of people who were already drowning in it. Zero-based budgeting works beautifully in theory. In practice, if your actual grocery spending varies by two hundred dollars between weeks, telling yourself you can allocate exactly forty-three dollars to groceries is a recipe for abandoning the system by Wednesday. Track first. Allocate second. The guide covers this sequence in Chapter 3, but I have seen people skip ahead to the allocation templates anyway. The Google Sheets version has a rolling twelve-month average formula in the expense analysis tab. It looks impressive. It also breaks silently when you have a month with no recorded income because the cell references shift. I found this by accident during a financial literacy workshop last year. A participant had been self-employed that January and skipped the income entry. The whole average column turned green, implying her expenses were unusually low. They were not. The formula was just referencing the wrong cells. The fix is simple: add a helper column that counts non-empty income entries, and make the average formula check that first. I uploaded the corrected version to the download page and noted it in the errata section. If you use the original file and see your averages drop to zero overnight, that is probably why. It does not address subscription creep well. There is a section on recurring expenses, but it treats them as fixed costs. Most people do not realize they have seven different subscription services they can cancel without immediate consequence. The SaaS cancellation tax is real in a lot of cases, but the psychological cost of feeling financially trapped is worse. I recommend cross-referencing the guide with a service like Minimalist’s budgeting approach or just running a manual subscription audit every ninety days. The guide assumes you will catch these during your monthly review. You will not. You need a separate trigger for that.
Get the Full Details

Another limitation: the investment section is intentionally thin. It covers index funds and high-yield savings accounts at a surface level. If you are trying to build a portfolio beyond those two vehicles, you will outgrow this material within six months. That is by design. It is a starter kit, not a complete curriculum. Pair it with a free course from Khan Academy’s personal finance track or a Bogleheads wiki deep dive once you are past the basics. Don’t try to use this guide as your only resource.
How Long It Actually Takes to Work
If you spend thirty minutes a week following the guide, you will see meaningful results in about eight weeks. Thirty-five minutes if you struggle with spreadsheets. Two hours a week if you keep going back to reorganize categories instead of just filling them in. Most people fall into that last trap. They treat the system like a project to optimize instead of a habit to maintain. Keep it flat. Fill the sheets. Move on. The discipline matters more than the design.
Download and Next Steps
The current PDF is version 4.2 from March 2024. The companion Sheets template is version 2.1 from April 2024. Both are hosted at pfrhub.org/downloads. There is a Patreon for people who want the monthly live Q&A sessions, but the PDF alone is sufficient for nine out of ten readers. Read Chapter 1. Fill out your net worth sheet. Come back in thirty days with your expense data. Everything else in the guide builds on that foundation.