Why Your Fundamentals Are Wrong
Forex Trading Fundamental Analysis is less about economics and more about reading the market's interpretation of economics. I've watched enough traders get rekt by good data and bad prices to know the disconnect is real and consistent. Everyone knows interest rates matter. Rates are already priced into spot by the time the data drops. What moves currency pairs is the revision to future expectations, not the current quarter's number. When the Fed signals a pivot three months earlier than consensus, the dollar doesn't weaken gradually over a quarter. It gaps down on the morning of the speech and stays there. The yield curve is a more reliable leading indicator than almost any single data release. When the 2s10s Treasury curve inverts and then steepens, that sequence reliably precedes meaningful USD moves. But not all inversions produce the same outcome. The 2018-2019 inversion lasted eleven months with a modest 3 percent dollar move. The 2022-2023 inversion produced a twenty percent dollar rally before the curve corrected. Same signal, entirely different mechanics because the context was completely different.
I learned this the hard way in March 2022. The UK gilt crisis hit during a volatile CPI print. Every textbook said raise rates aggressively and the pound would strengthen. Sterling dropped two percent in fifteen minutes instead. The problem wasn't the data interpretation. It was that I was trading a liquidity event in a market that had already been unwinding position. Fundamentals don't override immediate funding pressures. The workaround I use now is simple: I check the order book depth and overnight funding rates before entering any trade around a major data release. If the bid-ask spread on GBP/USD is widening beyond three pips thirty seconds before the print, I sit out. The model doesn't matter when the market is searching for counterparty.
The Release Calendar Trap
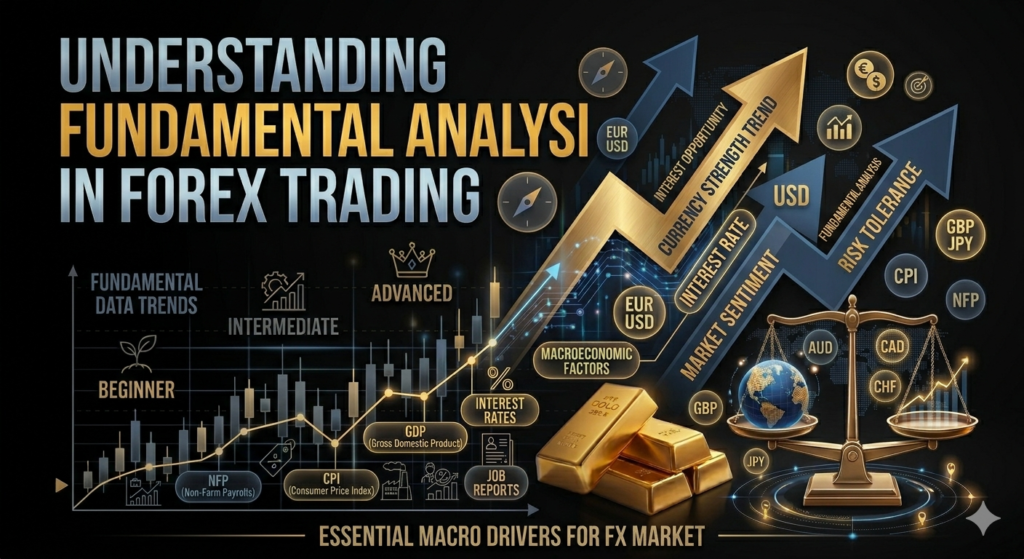
The consensus expectation printed in newspapers and trading platforms is already reflected in price. By the time retail traders read the number, institutional flows have already adjusted their exposure. The only alpha comes from what the data does to forward guidance narratives, not from the headline figure itself. Consider US nonfarm payrolls. The headline 200,000 number looks strong. But if average hourly earnings came in at 0.2 percent month-over-month instead of the expected 0.4 percent, and the prior two months were revised downward by 45,000 combined, the labor market story is weakening faster than the headline suggests. Most retail traders look at one number and trade one direction. Professionals look at the revision matrix and the wage component to estimate what the Fed will actually do. The difference between those two approaches is the difference between being on the right side of a move and getting caught in the reversal that follows. Another counter-intuitive point that beginners miss: strong economic data can weaken a currency if it removes the possibility of central bank accommodation. When Australia released a hot jobs report in 2023, AUD/USD dropped because traders realized the RBA wouldn't hold rates steady and the carry trade was no longer safe. The data was bullish for the economy but bearish for the currency pair. The relationship between growth and currency strength is conditional on monetary policy response, and that response depends on where the central bank's mandate equilibrium actually sits.
Get the Full Details

Central Bank Communication As a Signal
FOMC minutes, ECB press conferences, and BOJ policy statements contain directional information that raw data releases rarely provide. The language around "patient," "data-dependent," and "restrictive" shifts the entire curve. I track the Federal Reserve's dot plot distribution alongside the CME FedWatch implied probability. When the median dot moves two ticks in one meeting and the implied rate path shifts by only twenty-five basis points, there's a mismatch worth trading. The mismatch happened in September 2023 when the Fed raised its terminal rate estimate but kept forward guidance deliberately vague. Short-duration Treasuries sold off hard. The dollar didn't respond because the market read the vagueness as a signal that the next move could be a pause, not a hike. The disconnect between the hawkish forward guidance and the actual market pricing was a clear signal to go long the dollar, which I did. The pair moved about eighty pips over the following week.
Putting It Together In Practice
The workflow I use takes about twenty minutes per major release. First, I check what the consensus expectation is and how it differs from the prior estimate. Then I look at the prior month's revision to gauge the direction of momentum. After that, I check the broader macro backdrop: where rates are positioned relative to inflation, what the yield curve is doing, and whether there's a risk event overlapping the release. If everything aligns with a directional bias, I enter. If there's a conflict between the data and the macro backdrop, I usually don't trade until the dust settles. The biggest bottleneck with fundamental analysis is timing. Markets react in milliseconds to data releases. By the time you read a headline on your phone, the move has already happened. The workaround is setting conditional orders based on scenarios rather than reacting to outcomes. I predefine three outcomes for each major release—beat, miss, and in-line—and set orders for each scenario before the print. This removes emotion from the execution and keeps you from chasing price. There are scenarios where fundamental analysis simply doesn't work. Low-liquidity crosses like USD/TRY or USD/ZAR move on geopolitical headlines and capital controls, not on inflation data. Emerging market currencies are influenced by commodity prices, political risk, and sovereign debt dynamics that no standard macro model captures. If you're trading EM pairs, fundamentals are a secondary tool at best. Stick to the majors if you're relying on this approach.
Slippage during high-volatility releases also eats into edge. The spread on EUR/USD can widen from one pip to eight pips within seconds of a major US data release. If you're trading with a small account, that spread expansion can turn a winning setup into a breakeven or losing trade before the price even moves in your favor. Tight stops become impossible to manage during these windows, which is why most practitioners reduce position size by half or skip the trade entirely.

What To Monitor Before You Trade
A practical checklist for any fundamental analysis session: the yield curve slope across the relevant tenors, the current market-implied rate path versus the central bank's stated path, the revision trend in the prior three data points for the indicator you're watching, and the position of the currency pair relative to its recent trading range. If all four factors point the same direction, the trade has a clear thesis. If two point one way and two point the other, the setup is noisy and waiting is the better decision. The core insight is that fundamentals provide direction, not timing. Price action provides timing. Combining both reduces the chance of being directionally right but entry-timing wrong, which is the most common reason fundamental traders lose money despite having correct macro views.