How to Fill Out the Social Security Benefits Worksheet for 2022
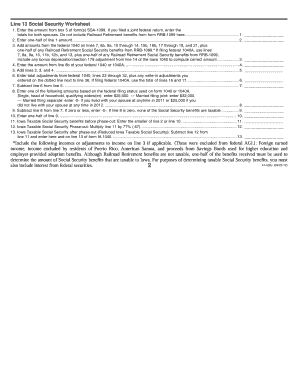
The Social Security worksheet on Form 1040 exists because not all of your Social Security benefits are taxable. The IRS only taxes a portion, and that portion depends on your total income combined with half of your Social Security benefits. That combined amount is called your "provisional income," and it determines whether 0%, 50%, or up to 85% of your benefits get included in taxable income. You only need to fill out this worksheet if you received Social Security benefits during the year and need to figure out how much of that is taxable. The worksheet is found in the Form 1040 instructions, not printed on the form itself. It's labeled as the "Social Security Benefits Worksheet" and it's separate from the main form. Here is how it actually works. Line 1 is the total amount from Box 5 of all your SSA-1099s or RRB-1099s. That is your gross Social Security benefit before any deductions. Line 2 is one-half of line 1. You subtract any tax-free Social Security benefits, like workers' compensation that converted to Social Security after your retirement age, from line 1 to get line 3. Then line 4 combines that adjusted benefit with your modified adjusted gross income, which includes nontaxable interest and certain foreign income. The result is your provisional income.
Once you have provisional income, the worksheet uses threshold numbers to determine the taxable portion. For single filers, head of household, qualifying widow or widower, or married filing separately who lived apart from their spouse all year, the thresholds are $25,000 and $34,000. For married filing jointly, they are $32,000 and $44,000. If your provisional income falls below the first threshold, none of your benefits are taxable. If it falls between the two thresholds, up to 50% may be taxable. Above the second threshold, up to 85% may be taxable. I spent years dealing with clients who had complex benefit situations. One edge case that comes to mind involves a client who received both Social Security retirement benefits and Railroad Retirement Board tier 1 benefits. Both came in on different forms, and both needed to be included in the worksheet. The tricky part was that some of the RRB benefits were taxable and some were not, depending on how the railroad system classifies them. The workaround was to pull each SSA-1099 and RRB-1099 separately, verify which boxes contained taxable versus nontaxable portions, and then net them on the worksheet. If you have multiple forms, do not just add them together blindly. Check each one. Another issue that catches people off guard involves spousal benefits. If one spouse received benefits based on the other's work record, both spouses get their own SSA-1099. When married filing jointly, you combine both forms. But if one spouse dies during the year, you still get an SSA-1099 for the deceased spouse, and it must be included in the calculation even though the survivor may have lost that income stream.
There is a common misconception that filing status alone determines whether your benefits are taxable. It does not. Your provisional income does. A single person making $22,000 a year from a pension and small investments will have zero taxable Social Security. A single person with the same pension plus $5,000 in capital gains might cross the $25,000 threshold and owe taxes on part of their benefits. The brackets are narrow, and small changes in income can push you into a higher taxable category. One thing most people miss is that the worksheet does not account for state taxes. Some states fully exempt Social Security benefits. Others partially exempt them. A few tax them the same way the federal government does. If you live in a state that taxes Social Security, you will need a separate state worksheet, and those vary by state. California, for example, conforms to the federal exemption thresholds but has its own calculation. Colorado has a different formula entirely. Do not assume your state follows the federal rules. If your provisional income is well above the second threshold, the worksheet will likely show that 85% of your benefits are taxable. In that range, an additional dollar of income does not increase your tax by a flat rate because of the way the 85% phase-in interacts with your marginal tax bracket. This is sometimes called the "benefits cliff effect," though the IRS does not use that term. It means that for some taxpayers, earning a little more can result in a proportionally larger increase in total tax liability than expected.
Get the Full Details
The worksheet itself is straightforward arithmetic. The difficulty comes from gathering the right numbers from the right forms and applying the correct thresholds for your filing status. If you use tax preparation software, it handles most of the heavy lifting. But you should still verify that the software pulled the correct figures from each SSA-1099. I have seen cases where the software defaulted to the wrong filing status threshold because the taxpayer's marital situation had changed mid-year. A divorce finalized in November could cause the software to apply joint thresholds instead of single thresholds, or vice versa, depending on how you answered the interview questions. There are scenarios where the worksheet approach simply breaks down. If you received lump-sum Social Security benefits covering multiple prior years, the standard worksheet will not handle that correctly. You need to file Form 8609 or use the lump-sum election method described in IRS Publication 915. If you are claiming Medicare premiums that were withheld from your benefits, those are already reflected in the Box 5 total and do not require a separate adjustment on the worksheet. If you repaid benefits in 2022 that you had reported as income in an earlier year, you can claim a credit or deduction on Schedule 1 rather than modifying the worksheet directly. For most taxpayers, the process takes about ten to fifteen minutes once you have all your forms organized. The biggest time sink is tracking down every SSA-1099 and RRB-1099 you received across all accounts. The IRS sends these out in January, and they go to every person listed on the account, not just the primary recipient. If you and a former spouse both receive statements for the same benefits, you both need to include them, and you both need to run the worksheet separately based on your own filing status and income.
Download the official Form 1040 instructions for tax year 2022 directly from IRS.gov. The worksheet is in the instructions under the section for lines 6a and 6b. There is no separate form number for the worksheet itself. It is simply a calculation tool embedded in the instructions document. If you need the current version for a different year, look for the corresponding tax year in the instructions title. The worksheet structure has remained largely consistent, but the income thresholds adjust annually for inflation. If your situation is extremely simple, with only one SSA-1099 and no other income adjustments, the worksheet is essentially a three-step calculation. But the moment you add multiple sources of income, prior-year repayments, disability conversions, or railroad benefits, the complexity increases fast. That is when it pays to be meticulous about the source documents rather than relying on memory or rough estimates.