What Form 1120 S Actually Requires
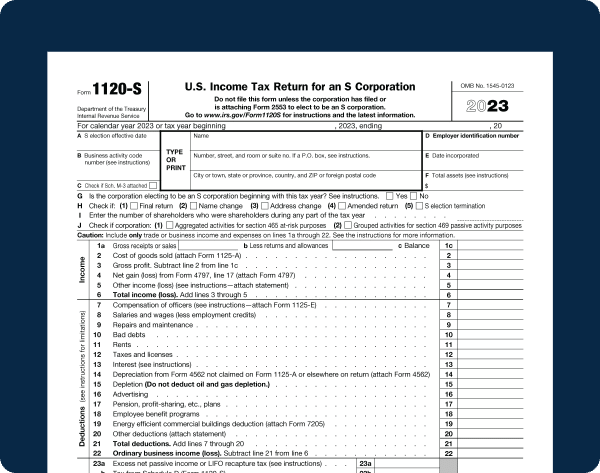
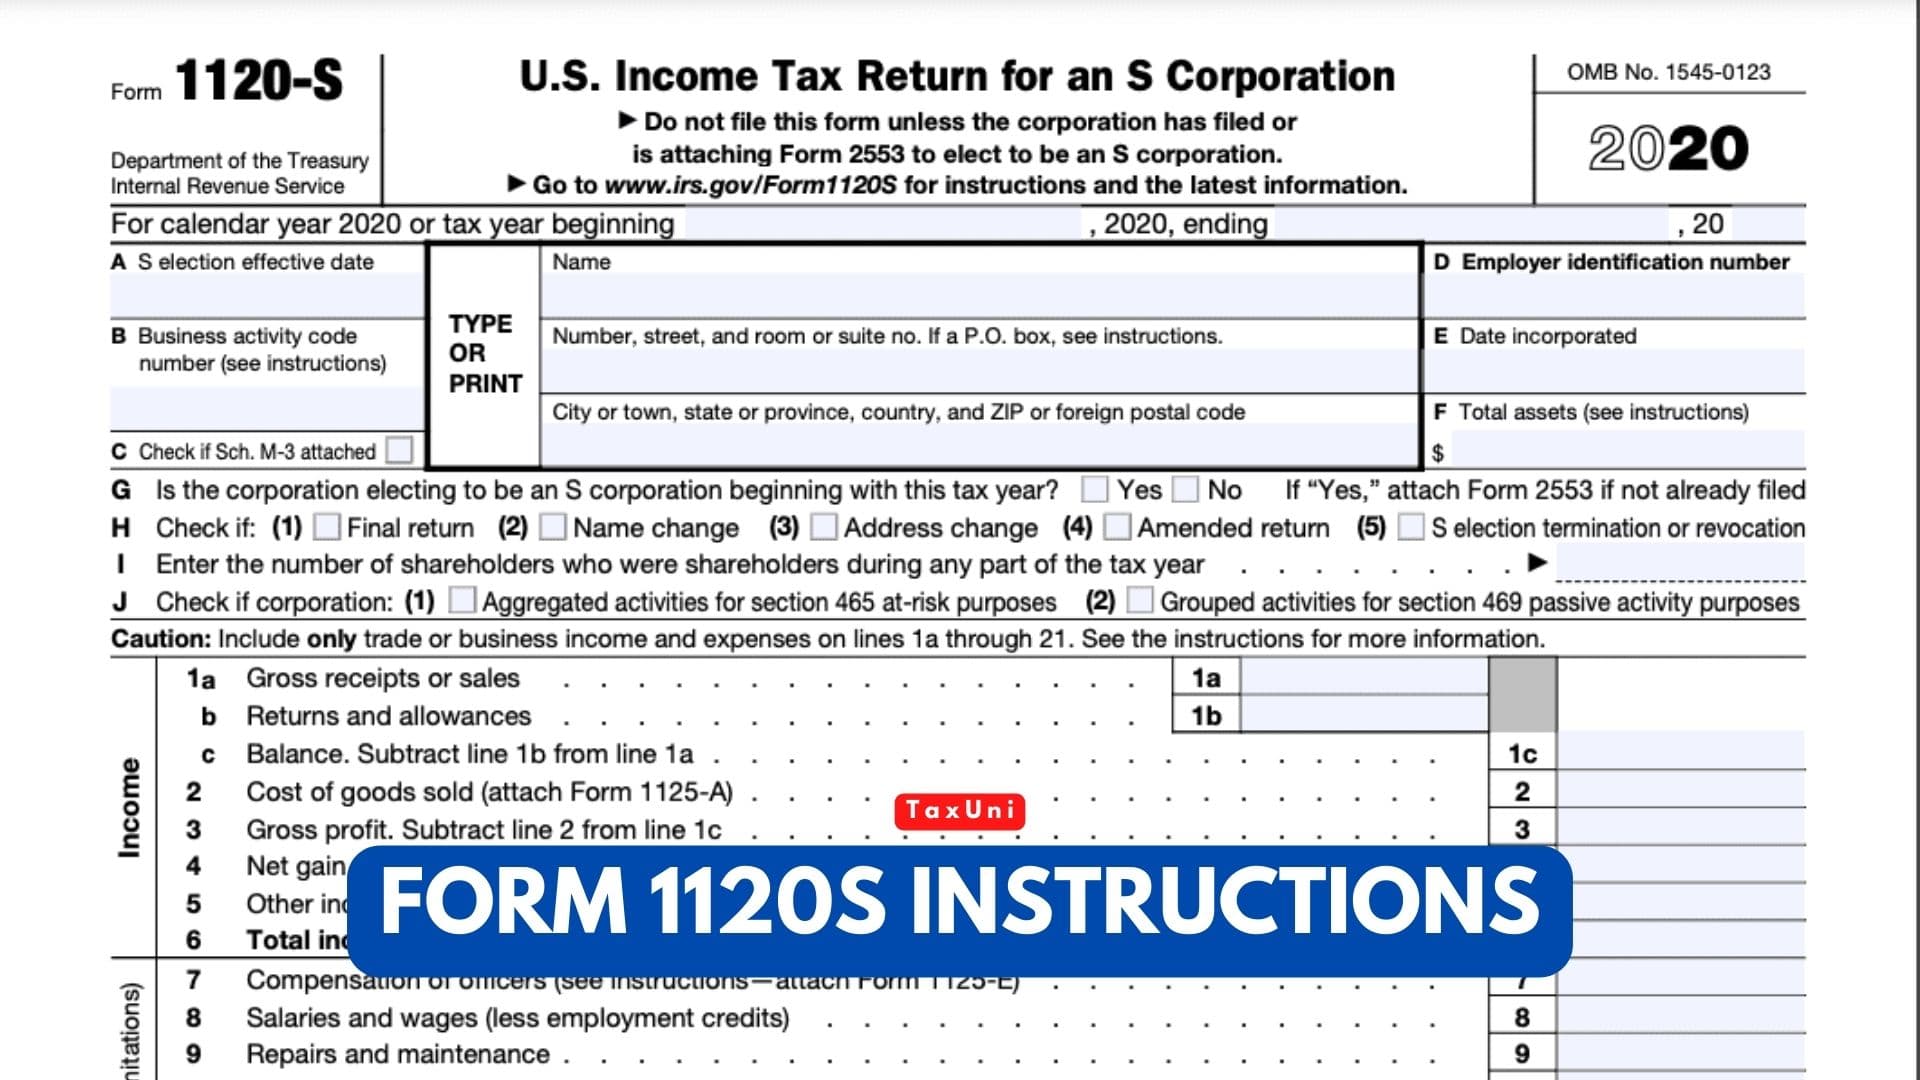
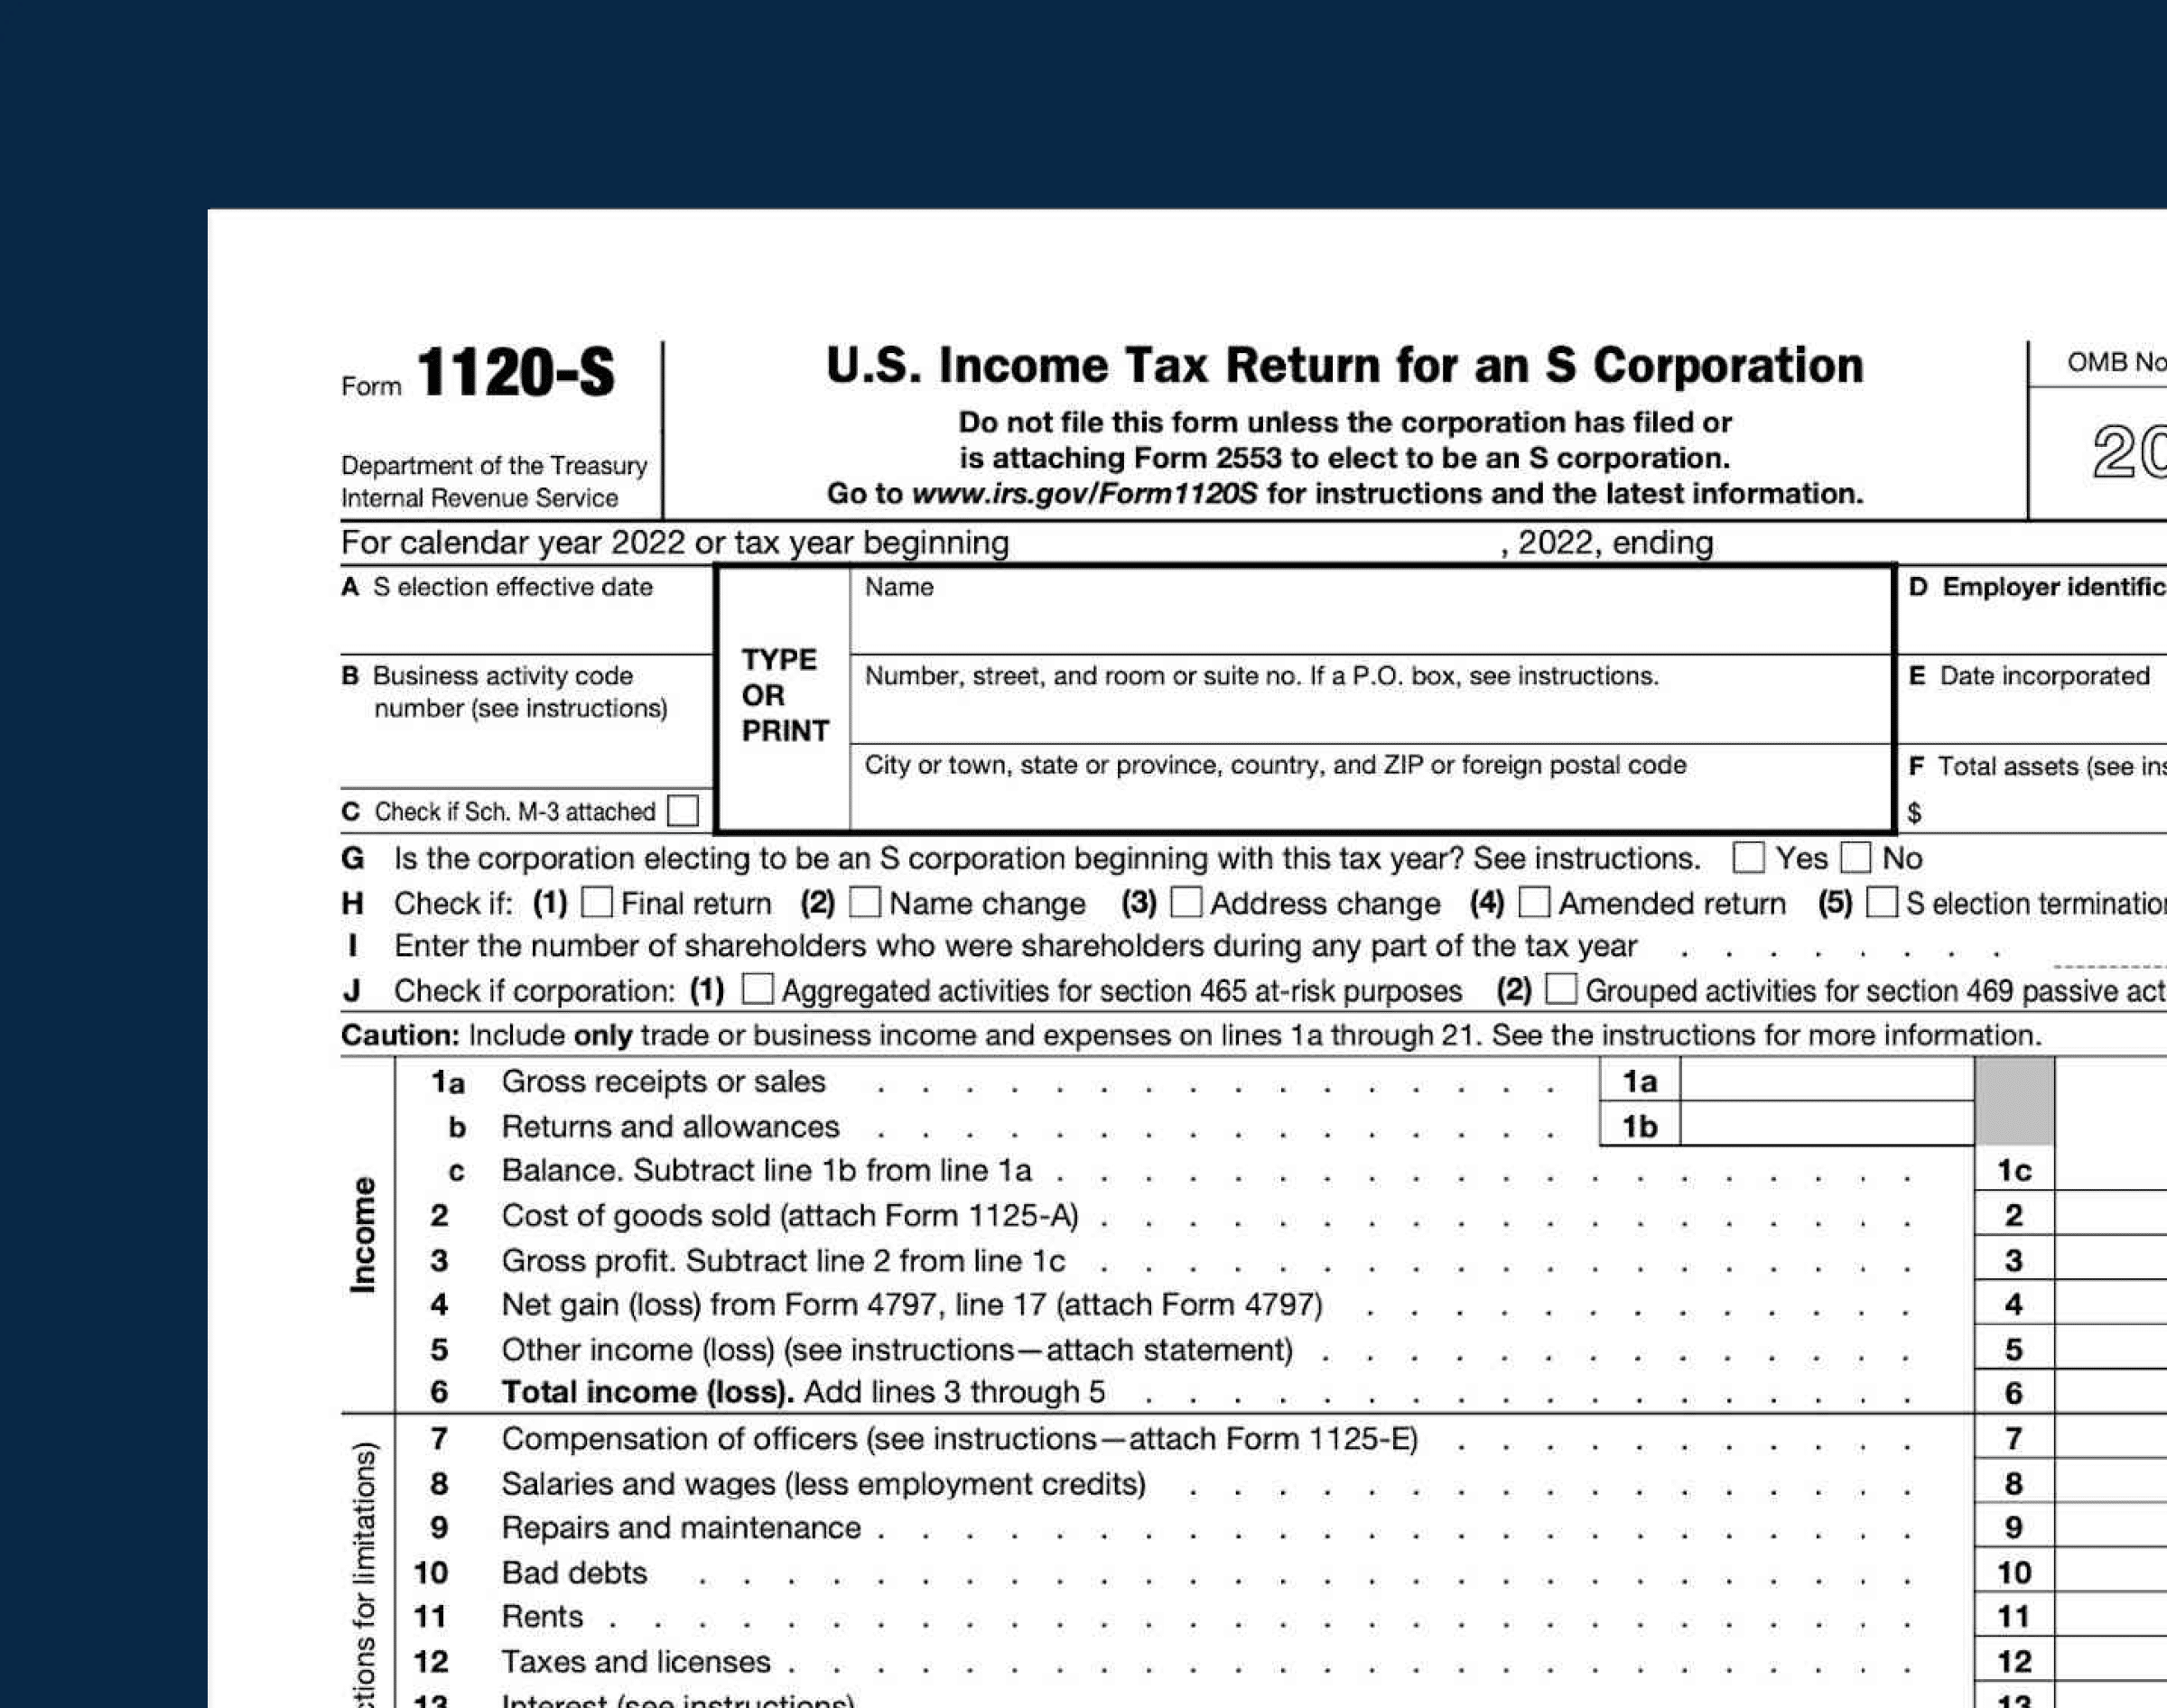
Most people opening the IRS packet for the first time assume it is straightforward. It is not. The form itself—just a few pages—looks manageable, but the supporting schedules inside it will chew you up if you have not done this before. I spent about six hours last year untangling an S corp return that went sideways because someone had mixed K-1 allocations between capital distributions and ordinary income without realizing the distinction mattered on Schedule K-1 line 15 versus line 16. The form does not warn you about that. You learn it the hard way. You can download the official version directly from irs.gov. Search for "Form 1120-S" and grab the PDF that includes both the form and the accompanying instruction booklet. Always verify the year matches your tax filing period. The 2024 instructions apply to returns due in April 2025. The 2025 instructions apply to returns due in April 2026. Mixing them up will not cause an immediate audit, but it will cause confusion on things like updated depreciation tables and the latest shareholder basis rules. Don't bother with third-party sites. They are not worth the risk. The instruction booklet runs roughly 80 to 120 pages depending on the year. It covers every line, every schedule, and a handful of special situations. Most practitioners skip straight to the pages relevant to their case. That works fine until something unexpected comes up, which it always does.
Reading the Instructions the Right Way
The Form 1120 S Instructions are organized by line number, but the narrative under each line assumes you already understand Subchapter S. If you don't, you will spend more time flipping back and forth than you should. I usually start with Part I, Section A, which deals with income and gains, then move through the deduction sections, then handle the K-1 schedules last. The reason is simple: the numbers on the K-1 lines depend on everything before them. If you reconcile the main body first, the K-1 work flows easier. One thing the instructions never emphasize enough is the difference between book income and tax income on an S corp return. S corps are pass-through entities, which means the corporation itself generally does not pay federal income tax. But the book value of assets, the method of depreciation, and the treatment of certain deductions can still diverge from the tax treatment. This creates mismatches that show up on Schedule B, line 10, and sometimes on Schedule K-1 line 12. I once had a client whose real estate held appreciated property from a C corp conversion. The book basis was one number, the tax basis was another, and the instructions barely flagged this scenario until I cross-referenced Section J of the instruction booklet. Took me an afternoon to sort it out, but it would have been a nightmare at audit time.
Schedules That Trip People Up
Schedule K-1 is where most errors land. Each shareholder gets one, and the totals on Page 1 have to reconcile with the main Form 1120 S. The reconciliation is usually automatic if you enter data correctly, but it breaks easily when you have multiple classes of stock or when a shareholder's basis runs negative. Negative basis is not the end of the world, but it requires careful tracking across years. The instructions explain the basis limitation rules in Part III, but they bury the practical example three sections down. I keep a sticky note on my desk that says "check basis before finalizing K-1" because I have done this return enough times to know when things are off. Schedule L, the balance sheet, is another area where shortcuts cause problems. Assets and liabilities must match the prior year unless there is a documented change. If you carry forward numbers without reviewing them, depreciation schedules can drift. Accumulated other comprehensive income often gets overlooked entirely. The instructions cover Schedule L briefly and assume you know what you are doing. You may not.
Get the Full Details
Common Pitfalls Nobody Talks About
The biggest issue I see is the treatment of S election timing. If the S election was made mid-year, the short period rules kick in and the income allocation between the pre-election and post-election periods matters. It is not something the Form 1120 S Instructions walk through step by step. You find it in the special rules section near the end, and it is easy to miss. A missed election timing adjustment can result in the wrong amount of income flowing to shareholders or being treated as C corp income incorrectly. Either way, it creates a paper trail that looks suspicious later. Another pitfall involves the accumulated earnings and profits issue. If the S corp ever was a C corp, it carries over earnings and profits indefinitely. Distributions from E&P are taxable to shareholders as dividends even though the entity is an S corp. The instructions mention this on Schedule K-1, Line 13, but they do not provide a calculator or a clear example for most situations. I had to build my own spreadsheet to track E&P buckets across multiple years after a client converted from C to S status. Without that tool, the K-1 numbers were basically guesses.
When the Instructions Are Not Enough
There are scenarios the Form 1120 S Instructions simply cannot cover in detail. Passive activity loss rules interact with S corp income in ways that change year to year based on legislation. The at-risk rules have their own separate code sections that reference back but do not reproduce the full logic. State-level conformity adds another layer—the IRS form tells you nothing about how California or New York or Texas treats S corp income differently. You need state-specific guides or software that handles multi-state allocations. Software can help here. TurboTax Business, Drake, and CCH Axcess all have built-in checks that catch many of the errors I mentioned above. They are not perfect, and they sometimes default to assumptions you need to override. But they reduce the time from a full day to somewhere between two and four hours for a standard single-shareholder S corp return. A more complex multi-shareholder return with basis complications still requires manual work.
Bottom Line
Read the instructions, but don't trust them to be exhaustive. Cross-reference with the actual code sections when something feels vague. Verify basis calculations independently before finalizing K-1s. Keep a running E&P schedule if your client has any C corp history. And double-check that you are using the current year's Form 1120 S Instructions, not last year's. The IRS revises certain lines annually and the changes are not always obvious at a glance.