Navigating Form 8812 Line 5: What It Actually Is and How to Fill It Out
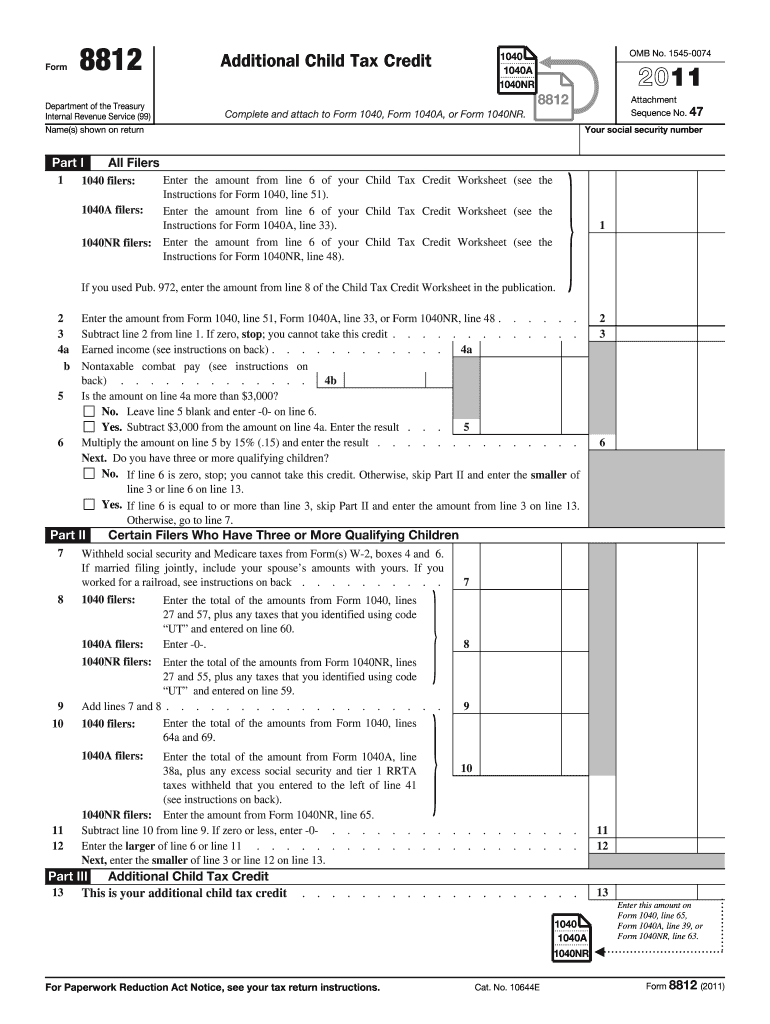
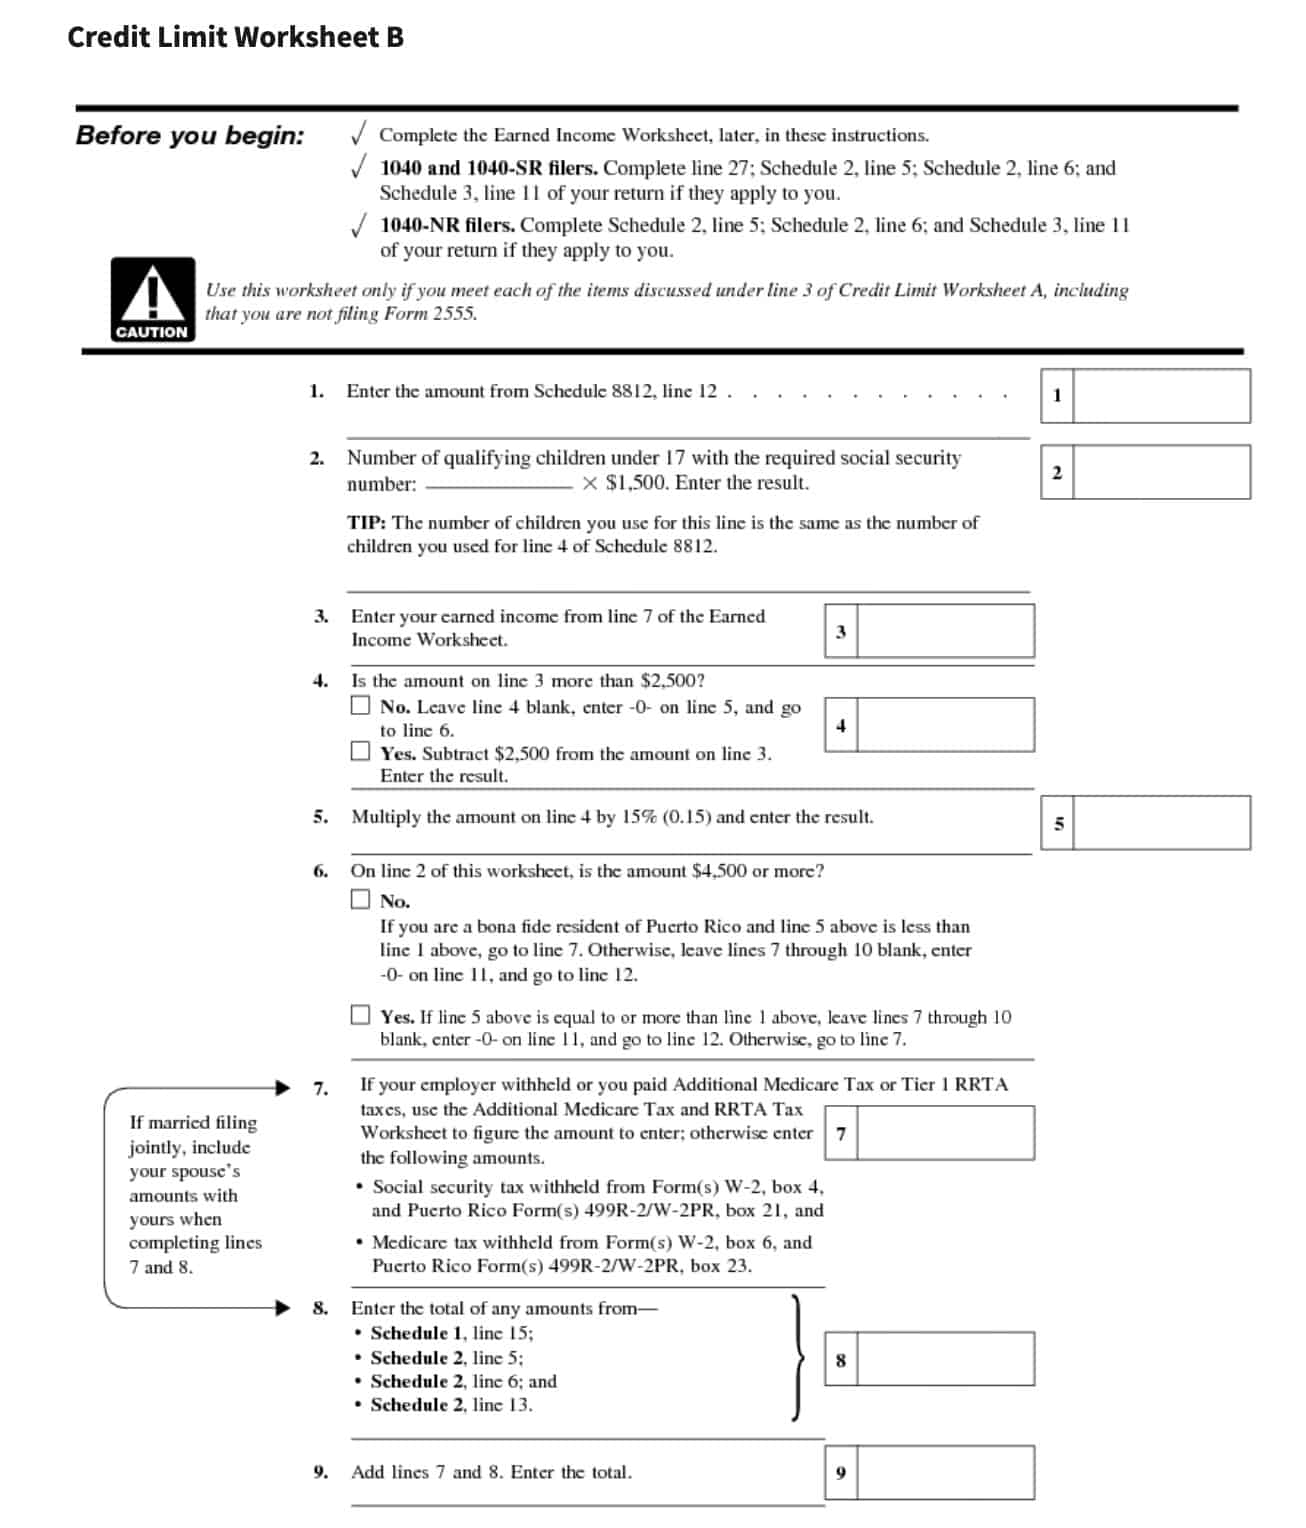
Form 8812 deals with three separate credits—Earned Income Credit, Additional Child Tax Credit, and the recovery rebate amounts—but the line 5 worksheet is the piece most people mess up because it sits right at the intersection of two different calculation paths. If you are claiming the earned income credit on Schedule EIC and then moving it over to Form 8812, line 5 is where that transfer happens. The worksheet itself is not complicated, but the way the instructions are written makes it easy to plug in the wrong number and quietly undercut your refund. The worksheet lives inside the Instructions for Form 8812. You start by pulling your earned income credit from Schedule EIC, line 8, or from the EIC table if you are using that instead. That number goes onto line 5 of the worksheet. From there, you compare it against your adjusted gross income using the same threshold chart you already used on Schedule EIC. If your AGI is below the limit for your filing status and number of qualifying children, the amount on line 5 stays as-is. If your AGI exceeds the threshold, you follow the worksheet's subtraction steps to reduce the credit dollar by dollar until it hits zero. I spent about forty minutes on this last year because I had a client with two qualifying children and a side gig that pushed their AGI just two hundred dollars over the EIC phaseout threshold. The difference between staying in the credit and losing it entirely was roughly four hundred dollars in additional child tax credit benefits. The workaround was straightforward—rechecking whether some of the self-employment expenses should have been deducted earlier to bring AGI below the line. Once I adjusted Schedule 1, the EIC came back and the worksheet worked as intended. Took about fifteen minutes after I found the issue.
The thing nobody warns you about is that line 5 can end up zero even when you clearly qualify for the EIC. This happens when you have income from sources that boost AGI but do not count as earned income—interest, dividends, or a small IRA distribution. The worksheet still uses AGI for the phaseout comparison, so those unearned amounts can silently wipe out your credit. I have seen this at least half a dozen times in a single tax season. The fix is usually to re-examine whether any of that income is actually reportable, or whether a deduction like the educator expense or HSA contribution can bring AGI back under the cutoff. If your situation is complicated enough that the worksheet produces a result that feels wrong, the alternative path is to use the EIC Assistant on IRS.gov. It asks the same questions in plain language and will tell you exactly where the phaseout hits. It does not replace Form 8812, but it saves you from spending an hour wrestling with a worksheet that may be pointing you at the wrong number in the first place. You can download the current Form 8812 and its instructions directly from irs.gov by searching the form number. The worksheet is included in the instructions, not on the form itself. Print it, fill it by hand, and then transfer the final figure to the appropriate line on Form 8812. Do not skip comparing line 5 against the AGI chart at the end—if you do, you risk claiming a credit you are not actually entitled to and triggering a delay when the return gets flagged later.