What Form N-CEN Actually Is
Form N-CEN is the new electronic annual and semi-annual report filing that the SEC replaced the paper-style N-1A and N-2 with. It came into effect in 2022, and every registered investment company and business development company now files their shareholder reports and certain other documents through this format. The form asks for structured data in specific fields rather than free-form narrative. That distinction matters more than most people realize when they're actually filling it out. The main purpose is to make fund data more searchable and comparable. The old system buried information across twelve pages of narrative plus exhibits. N-CEN pushes everything into data fields that EDGAR can parse. It sounds better on paper. In practice, the transition has been messy for advisors and compliance teams who used to work from templates.
Form N Cen Instructions breakdown
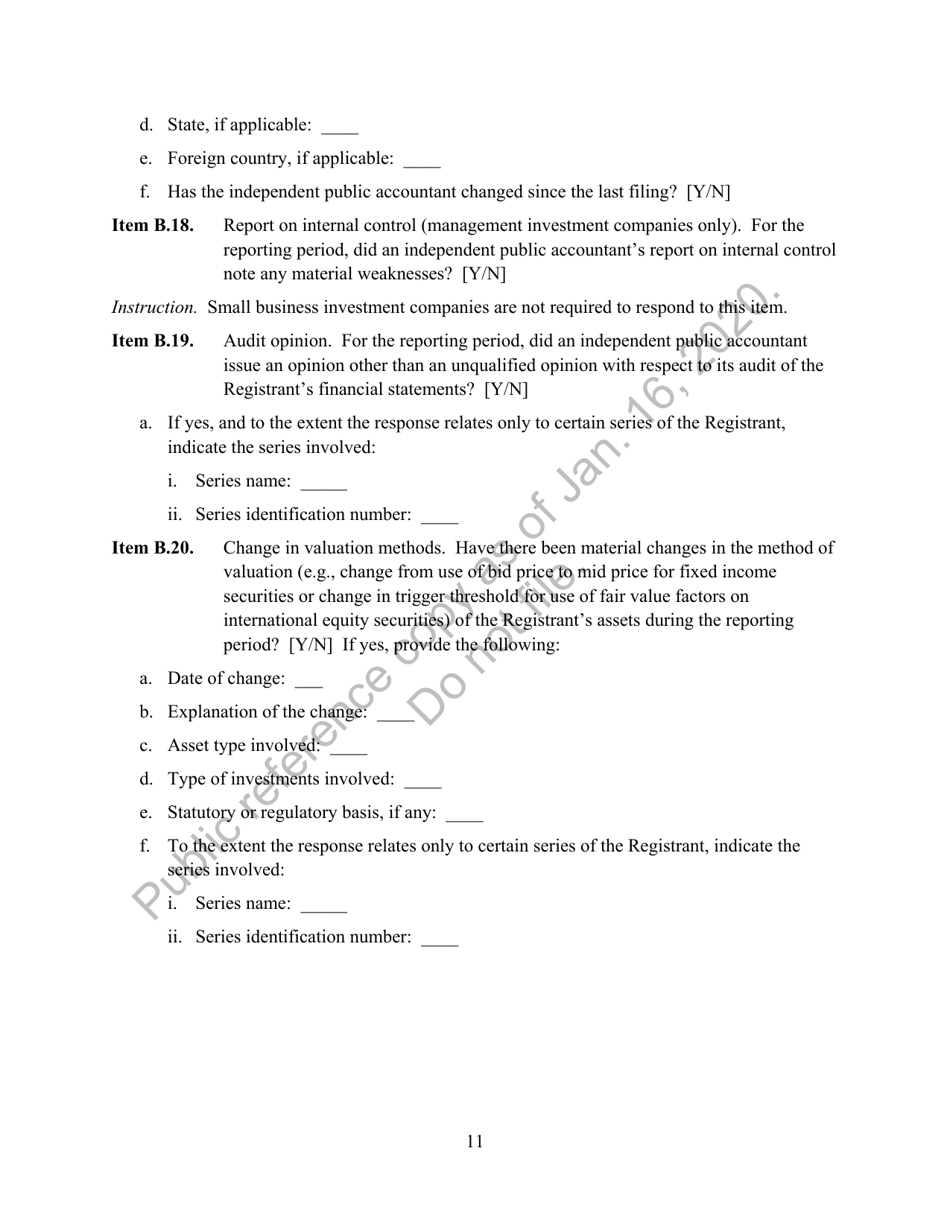
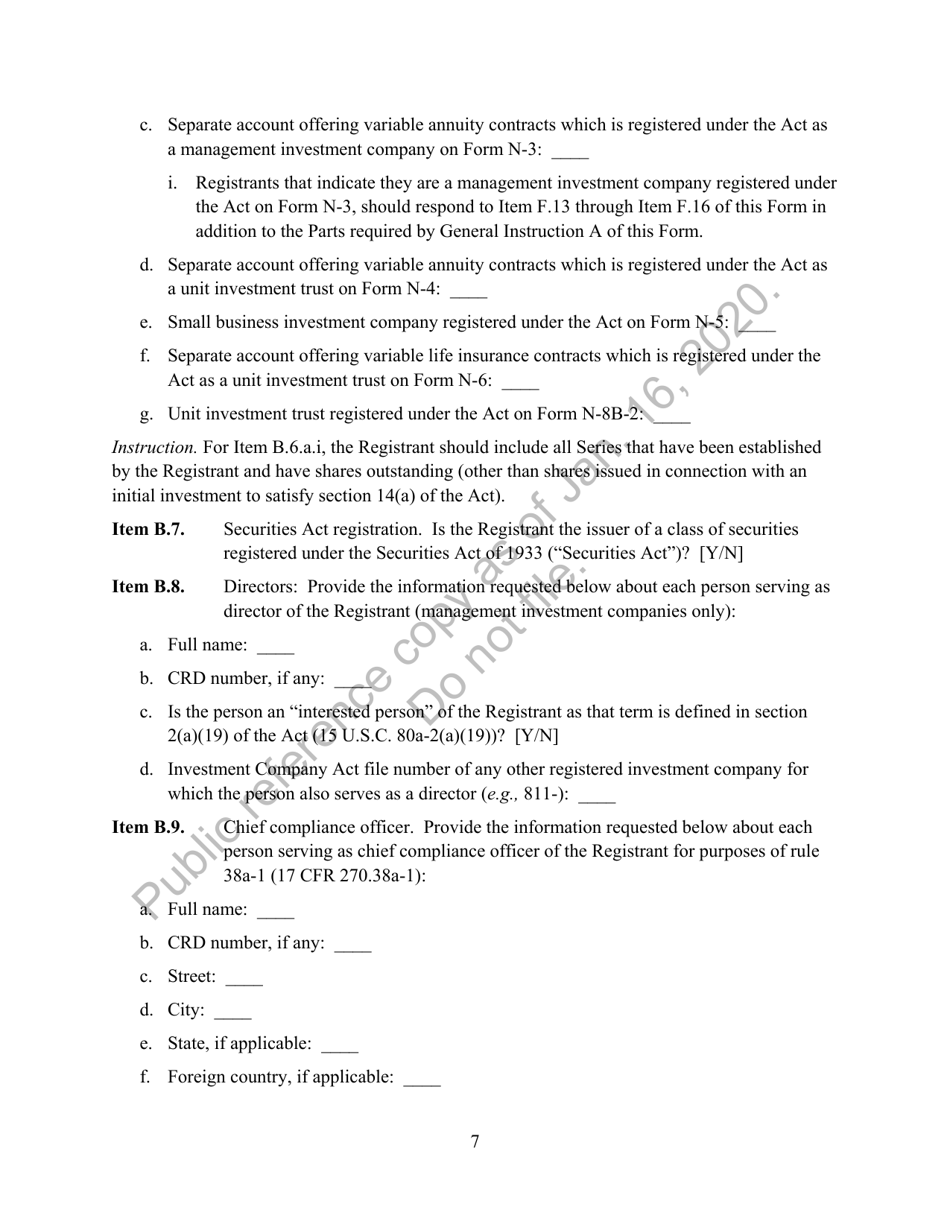
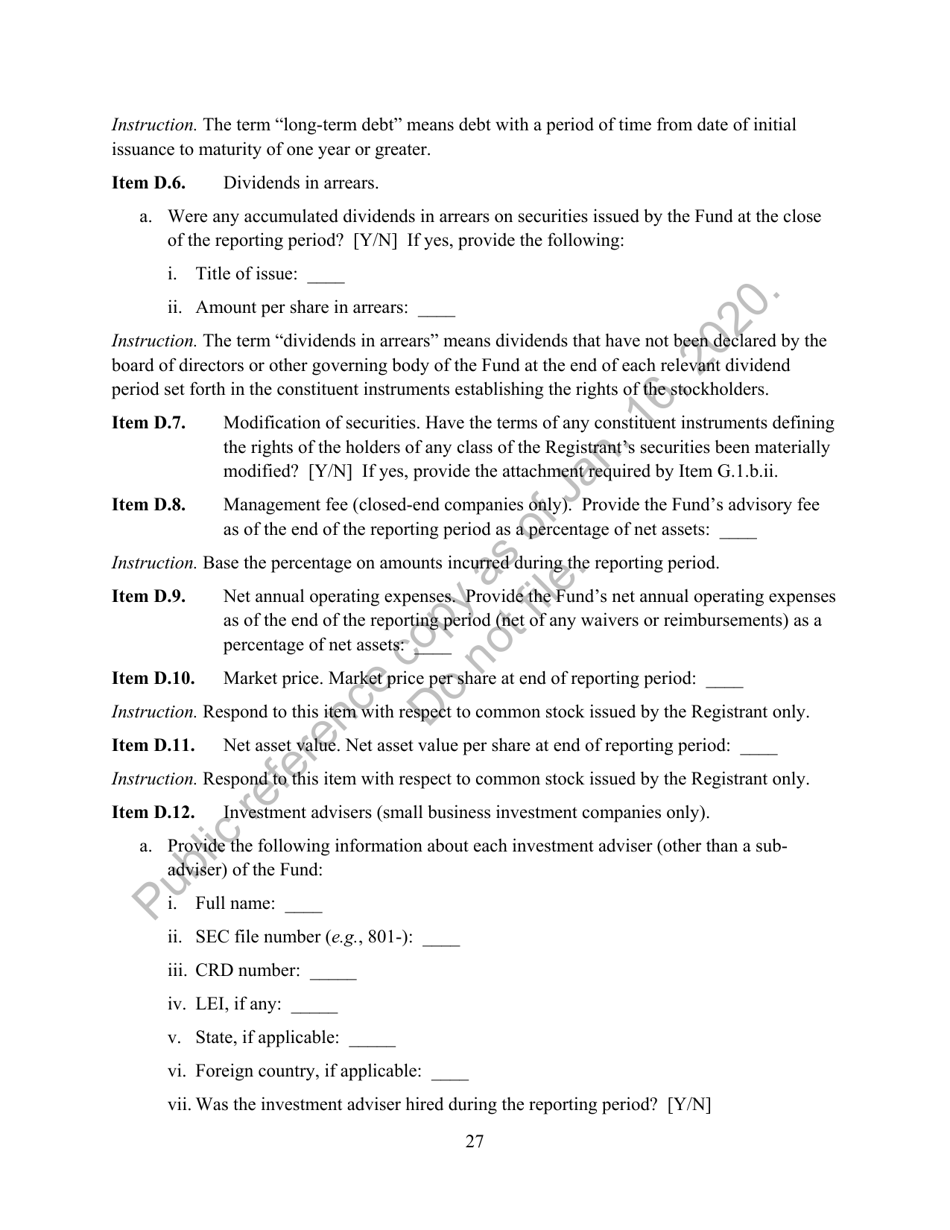
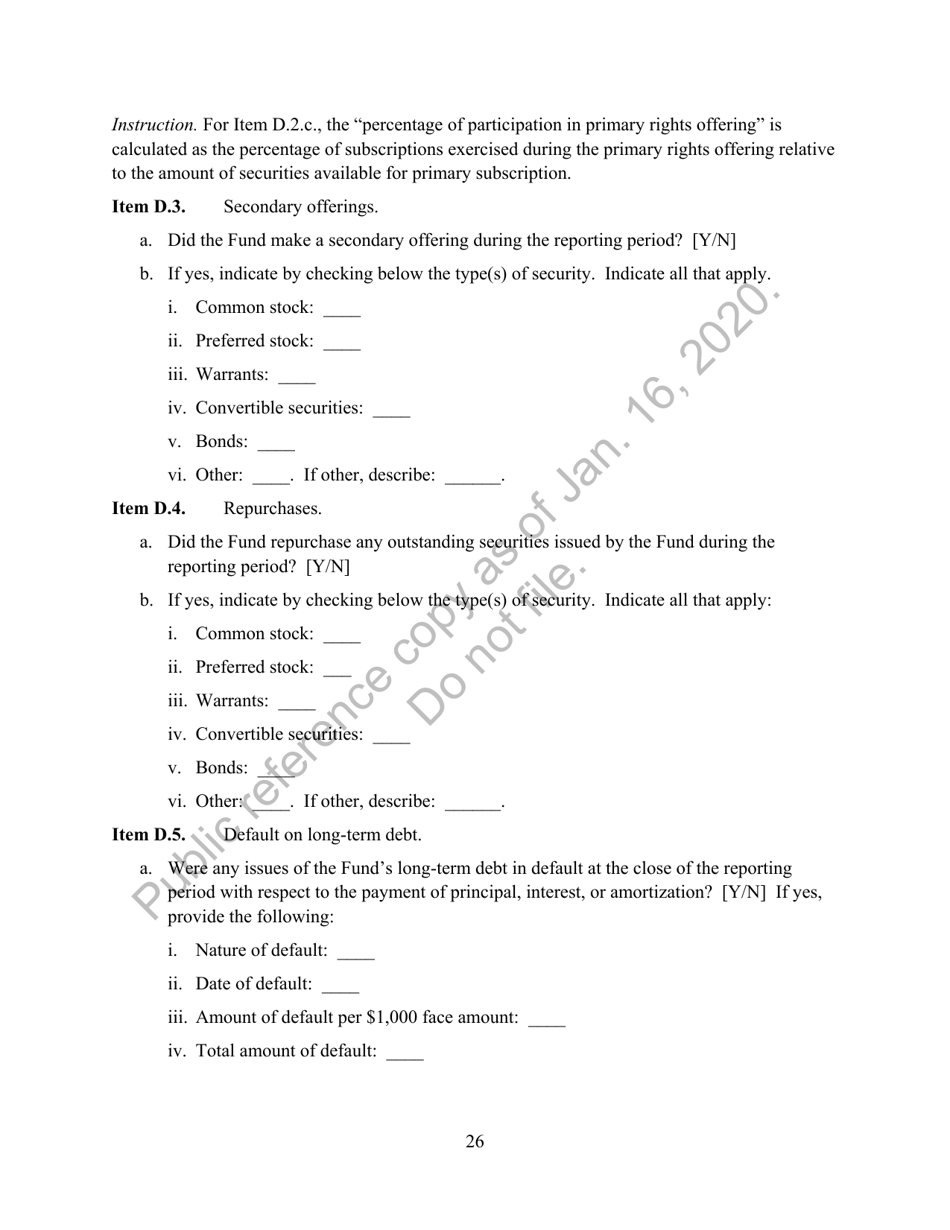
Getting the N-CEN instructions right starts with understanding the schedule structure. The form is divided into multiple schedules, each covering a different area: Schedule A handles organization details, Schedule B covers portfolio holdings, Schedule C covers investments in certain affiliated companies, and Schedule J is where most people run into trouble with valuation and financial data. The instructions tell you which funds must file which schedules. Not every fund files every schedule. I worked through my first N-CEN filing during the transition period, and the biggest shock was the data validation. The SEC's system checks fields in real time. If Schedule J shows total assets of $540 million but your Schedule B portfolio doesn't reconcile to that number, the filing gets rejected immediately. No warnings. No grace period. We spent three weeks chasing a reconciliation mismatch between our accounting system and the portfolio data that the fund administrator had pulled. The fix was to map the GL accounts to the N-CEN line items rather than simply copy-pasting totals. Copying numbers never works with N-CEN because the validation logic expects consistency across schedules, not just accurate individual lines. Another thing the official instructions don't emphasize enough: the difference between filing N-CEN as a standalone document versus pairing it with your prospectus and statement of additional information. N-CEN itself is a data filing. It does not replace the narrative documents you still have to provide. Funds generally file N-CEN alongside their annual and semi-annual reports that go to shareholders. The two things exist in parallel. Missing this distinction caused delays for a fund I advised on because they thought filing N-CEN satisfied the entire reporting obligation. It does not. It satisfies only the structured data portion.
The filing window is tied to your fiscal year end. Most funds file within 60 days of fiscal year end for annual reports and 60 days after the end of the second fiscal quarter for semi-annual reports. The earlier guidance still references 60 days, but N-CEN changed the mechanics significantly. Electronic-only submission is required, and the form uses XML-based tagging. You cannot upload a PDF as N-CEN. The system expects validated XML files generated through the SEC's existing submission tools or through a qualified third-party platform. I recommend using a platform that has N-CEN-specific validation before you attempt a direct EDGAR filing. Direct filing without pre-validation typically costs another filing cycle and at least two weeks of turnaround. Schedule J deserves special attention because it carries the financial responsibility section. This is where you disclose performance data, fees, expenses, and net income. The performance calculations follow a specific SEC methodology that differs slightly from how some fund administrators compute returns internally. I found that my administrator's return figures were off by roughly 5 basis points compared to the N-CEN required methodology, and the variance compounded over multi-year disclosure periods. The workaround was to rebuild the performance schedules in a spreadsheet that followed the exact SEC formula before entering them into the form. It took about four hours but saved us from filing incorrect data that would have required an amendment later. There are also practical limits to what N-CEN can handle. Funds with complex structures like separate accounts, sub-advised funds, or umbrella funds with many series find the schedule mapping particularly burdensome. The instructions assume a standard single-series fund structure in many places, and there is no clean workflow for funds where each series files its own data within a parent framework. You have to build a custom process for each scenario, and there is no one-size-fits-all template from the SEC.
Get the Full Details
If your fund uses a non-standard fiscal year, such as a 52-53 week fiscal year, the timing calculations become even less straightforward. The instructions reference fiscal year end dates, but week-based fiscal years create ambiguity about what qualifies as the official end. The safest approach is to confirm with the SEC's Division of Investment Management or your legal counsel before filing. Do not assume your standard practice from the old N-1A period applies here without verification. You can access the current Form N-CEN and instructions through the SEC website. The form and related materials are available on the SEC's official filing pages, and the instructions include detailed schedule-by-schedule guidance along with examples. The most recent version reflects amendments from the SEC's 2022 final rule and subsequent staff guidance. Check the filing date each time you prepare to submit, because the requirements have shifted since the initial rollout and a few further updates have been proposed. The bottom line is that N-CEN improves data quality over time but adds real friction in the short term, especially for funds transitioning from legacy formats. Budget extra time for reconciliation between your accounting system and the required fields. Double-check performance calculations independently. And do not treat N-CEN as a substitute for your narrative disclosure documents. It is a separate filing layer that runs alongside them.