So You Need To Pick A Business Structure
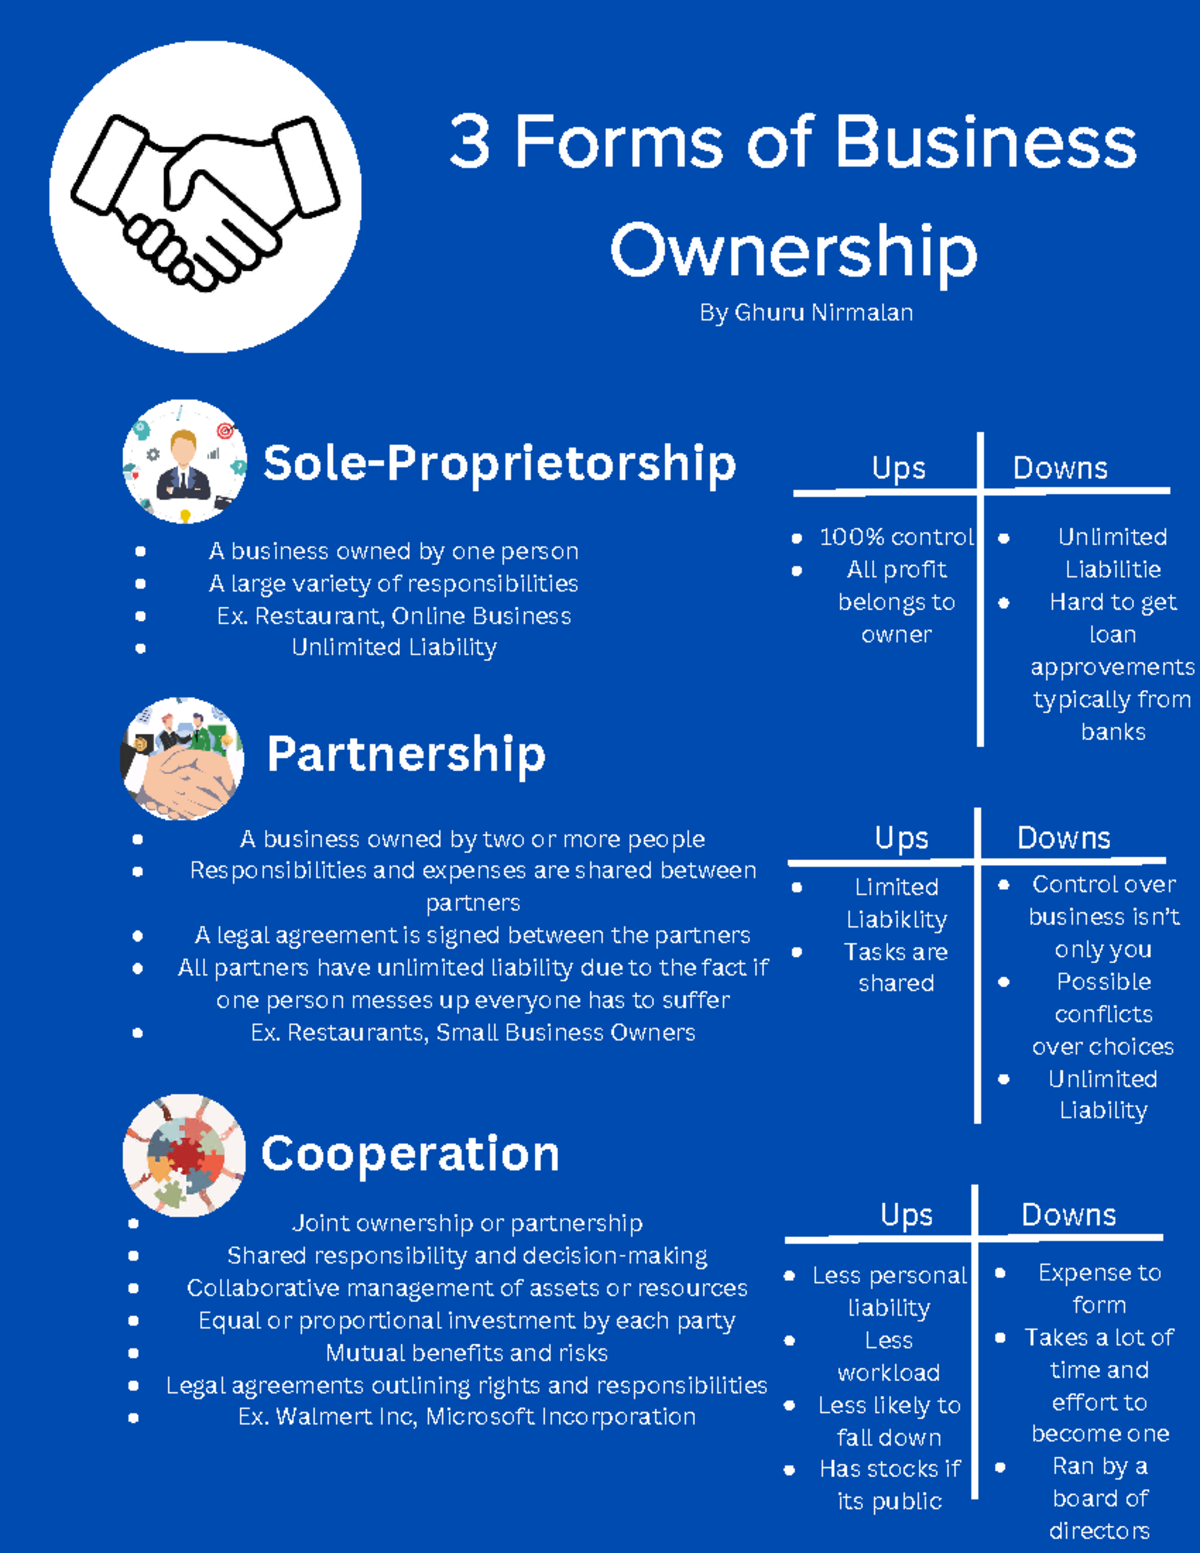
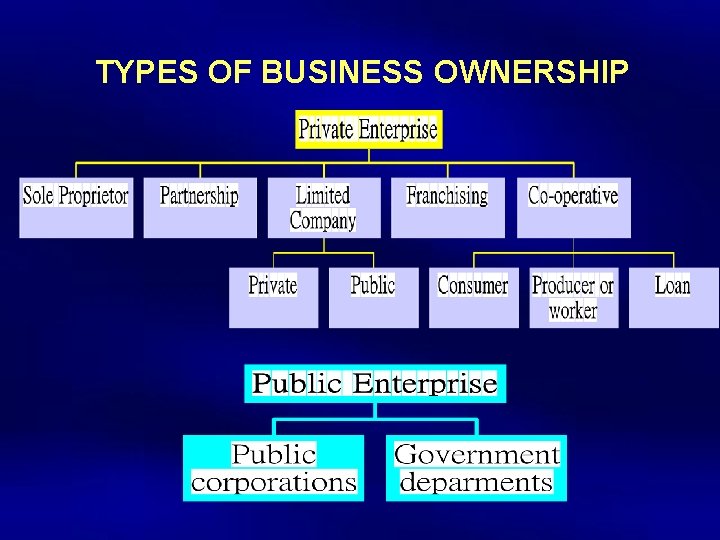
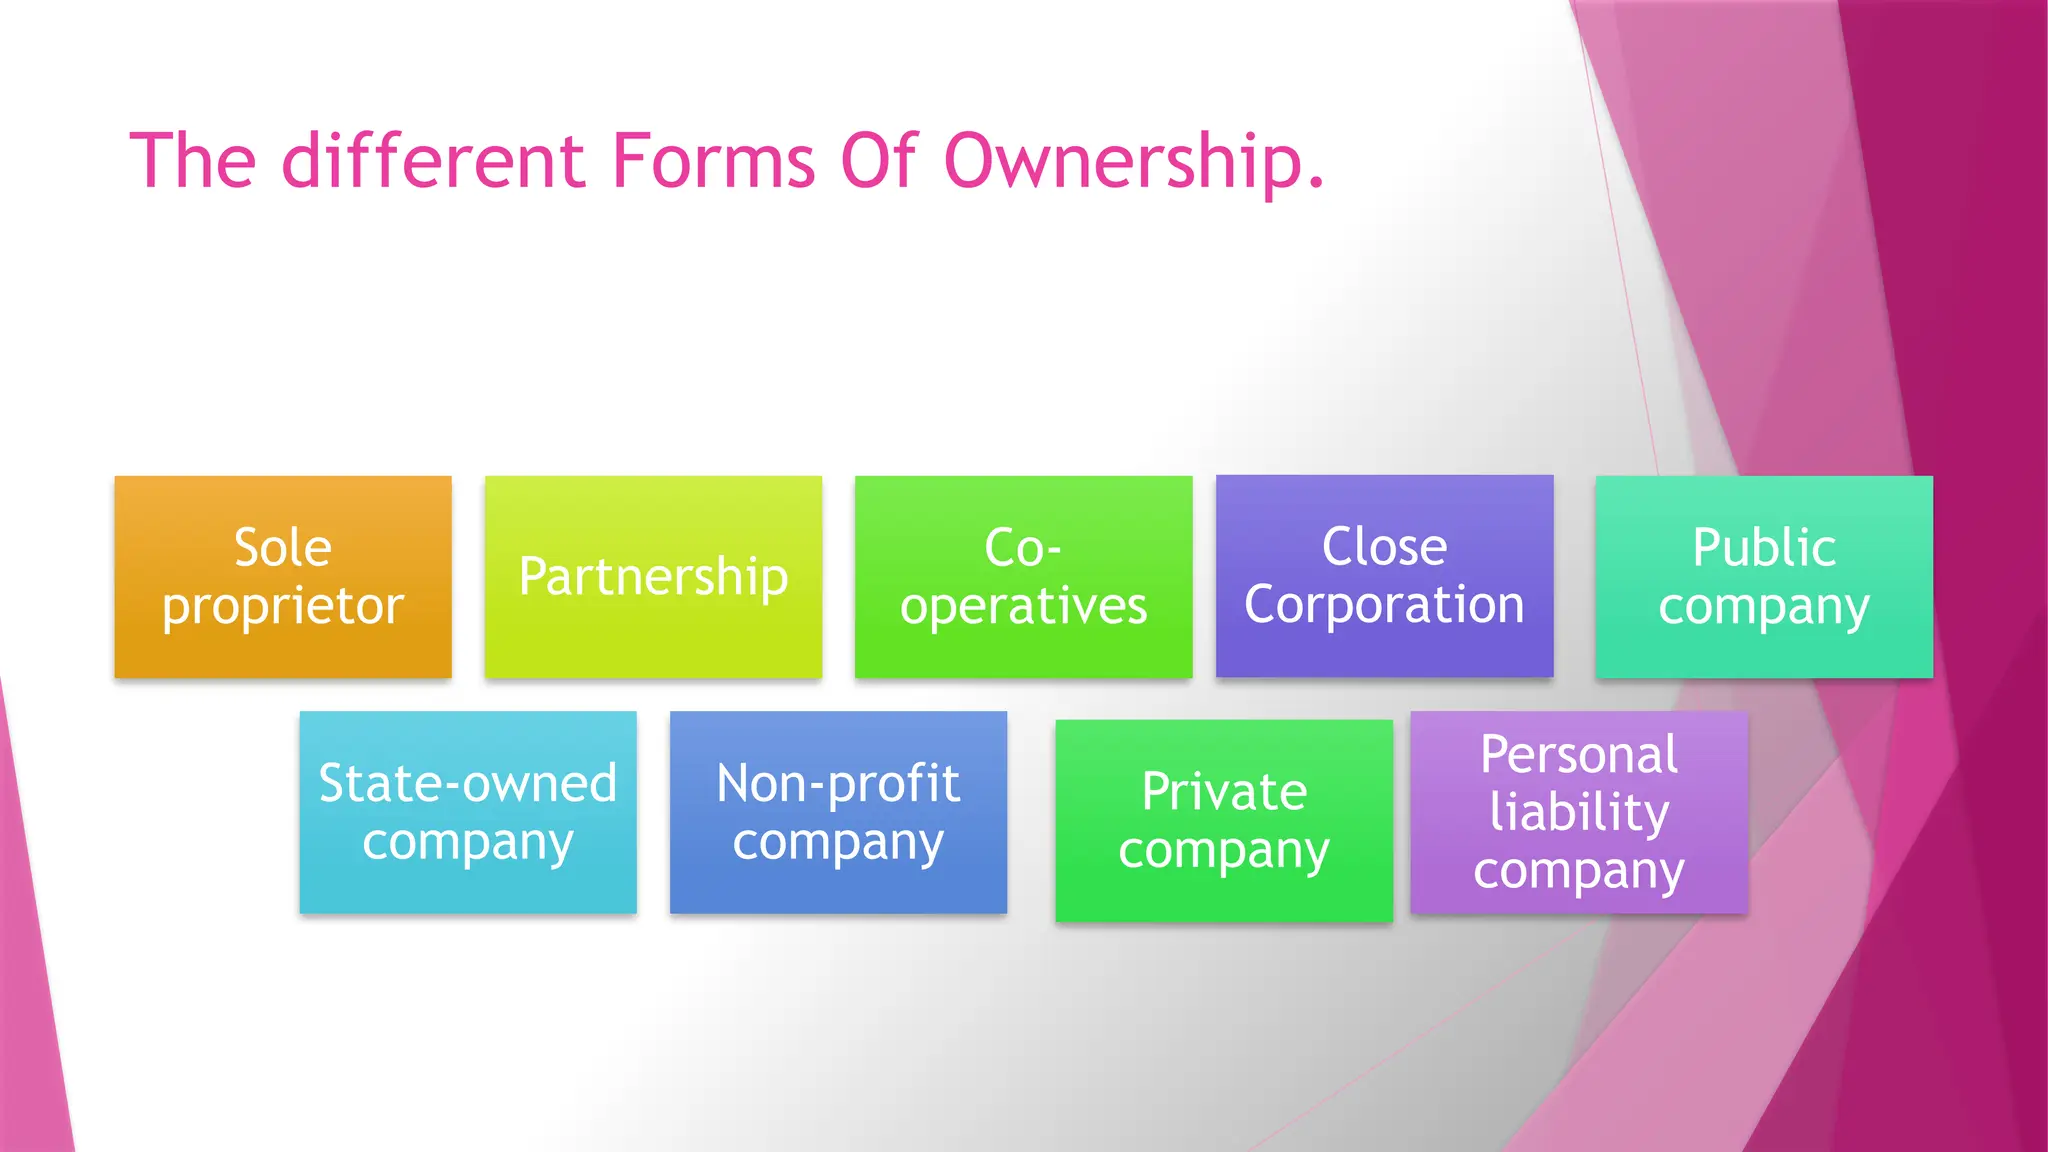
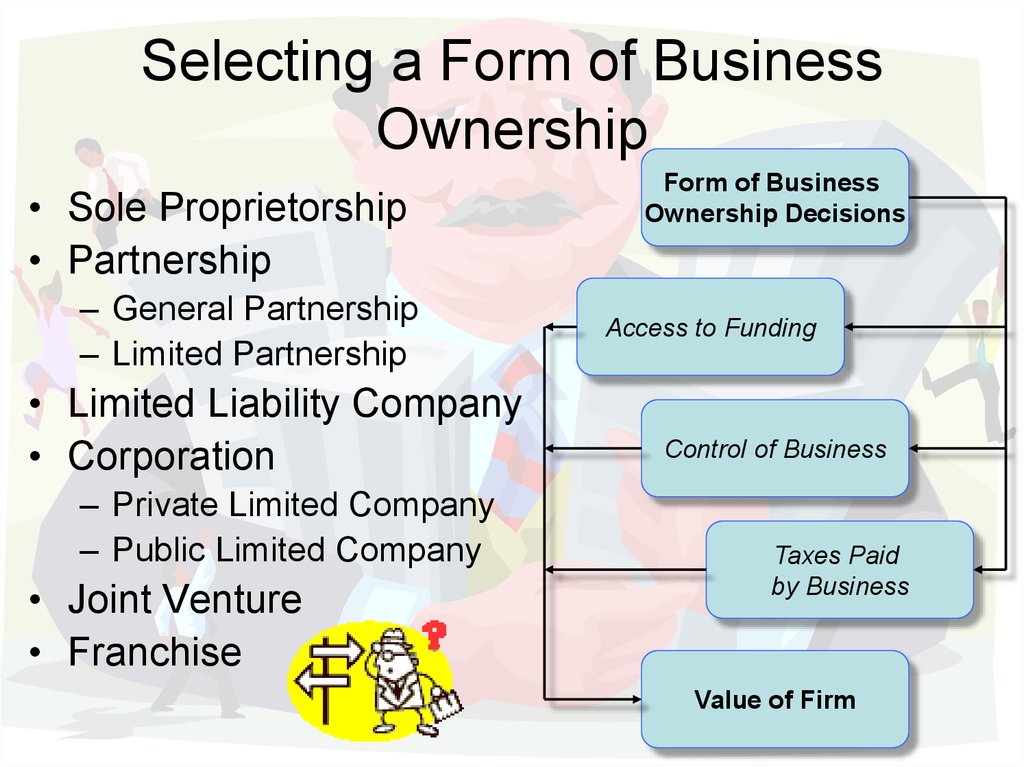
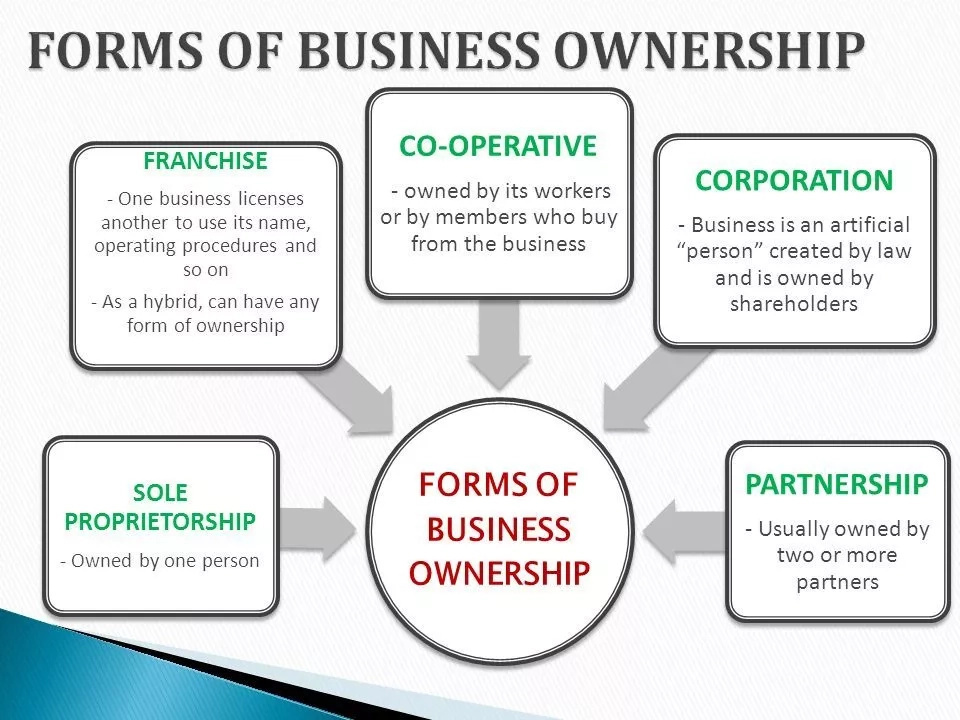
I spent about three years running a sole proprietorship before I bothered converting to an LLC, and honestly it was the most painful year of paperwork and anxiety of my entire career. The Forms Of Business Ownership available to you aren't really a question of which one sounds best on paper, they're about who takes the hit when something goes wrong, how much tax friction you're comfortable with, and whether you actually need other people's money to survive the first two years. The standard list you'll find everywhere has five main categories: sole proprietorship, partnership, limited liability company, S corporation, and C corporation. There are also variations like LLPs and PLCs but those are niche enough that most people won't need them unless they're in a regulated profession like law or accounting.
Structuring Your Entity For Reality, Not For A Flowchart
Here's what nobody tells you upfront: the choice isn't mostly about taxes. It's about liability exposure and exit flexibility. You can always change your entity later but it's ugly and expensive. I watched a friend flip from sole prop to LLC to S corp over a four year period because each change required new bank accounts, refiled licenses, new contracts, and an accountant who charged by the hour. The whole thing cost him roughly $8,000 in legal and filing fees and took about six weeks of suspended operations. Start with your actual risk profile. If you're consulting or doing remote work with minimal physical interaction, a sole proprietorship might be fine for year one. If you're handing off equipment, storing inventory, or dealing with clients on site, an LLC from the start is usually cheaper than the alternative. One client slipped on a loose cable at my old office, called their lawyer, and I spent eight months in civil court even though the claim was eventually dismissed. Being an LLC would have blocked that entire mess. That's not fearmongering, that's just what liability protection actually does.
Breaking Down The Five Main Structures
Sole proprietorship is the default when you start working without filing anything. You're the business. There's no separation between your personal assets and your business obligations. It costs nothing to establish, you file Schedule C with your personal tax return, and you pay self-employment tax on everything. The downside is unlimited personal liability. Your house, your car, your savings account, they're all on the table if someone sues you. Simple to set up, brutal to unwind if things go sideways. General partnership is basically two or more sole proprietors sharing everything, including the liability. Each partner is personally responsible for the entire debt of the business, not just their share. I was once brought into a partnership discussion where one person wanted equal ownership but no involvement in day to day operations. That's not a partnership, that's a silent investor, and you'd want a different structure for that arrangement. Partner agreements need to cover profit split, decision making authority, buyout terms, and what happens when someone wants out. Without a written agreement you're governed by your state's default partnership statutes, which are designed for disputes, not for running a business. LLC is where most small businesses end up and for good reason. You get liability protection without the corporate compliance overhead. Members own percentage shares, operating agreements define how decisions are made, and profits pass through to personal tax returns so there's no double taxation. The catch is that some states charge annual franchise taxes or minimum fees on LLCs regardless of revenue. California's $800 annual franchise tax is the most well known example, but states like Arizona and Texas have their own version of that friction.
Get the Full Details
S corporation is a tax election, not a business structure itself. You form an LLC or corporation first, then file Form 2553 with the IRS to be taxed as an S corp. The main benefit is self-employment tax savings. As an LLC taxed as a sole prop or partnership, you pay self-employment tax on all net earnings. As an S corp, you pay yourself a reasonable salary subject to payroll taxes and take additional profits as distributions not subject to self-employment tax. I ran a business pulling about $90,000 in net income and switching to S corp status saved me roughly $4,200 a year in self-employment tax after accounting for the extra payroll setup costs. The tradeoff is administrative complexity: you need a separate payroll process, quarterly filings, and an accountant who actually understands the reasonable compensation doctrine. Mess that up and the IRS can revoke your S corp election retroactively, which is worse than never having elected it in the first place. C corporation is the default corporate structure and it exists mostly for companies planning to raise venture capital or go public. It's a separate taxpayer, so income gets taxed at the corporate level and dividends get taxed again at the individual level. That double taxation is why most small businesses avoid it. But C corps have real advantages: they can offer multiple classes of stock, they attract institutional investors, and retirement plan contributions are treated more favorably. If you're a solo founder bootstrapping a service business, a C corp is almost certainly the wrong choice. If you're building something that needs $2 million in seed funding within eighteen months, it might be the only realistic option.
The Hidden Complexity In Choosing Among Forms Of Business Ownership
There's a scenario that comes up surprisingly often and it's easy to miss. When you're a single member LLC electing S corp status, the IRS requires you to pay yourself a reasonable salary before taking distributions. Reasonable salary is defined by the market rate for someone doing your job in your geographic area. If you're pulling $60,000 in profit and paying yourself a $30,000 salary to minimize self-employment tax, the IRS will likely flag that. I had a client who ran a digital marketing agency with about $140,000 in annual profit. He was paying himself $40,000 as salary and taking the rest as distributions. His CPA had set that up without checking Bureau of Labor Statistics data for marketing managers in his metro area, which showed a median salary closer to $72,000. The IRS audit didn't happen, but the exposure was real and the fix would have been costly. Another thing people overlook is state level variation. LLC laws differ significantly by state. Delaware is popular for corporations because of its Court of Chancery, but for a small business operating entirely in Ohio, forming a Delaware LLC just adds a registered agent fee and another annual report without any real benefit. Some states also treat LLCs differently for purposes of professional services. If you're a therapist, architect, or chiropractor in a state that restricts LLC formation for licensed professionals, you might be forced into a professional corporation or PLLC regardless of what you'd prefer. There's also the issue of investor readiness. Angels and VCs almost universally require a Delaware C corp. If you're an LLC or sole prop when they come knocking, you'll need to convert anyway, and that conversion triggers tax events. It's not catastrophic but it's unnecessary friction. I once told a founder waiting on a term sheet to convert his Colorado LLC to a Delaware C corp before the meeting. He asked why. The investor's legal team wouldn't touch anything that wasn't a Delaware corporation. The meeting got rescheduled twice while he waited for the conversion to process. By the time it was done, the investor had moved on to another deal. Conversion took eleven business days and cost about $2,500 including legal fees.
How To Actually Make The Decision
Write down three numbers: your expected annual revenue for the next three years, your personal risk exposure in the work you do, and whether you plan to bring in outside capital. If revenue stays under $60,000 and risk is low, start as a sole proprietorship and upgrade when it makes sense. If revenue is in the $60,000 to $200,000 range with moderate risk, an LLC is usually the right call. If you're pursuing significant outside funding or planning to scale aggressively, look at S corp or C corp from the beginning. Then run the numbers on your taxes. A quick spreadsheet comparing self-employment tax liability across sole prop, LLC, and S corp structures will show you the actual dollar difference. Don't guess. The difference between paying SE tax on $100,000 versus $60,000 is about $2,800, and that matters more than most people expect when you're operating on thin margins. The Forms Of Business Ownership discussion usually gets abstract because people talk about them in isolation. In practice they exist on a spectrum from least protected to most protected, from simplest to most complex, and from lowest overhead to highest compliance burden. Pick the one that matches where you actually are, not where you hope to be in five years. You can always upgrade later, but starting too complex is harder to fix than starting too simple.