So You Want to Understand Frank Abagnale In Catch Me If You Can
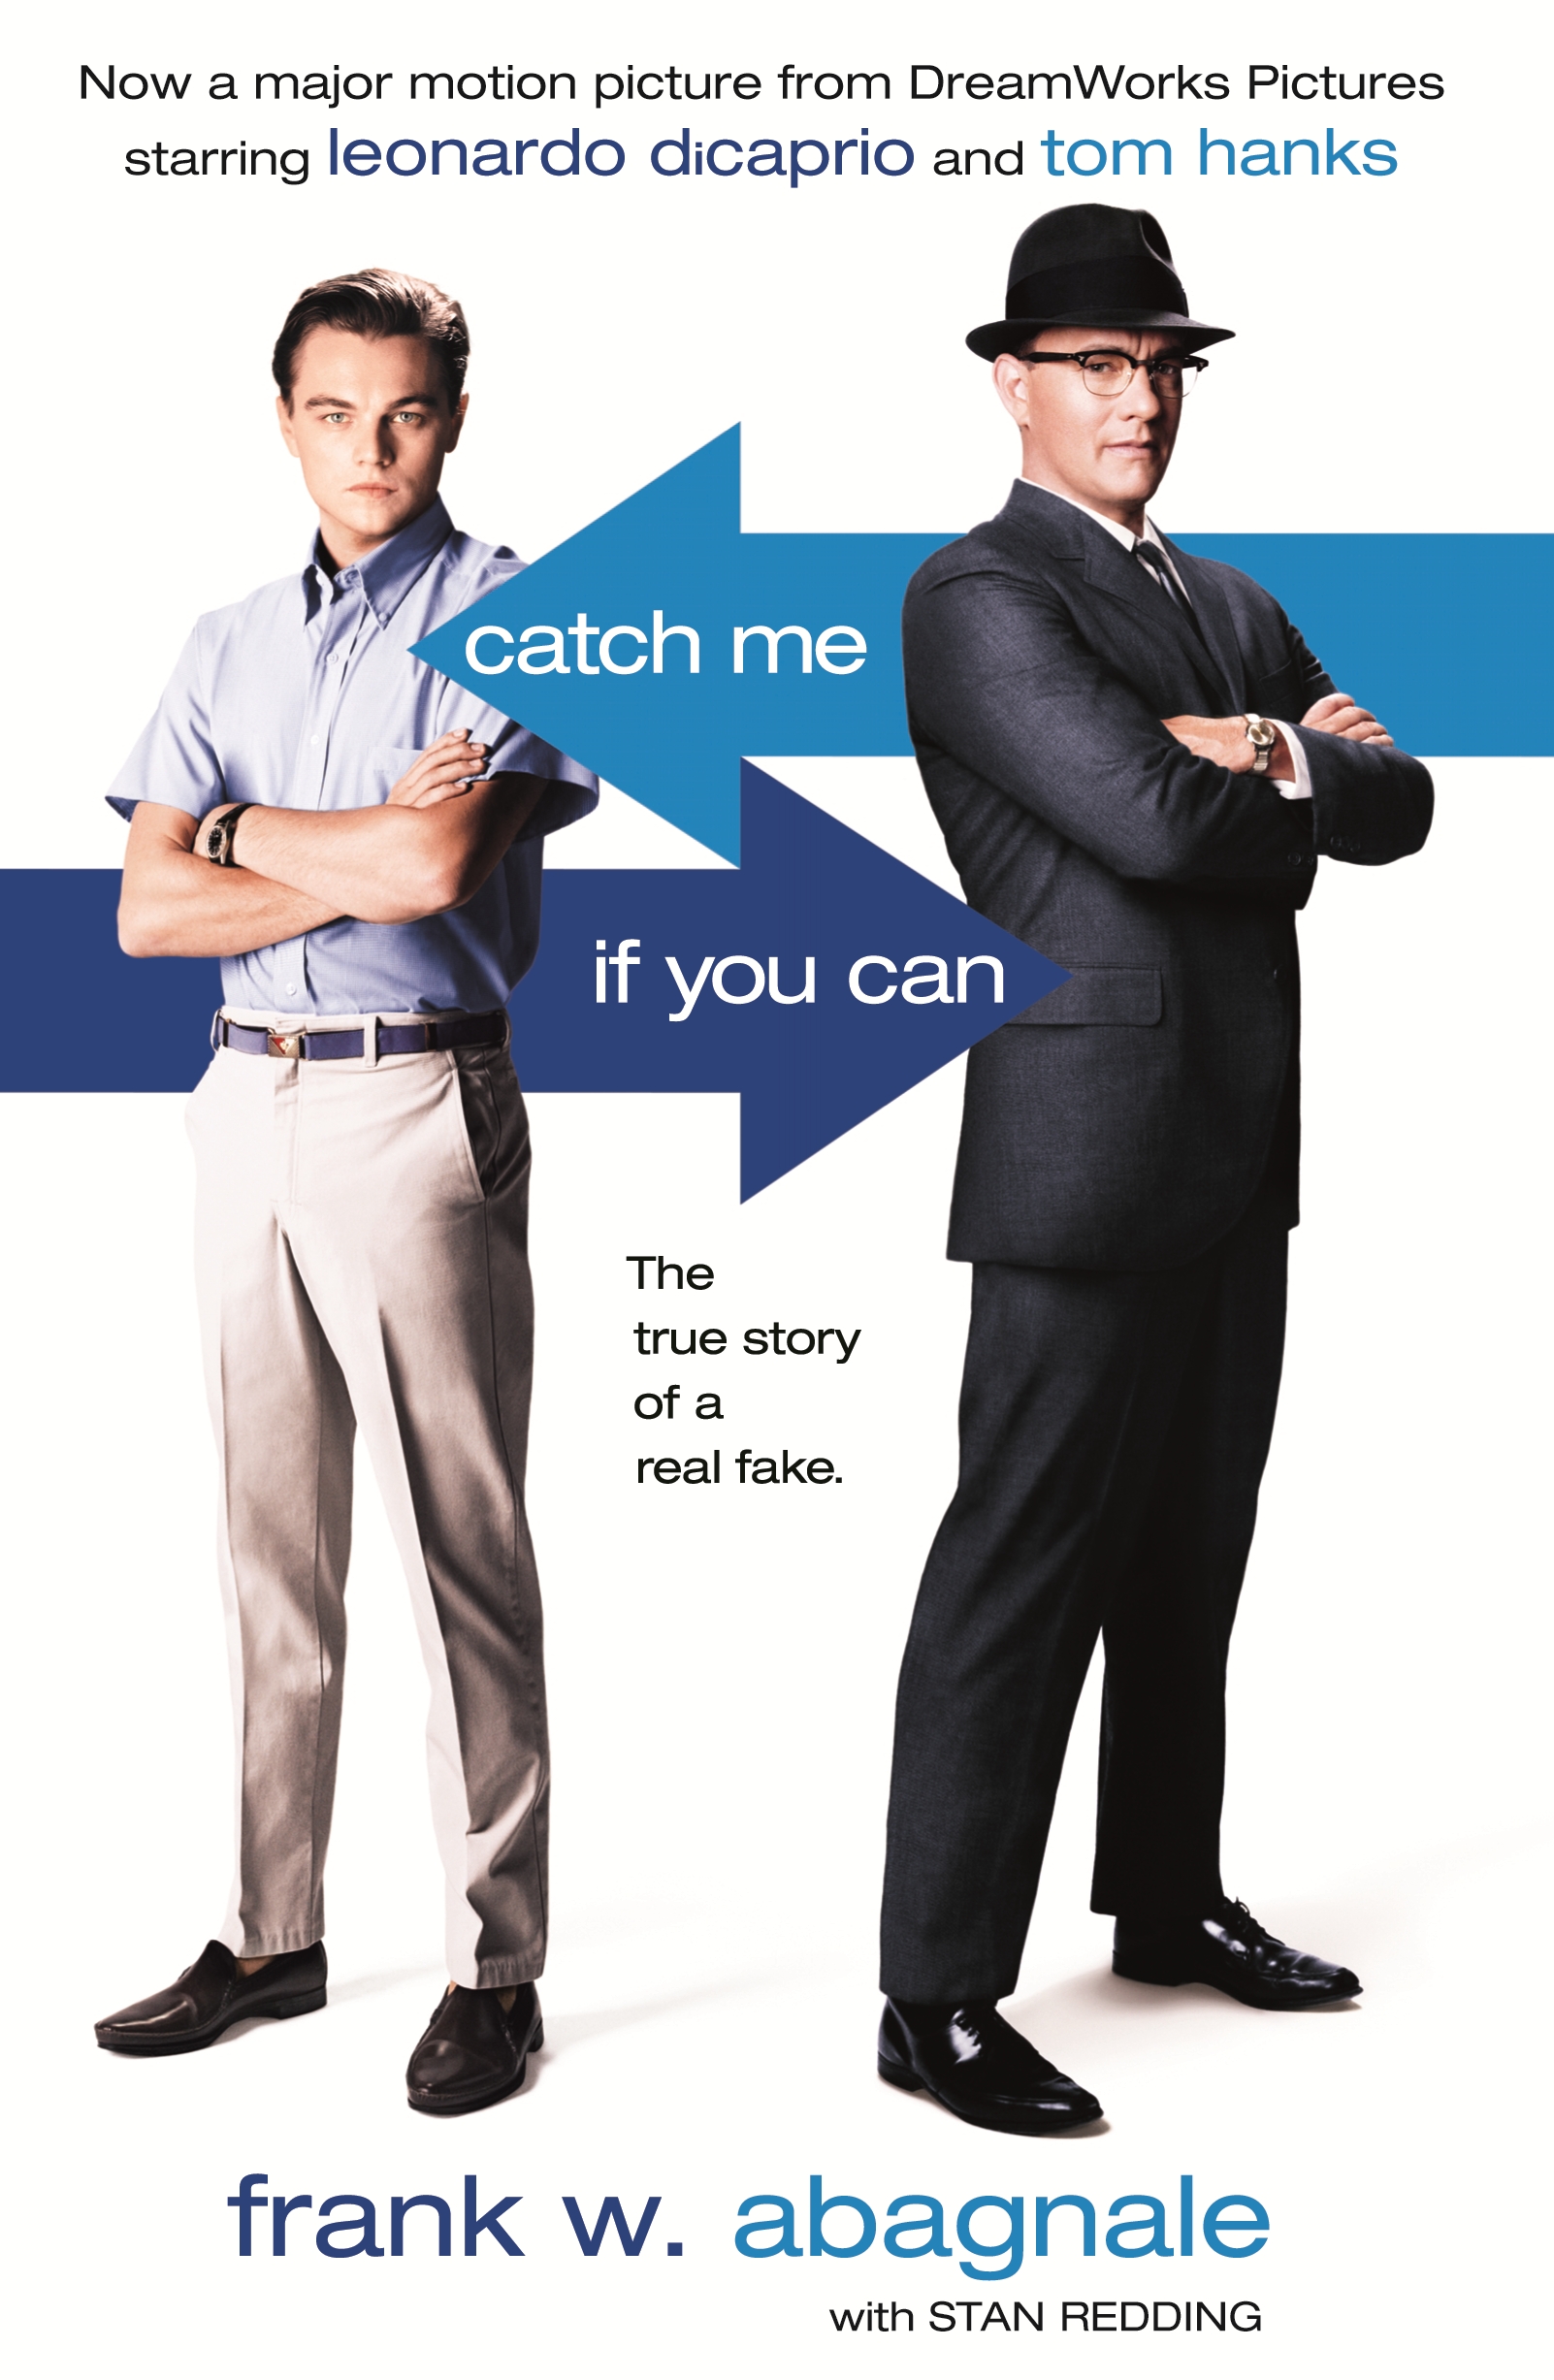
The movie came out in 2002, directed by Spielberg, and it turned one of the most unusual con men in American history into a cultural touchstone. Most people who watch it walk away thinking it's a charming caper film. It isn't really. It's a document of how a system that should have caught someone like Frank Abagnale failed at almost every level, and how he exploited that failure in ways that are still relevant to fraud prevention today. Frank Abagnale Jr. ran a check fraud scheme between 1964 and 1971 when he was seventeen to twenty-four years old. He forged bank checks using Pan Am employee uniforms, fake identification as a physician, and an assumed identity as a legal prosecutor. The total value he moved through the system is estimated somewhere around two to four million dollars in 1970s money, which adjusts to roughly twenty to forty million today depending on which inflation calculator you trust. The key detail that the movie smooths over is how little technical skill was actually required. Banks in the 1960s operated on paper-based clearing systems with minimal verification. A check could be deposited at one bank, forwarded through a regional processing center, and credited to an account before the issuing bank even saw it. Abagnale didn't need sophisticated skills. He needed access to blank check stock, a basic understanding of routing numbers, and the social confidence to walk into a bank and act like he belonged there. Those three things cost him almost nothing.
The movie compresses his timeline significantly. It also creates a fictionalized rivalry with the FBI agent Carl Hanratty, played by Tom Hanks. The real Hanratty did pursue Abagnale, but the dynamic was far less personal than the film suggests. Abagnale himself later acknowledged that Hanratty was one of the few agents who actually understood what he was doing, which is why the pursuit lasted as long as it did. I spent roughly six years working in financial fraud operations, and the first thing I noticed when I started studying the Abagnale case was how many of the techniques he used are still recognizable in modern fraud patterns. The specific mechanics changed because the infrastructure changed, but the underlying logic is identical: find the gap between what the system expects and what the system actually verifies, then step through it.
How Abagnale's Method Actually Worked
People always ask about the check forging technique, so let me explain it plainly. Abagnale bought blank check forms from a company called National Checking Service. They were genuine stock, legally produced, just uncirculated. He printed his own account information on them using a standard IBM electric typewriter and carbon paper to create theMICR line — the magnetic ink character recognition numbering at the bottom of the check. That's the line with the routing number and account number in those distinctive fonts that bank machines read. The real trick wasn't the forgery itself. It was the speed of the deposit cycle. Abagnale would deposit forged checks at different banks across multiple states, often using accounts he opened under his various aliases. Because inter-bank clearing in that era could take several days, the money would appear available in his account before the fraud was detected. By the time the check bounced, he'd already moved the funds or closed the account. One detail that almost nobody mentions: Abagnale's early success was partly due to a bank policy error. A Wells Fargo branch in Louisiana accepted a forged Pan Am pilot check without verifying the endorsement because the check was drawn on a New York bank and the branch assumed the identification chain was sound. That single lapse taught him something important. Verification was inconsistent across institutions, and that inconsistency was his primary vulnerability to exploit.
Get the Full Details

When I first analyzed this pattern while consulting on a bank fraud review project, I found the same inconsistency in a completely different context. We were dealing with merchant check acceptance in the early 2000s, and the problem was identical in structure, just operating at a different scale. A regional bank in the Midwest was accepting high-value checks from out-of-state merchants with minimal verification because their automated clearing system flagged transactions above a certain threshold differently than local deposits. The workflow assumption was that large out-of-state checks needed "extra caution," but the actual process required no extra documentation. It was a gap between policy and procedure, exactly the kind of gap Abagnale identified and exploited. The workaround I implemented was straightforward but costly. We restructured the clearing threshold so that all checks above five hundred dollars, regardless of geography or merchant history, went through a secondary verification step that required positive confirmation from the issuing bank. This added roughly twelve to eighteen hours to the deposit cycle for affected checks, which meant slower access to funds for merchants and more complaints from our retail clients. But it eliminated the class of fraud that was costing us approximately forty thousand dollars per month. The friction was the point. Verification slowdowns are the only thing that reliably stops procedural exploitation.
What the Movie Gets Right and Wrong
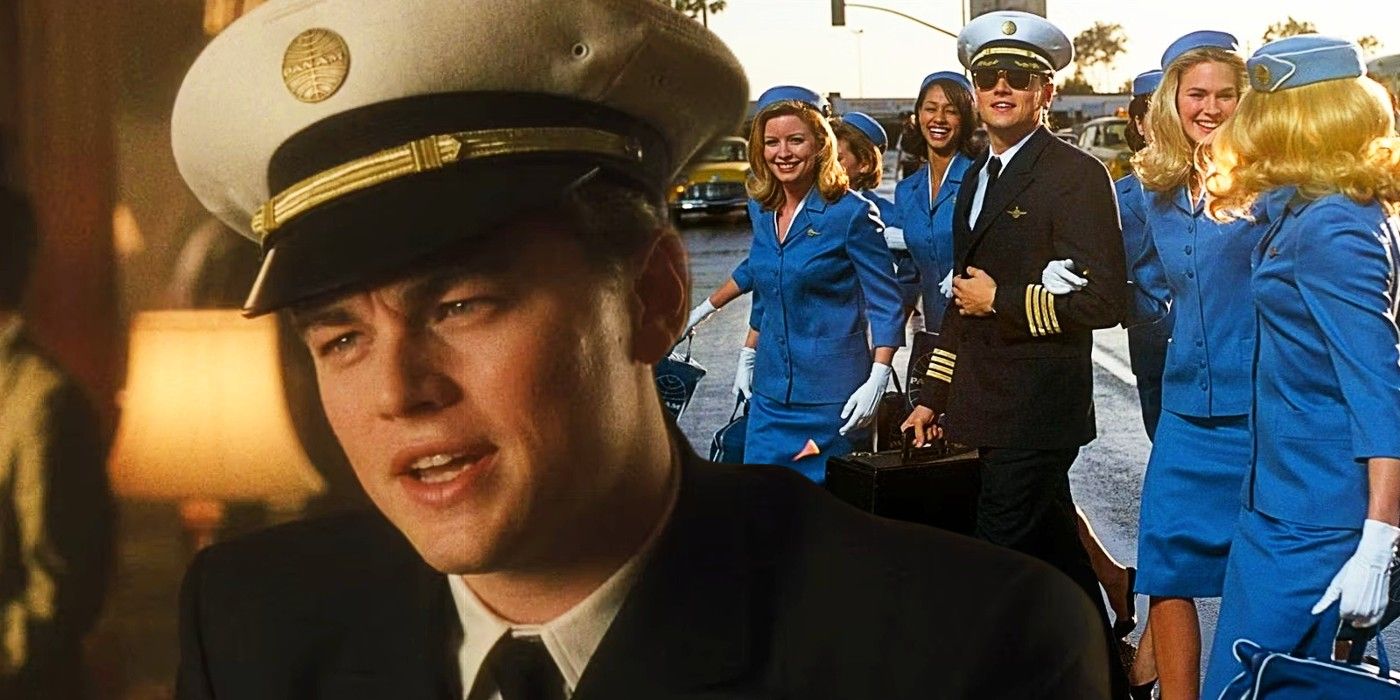
The film captures the social engineering component accurately. DiCaprio's performance shows Abagnale as someone whose real talent wasn't forgery — it was reading a room and adjusting his behavior to match whatever authority figure he was dealing with. The uniform work, the confident walk, the casual references to institutional procedures. That's the core of his method, and the movie gets it right. Where the film takes significant liberties is in the timeline and the personal dynamics. The real Abagnale was arrested in France in 1971 after a failed attempt to scam a airline employee out of first-class tickets. He was extradited to the United States, faced multiple federal charges, and was eventually sentenced to twelve years in federal prison. He served roughly five years before being released in 1976 after cooperating with authorities on fraud prevention matters. The movie ends with a fabricated epilogue showing Abagnale receiving a presidential pardon and Hanratty attending his wedding. Neither event happened. Abagnale never received a pardon from the president, and he and Hanratty did maintain a professional relationship after his release, but the specifics shown in the film are invented.
Abagnale himself has spent decades since then working as a fraud consultant, giving lectures, and writing books. He's legitimate about his past — he doesn't claim he was a hero or that the system was broken because it was evil. He says it was broken because it was complacent, and that's a meaningful distinction. Complacency can be fixed. Evil is harder to deal with.
The Counter-Intuitive Part Beginners Miss
Most people who study the Abagnale case focus on the con itself. The more interesting lesson is about the response. After his arrest, Abagnale became one of the most effective fraud prevention consultants in the country precisely because he understood the system from the inside. Banks and government agencies paid him to tell them where their processes failed, and he was relentlessly accurate about that. The counter-intuitive insight is that Abagnale's greatest contribution to fraud prevention came from the fact that he was caught. If he had never been apprehended, he would have continued exploiting gaps without any incentive to document them or share his methods with the institutions he victimized. His imprisonment created a situation where his expertise had value to the very people he defrauded, and that economic incentive reshaped how American banks approach check verification. There's also a less discussed limitation to everything Abagnale did. His entire operation depended on an analog infrastructure that no longer exists. Modern check processing, electronic fund transfers, real-time account verification, and biometric authentication make his specific techniques obsolete. The social engineering component survives — con artists still use uniforms and false authority — but the check fraud mechanism he perfected is essentially dead. Banks today don't clear paper checks the way they did in the 1960s, and the speed advantage he exploited through the clearing cycle is gone.
This means anyone looking at the Abagnale story as a practical guide to financial fraud is looking at a case study from a bygone era. The psychology is still relevant. The infrastructure is not. If you're studying this for academic or professional reasons, focus on the behavioral patterns and the institutional failures, not the specific techniques. The techniques are historical artifacts. The patterns are still alive.