What Actually Comes Up When You Sit Down for a Freddie Mac Interview
Most people walking into a Freddie Mac interview have no idea what they're walking into. They prep for generic finance questions and then get blindsided by something completely different. I went through this process twice — once trying to get in as a contractor and again later as a full-time hire. The second time went smoother because I stopped treating it like a normal banking interview. The core of Freddie Mac Interview Questions revolves around three areas: government-sponsored enterprise mechanics, credit risk modeling, and structured finance. If you can speak competently about all three without sounding like you just read a Wikipedia article, you're ahead of most candidates. That said, the actual day-to-day job matters more than textbook definitions. I once watched a candidate with a perfect CFA answer stumble when asked how they'd handle a GSE stress scenario involving portfolio-level prepayment risk. They knew the models but hadn't thought about what happens when the assumptions break.
Freddie Mac Interview Questions That Actually Matter
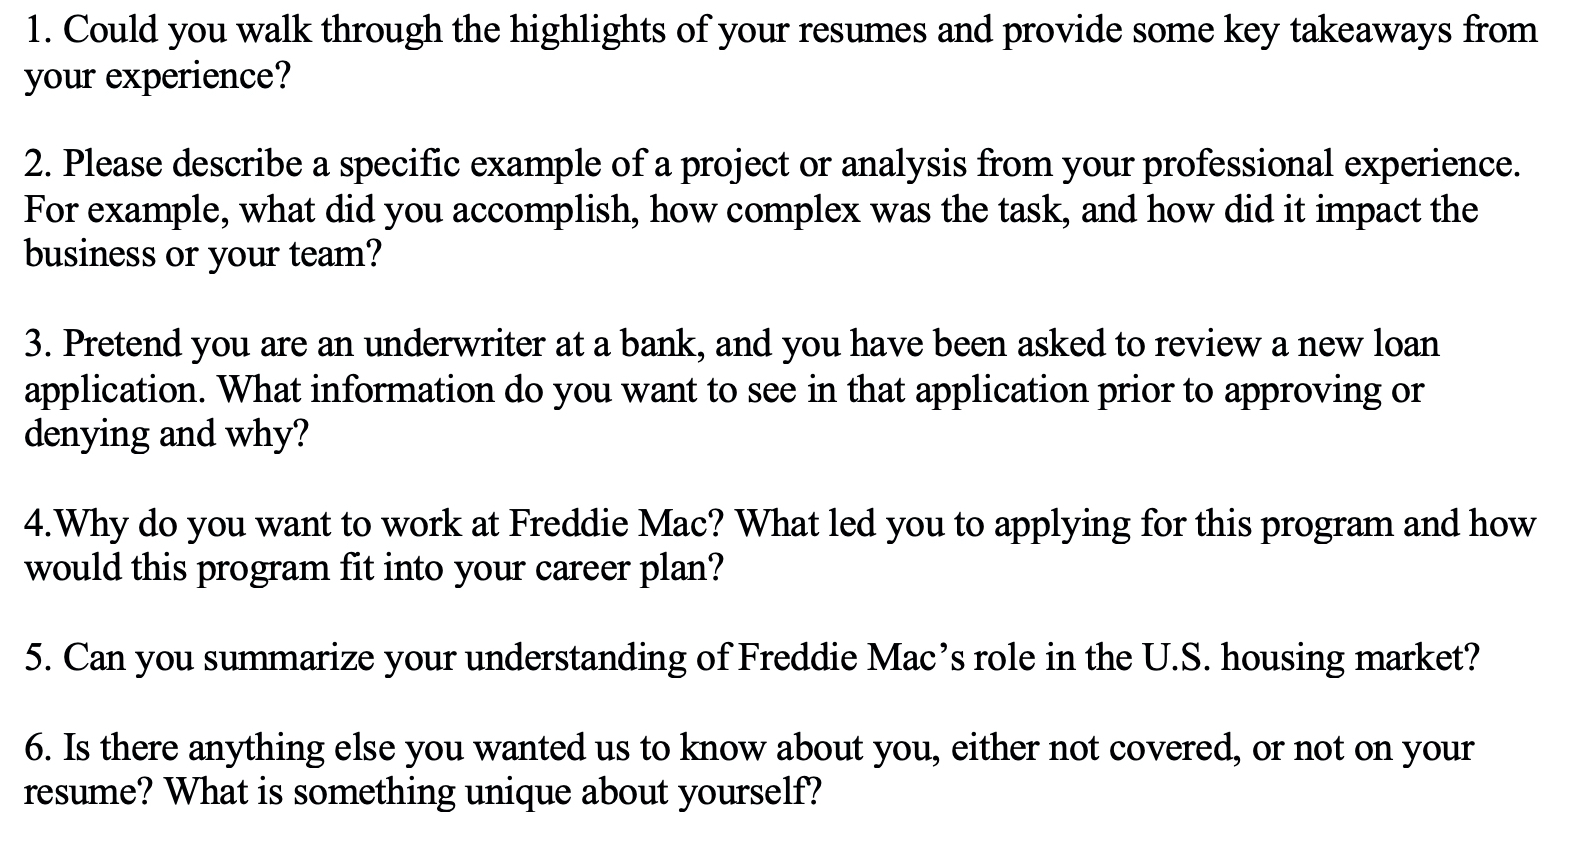
Don't waste time on questions like "tell me about yourself" or "where do you see yourself in five years." Yes, they ask those. But they also expect you to move through them without making it a production. The real happens in the technical section, which typically runs 30 to 45 minutes and varies depending on the team. For risk and analytics roles, expect questions on Monte Carlo simulation setup, convexity adjustments in mortgage-backed securities, and how you'd calibrate a prepayment model during a rate environment shift. I've seen people freeze on basic questions like "walk me through how a 30-year fixed rate bond's cash flows change when rates drop 200 basis points." The answer isn't just "prepayments increase." You need to talk about CPR, SMM, the hot month effect, and how curtailment behavior diverges from pure refinancing incentives. That gap between surface-level and actual understanding is exactly where most candidates fall apart. If you're interviewing for a product or operations role, the questions shift toward loan delivery standards, underwriting overlays, and the difference between eligibility and underwriting criteria. A lot of people confuse these two. Eligibility is binary — does the loan meet Freddie Mac's checklist? Underwriting is about risk tolerance. I remember helping a candidate prepare once and they couldn't explain the distinction clearly. When they showed up and got asked that exact question, they folded. It's a basic concept but almost nobody internalizes it until someone forces them to articulate it out loud.
How to Actually Prepare
The biggest mistake I see is people studying the wrong material. They pull practice questions from random interview prep sites that are built for investment banking or general finance roles. Freddie Mac operates differently. It's a GSE with a dual mandate — provide liquidity to the housing market while maintaining its own financial stability. That tension shows up in the questions. Start by reading Freddie Mac's Seller and Servicer Guide. Not skimming. Reading. Specifically the sections on loan eligibility, underwriting criteria, and product types. The document is dense and dry, which is exactly why nobody prepares with it. When I went through the process, I spent about 12 hours across two weeks working through the guide and taking notes on anything that felt ambiguous. That investment paid off directly. Two of the technical questions I encountered mapped almost line-for-line to scenarios described in Section 3030.1 and Section 4040.3 of the guide. Next, get comfortable with the basics of securitization. You should be able to explain how a conforming loan gets pooled, how the GSE guarantee works, and what happens to cash flows at each layer. If you're applying for a quantitative role, review how PAS (Predictive Analysis System) and HPA (Housing Price Forecast) feed into their underwriting models. These are proprietary tools, so don't pretend you know the internals, but understanding what they're used for and how their outputs affect decision-making will come up.
Get the Full Details
One practical tip that sounds obvious but almost nobody follows: look at the specific business unit you're interviewing for and research their recent publications or tool launches. Freddie Mac regularly releases things like the Uniform Residential Appraisal Database updates, changes to their risk-based pricing framework, or new delivery standards. If you can reference a specific recent initiative naturally during the conversation, it signals that you actually care about the organization rather than just landing any job in the sector. I once mentioned the transition to the Fannie Mae/Freddie Mac Common Securitization Certificate requirements during a follow-up discussion and it shifted the entire tone of the interview. Not because it was a trick question, but because it showed I'd been paying attention to industry movement.
A Problem I Encountered and How I Worked Around It
During my first interview cycle, I hit a wall with a question about how Freddie Mac handles mixed-income housing developments under the Low-Income Housing Credit (LIHTC) program. The interviewers were looking for me to walk through the interaction between LIHTC compliance periods and GSE underwriting standards. I knew enough to be dangerous but not enough to be confident. My answer was generic and they pushed back hard. After that interview, I spent a weekend going through Freddie Mac's multifamily underwriting guidelines and cross-referencing them with IRS Section 42 requirements. What I found was that the actual overlap is narrower than most people assume. LIHTC compliance affects rent restrictions and tenant income verification, but Freddie Mac's underwriting focuses on debt service coverage ratios, property condition reserves, and market absorption. The two frameworks run in parallel rather than intersecting deeply. I brought this insight up in my second interview cycle when a similar question came up, and it landed well because I was able to be specific about where the boundaries are rather than guessing at connections. This taught me a broader lesson about GSE interviews: the questions often probe the edges of your knowledge rather than the center. They want to know what you do when you're unsure, not whether you've memorized every guideline. Being honest about gaps while demonstrating how you'd find the answer is usually more valuable than padding a response with half-remembered details.
What Most Candidates Get Wrong
Over-preparing for the quantitative side while ignoring the operational reality is the most common pattern. Freddie Mac is not a hedge fund. It's a massive secondary market institution with strict regulatory oversight, and that culture bleeds into how they evaluate candidates. Technical ability matters, but so does comfort with process, documentation, and the procedural constraints that define daily work there. Another issue is treating the behavioral questions as separate from the technical ones. When they ask about a time you dealt with ambiguity or conflicting priorities, they're often testing whether your answer reflects a GSE-appropriate mindset. Saying you "moved fast and broke things" is the wrong framing. The right framing involves structured problem-solving, escalation paths, and risk-aware decision-making. I've seen strong technical candidates rejected because their examples made them sound like someone who'd create problems rather than manage them. There's also a subtle but important point about compensation expectations. Don't lead with salary in early rounds. Freddie Mac's pay bands are relatively standardized compared to private sector roles, and bringing it up too early can signal that you're evaluating the opportunity through a narrow lens. Save that discussion for when they bring it up, which they typically do in the later stages anyway.
Resources That Actually Help
Freddie Mac's own website has a center for industry resources, including their underwriting guidelines, product brochures, and data dashboards. The Multifamily and Single Family guides are the two documents worth your time. Beyond that, the Mortgage Bankers Association publishes regular commentary on GSE policy shifts that can help you understand the context behind the questions. For quantitative roles, reviewing the Federal Housing Finance Agency's quarterly risk reports gives you a sense of what Freddie Mac's leadership is tracking externally — and that awareness comes up in interviews more often than you'd expect. If you want something concrete to work through, take a Freddie Mac loan delivery example and walk through it end-to-end yourself. Pick a sample case from their training materials, determine whether it meets eligibility, run through the underwriting steps, and identify where a real-world edge case might trip things up. This exercise takes about an hour and forces you to engage with the actual material instead of passively reading it. I did this before both of my interviews and it changed how I approached the technical sections. Instead of recalling facts, I was reasoning through scenarios the way I'd actually handle them on the job. One last thing that doesn't get enough attention: the interviewers at Freddie Mac are often the same people you'd be working alongside. They can usually tell when someone is performing versus when someone is genuinely engaged with the material. Don't try to impress them with how much you know. Impress them with how clearly you think when you don't know something. That's the skill that carries through the actual work.