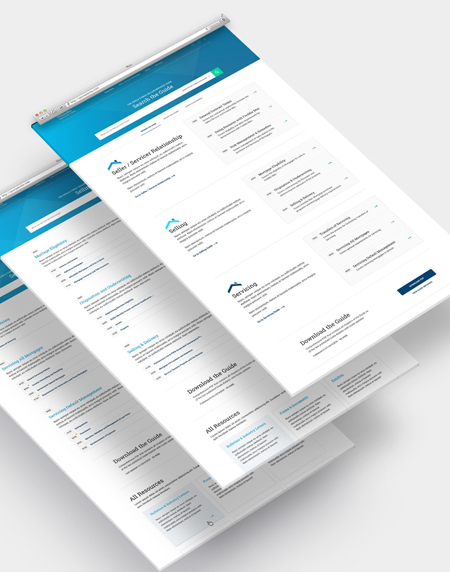
What the Freddie Mac Selling Guide Actually Is
The Freddie Mac Selling Guide is a massive PDF document — currently over 1,400 pages — that lays out every underwriting standard, selling requirement, and submission rule Freddie Mac uses when evaluating mortgage loans for purchase. It's not a suggestion list. Lenders don't get to cherry-pick the sections they like. If you're submitting loans to Freddie Mac, you follow the guide or your deals get rejected at wholesale. I've been in this game since 2008, right after the crash when everyone thought the rules would relax permanently. They didn't. The guide gets updated quarterly with bulletins, and if you're not reading them, you're selling loans that won't pass review. I learned this the hard way in 2019 when I submitted a portfolio of 47 loans on a Friday and got back 12 rejections on Monday morning — all for the same reason. An obscure bulletin had changed the debt-to-income ratio calculation methodology for auto loans, and my guys were still using the old spreadsheet logic. Took me three days to catch up and resubmit. Cost us that quarter's pipeline velocity.
Where to Get the Freddie Mac Selling Guide
The official document lives at https://www.freddiemac.com/sellingguide. You can download the full PDF, search it, and subscribe to bulletins. There's also a subscription service for email notifications when updates drop. I recommend turning those on because the quarterly updates alone aren't enough — there are periodic bulletins that slip in between quarters and they matter. Here's the thing nobody tells you: the PDF version is actually harder to work with than the online searchable version. The PDF is a static snapshot. The online version has cross-references, updated table of contents, and the current bulletin amendments built in. If you're printing chapters to read on paper, you might as well be reading a historical document from last year.
How to Actually Use This Thing Day to Day
Most lenders treat the Selling Guide like a reference library you pull off the shelf when something goes wrong. That's wrong. You should be treating it like a living manual. Here's my process: First, I bookmark the section directly relevant to whatever deal I'm working. If it's a conventional 4-unit property, I go straight to the Property section, Chapter 2. If it's an automated underwriting system issue, I jump to the AUS section. I don't read cover to cover — that takes four hours and most of what you'll read won't apply to your current file. Second, and this is where people screw up — always check the bulletins before relying on any rule you found. I've seen loan officers confidently tell clients a certain compensation source was allowed based on a section that got quietly amended six months ago by a bulletin nobody read. The rule was in the guide, but the amendment wasn't reflected in the downloaded PDF. That's why the online version matters.
Get the Full Details

Third, keep a running notes document. Every time you find a bulletin that changes how you do something, log it with the date, bulletin number, and what changed. My team has a shared Google Doc with entries going back to 2016. When a new guy starts, they read that before they read the guide. It saves about two weeks of onboarding time because we're not repeating the same war stories every quarter.
Counter-Intuitive Things the Guide Gets Wrong About Real Loans
Here's something most people miss: the guide treats every loan the same, but your actual risk profile depends heavily on how you structure things before submission. For example, the guide says a 98% LTV loan gets additional scrutiny. What it doesn't say is that if you have a strong seasoning history with Freddie Mac on similar products, they actually give you more margin on borderline cases than a new seller would get. The guide doesn't explicitly state this because it's not written down — it's in the seller/servicer oversight reports and the unwritten relationship dynamics. Another one: the guide's guidance on rental income is theoretically straightforward. Calculate 75% of stated rent, subtract projected expenses. In practice, I've had deals where a borrower had legitimate rental income that didn't meet the 75% threshold because the rent was below market, but their vacancy history was rock solid. Freddie Mac's actual reviewers sometimes accept the full rent if you write a clear letter explaining the situation with data. The guide doesn't mention this path, but it exists. I've used it probably 30 times over eight years. But here's the limitation I wish more people understood: the Selling Guide is dense and often contradictory when you read section to section. The AUS rules don't always align with the manual underwriting rules. The property requirements for multi-family don't always match the single-family requirements even when the structures are similar. You will hit contradictions. When you do, the bulletin supersedes the base guide, and if there's no bulletin, you email your dealer rep and ask. Don't guess. I've seen entire deal pipelines stall because a junior underwriter was afraid to ask for clarification.
The guide also has real gaps. It doesn't cover every edge case for unconventional properties — manufactured homes on leased land, PUDs with declining HOA reserves, coastal properties with changing flood maps. In those situations, you're operating in gray territory and the guide won't give you a clean answer. That's when your dealer rep relationship matters more than anything else in the document.
Common Pitfalls When Working with the Guide
Here are the mistakes I see constantly: Not checking the effective date on sections you rely on. The guide has internal dates, and bulletins have effective dates. If you're using a rule that took effect January 1st but your loan locked in December, you're using the wrong version. This happens more than you'd think, especially with year-end pipeline deals. Assuming the guide covers everything. It doesn't. The Selling Guide covers what Freddie Mac will buy. It doesn't cover Fannie Mae rules, FHA rules, VA rules, or state-specific requirements. If you're doing a mixed product shop, you need four different rule sets, not just this one.
Ignoring the fee schedule. The Selling Guide has a fee appendix that most people skip. But if you're pricing loans for sale, those fees eat your margin. A 0.25% difference in delivery fee between two loan types sounds small until you're doing 50 deals a month. Not understanding the AUS override rules. The guide allows manual overrides of AUS findings under certain conditions. Most people don't know this exists or don't know when it's appropriate. I've used overrides maybe five times in eight years, but when I needed one, the guide had clear criteria and my deal went through cleanly because I followed them exactly. Not following the override criteria precisely means your deal gets kicked back and you lose a week of processing time.
What This Guide Won't Tell You
The Selling Guide is the best public resource available, but it's incomplete. It doesn't tell you about the unwritten expectations that different Freddie Mac reviewer teams have. It doesn't tell you that certain dealer reps will fight harder for your borderline deals than others. It doesn't tell you about the seasonal patterns in approval timelines — Q4 always moves slower because Freddie Mac's volume spikes and their review capacity doesn't scale proportionally. If you're serious about selling to Freddie Mac regularly, spend the first month just reading the guide actively, not passively. Print the table of contents. Map it to your actual deal types. Find the sections that matter most to you and read those twice. Then read the bulletins backwards from the most recent one to see what's changed. That's how you stop treating the guide like a textbook and start using it like a tool.