Break-even analysis is one of those things everyone learns in a business 101 class and then immediately forgets because the spreadsheets they were given were complete nonsense.
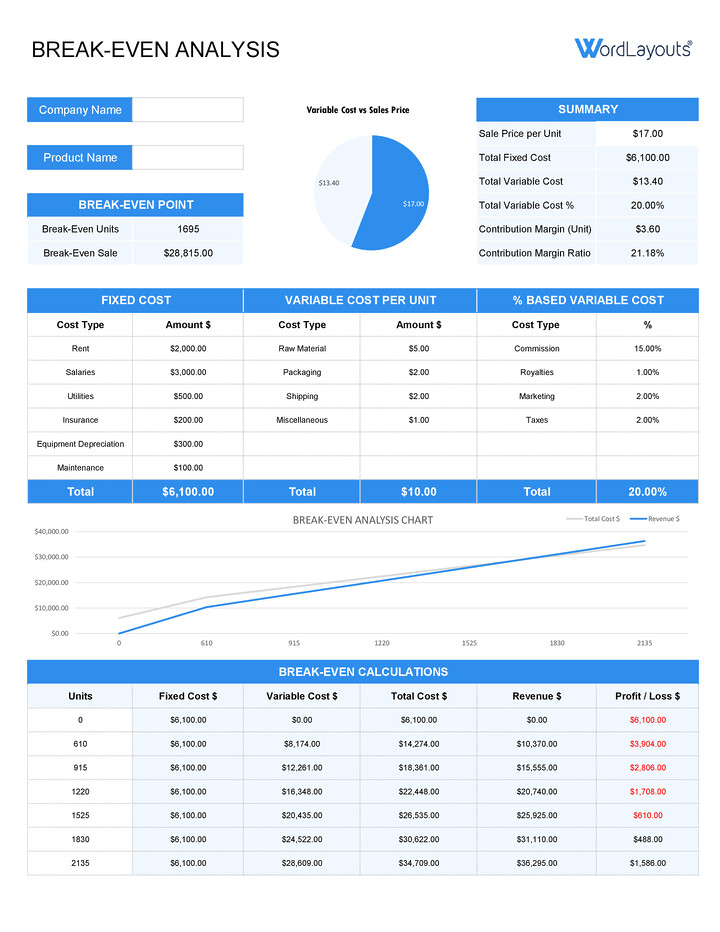
The actual calculation is trivial. Total fixed costs divided by the contribution margin per unit. That's it. What people don't understand is that the formula tells you almost nothing useful on its own. It gives you a number, like "you need to sell 2,400 units," but it says nothing about whether 2,400 units is realistic, achievable, or even possible given your market size. I spent years building and refining templates for small to mid-sized businesses, and the ones that actually get used are the ones that force you to confront the uncomfortable assumptions behind the math. The Free Break Even Analysis Template I put together does that. It doesn't just calculate a number. It makes you enter each cost component separately and shows you which variable is moving the needle the most.
Free Break Even Analysis Template
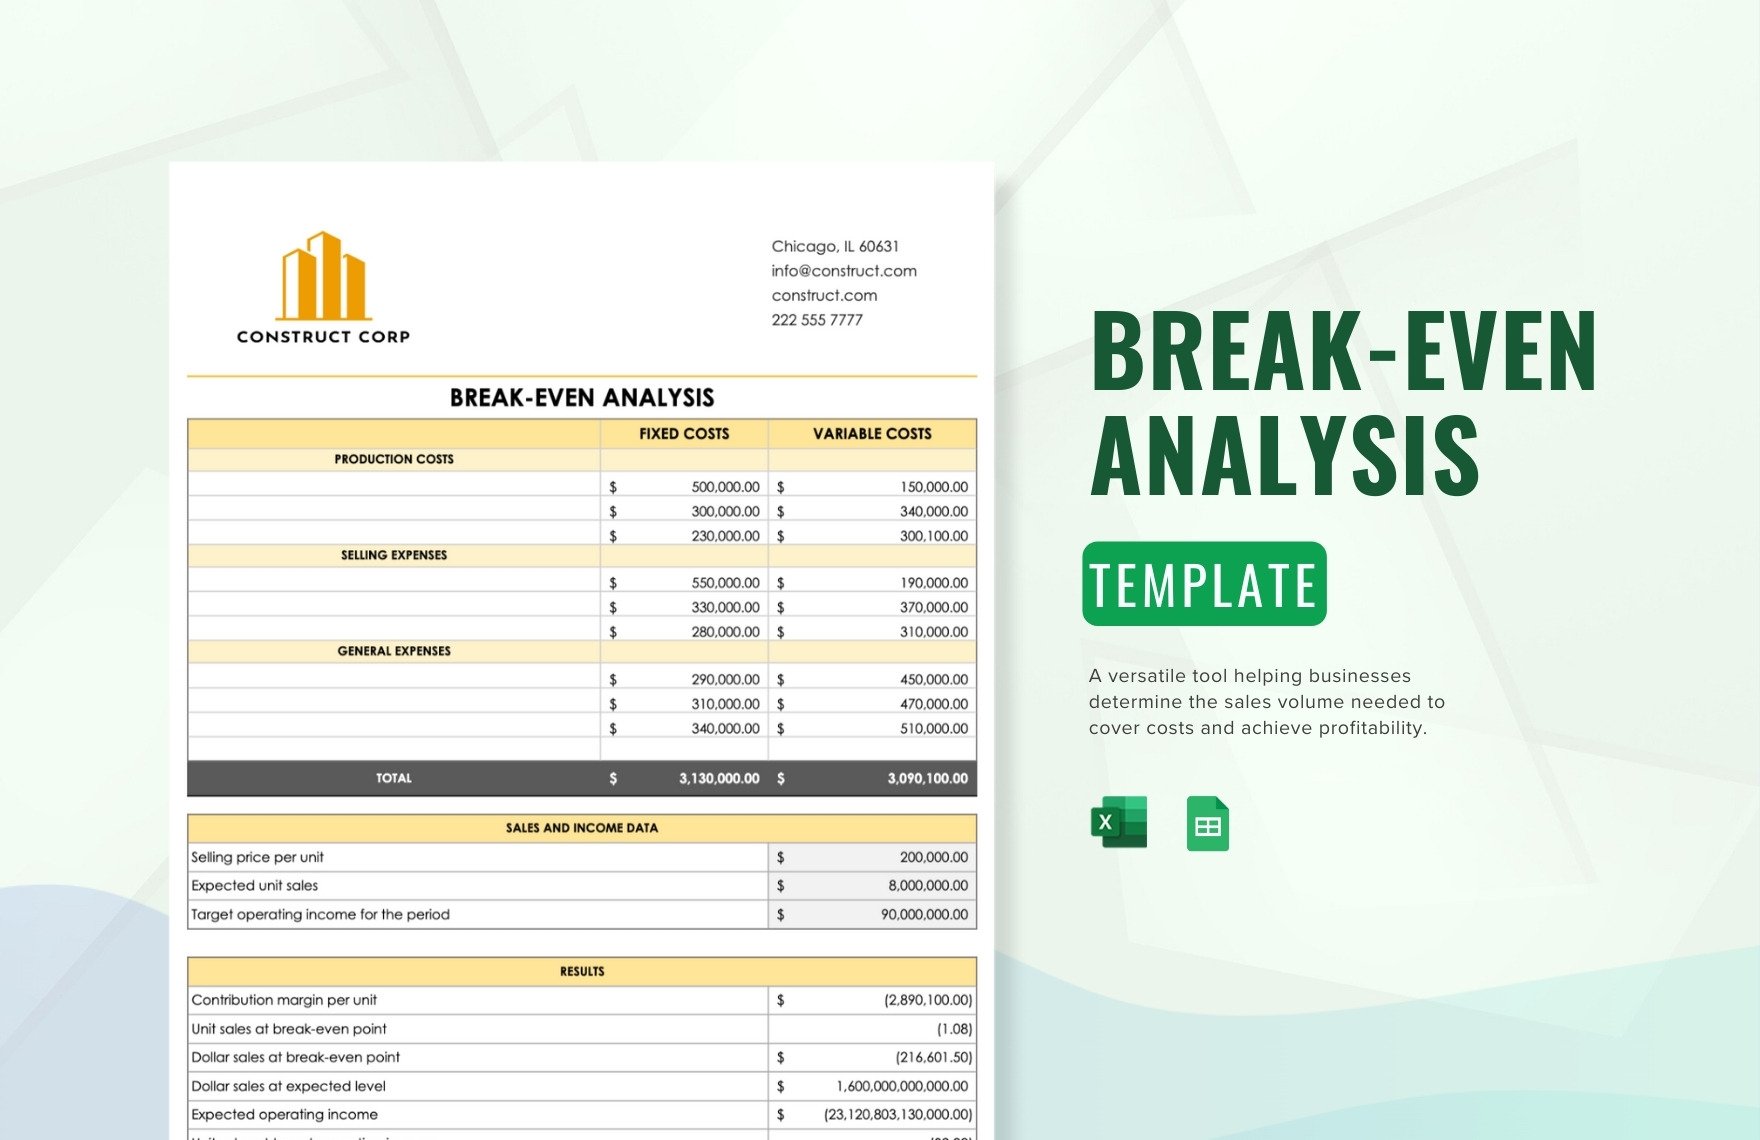
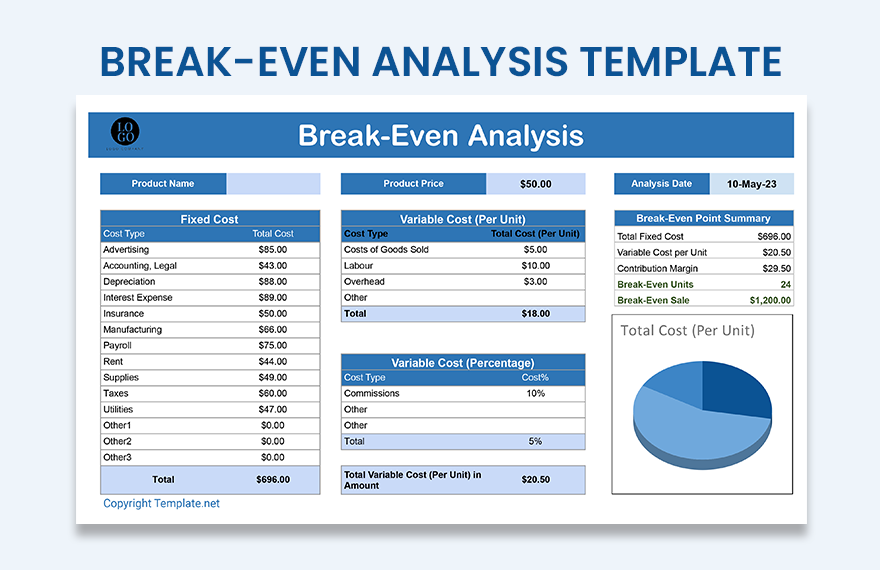
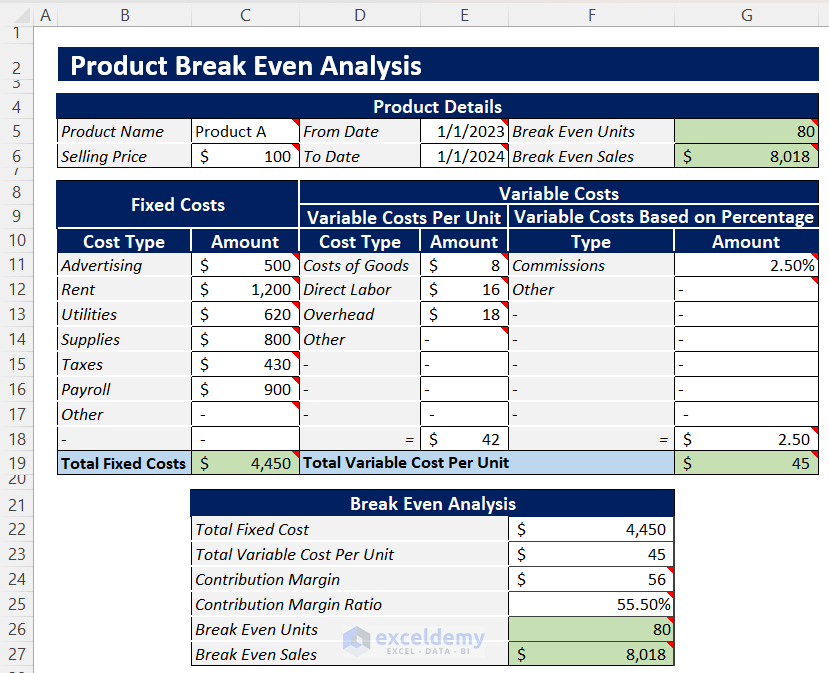
Here's how it works in practice. You set up three input categories: fixed costs, variable costs per unit, and selling price per unit. Fixed costs are the things that don't change whether you sell one unit or one thousand. Rent, insurance, software subscriptions, salaried staff. Variable costs are the things that scale directly with production. Raw materials, shipping, payment processing fees, packaging. The contribution margin is simply the selling price minus the variable cost per unit. Divide total fixed costs by the contribution margin and you get the break-even point in units. That last part is where most templates fail. They give you a single output cell and stop there. A functional template should also show you the break-even point in dollars, which is the break-even units multiplied by the selling price. This matters because investors and lenders rarely care about units. They care about revenue. When I was advising a friend who ran a custom furniture shop, his break-even was 120 tables per year at $800 each. In dollars that's $96,000. In units that's 120. The dollar figure looked manageable. The unit figure looked harder. The gap between them determines how you communicate the risk to different audiences. There's a specific edge case I ran into repeatedly that most templates don't handle: multi-product businesses. Say you run a coffee shop that also sells merchandise. Your fixed costs are the same regardless of what you sell, but your contribution margins are completely different between coffee and t-shirts. A standard break-even calculation collapses here because there's no single unit to measure. The workaround I use is a weighted average contribution margin approach. You assign a sales mix percentage to each product line, calculate the contribution margin for each, and blend them into a single weighted figure. From there you divide fixed costs by the blended margin and get a composite break-even in total units, which you then allocate back to each product based on the mix you entered. It's not perfect. It assumes your sales mix stays constant, which it never does in reality. But it's far better than pretending a coffee shop has one product.
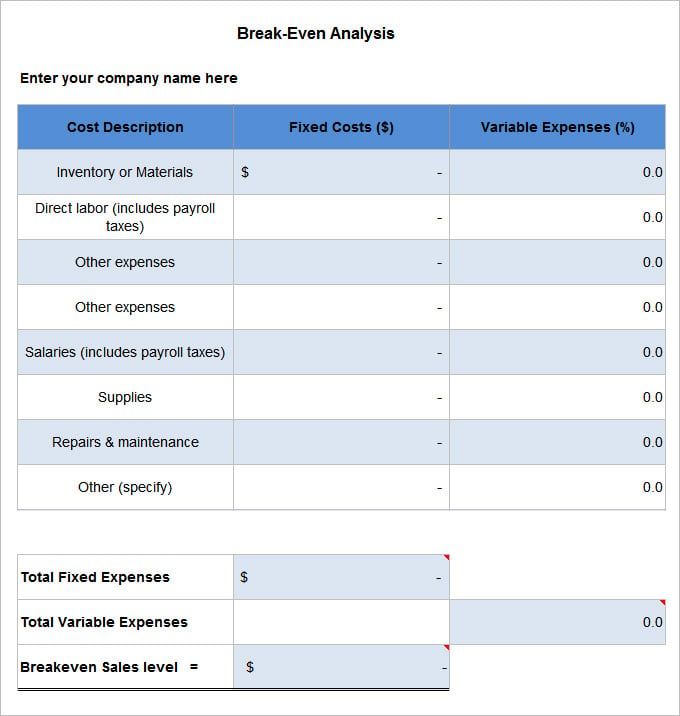
Another thing nobody talks about is the difference between cash break-even and accounting break-even. Accounting break-even includes depreciation and amortization as fixed costs. Cash break-even excludes them because you've already paid for those assets. For a capital-intensive business like manufacturing, the gap between the two numbers can be massive. I worked with a small injection molding company where the accounting break-even was 5,000 units per month and the cash break-even was 3,200. Running your cash flow model off the accounting number would make the business look way more dangerous than it actually is. Running it off the cash number would make you ignore the fact that your equipment will eventually need replacement. Use both. Label them clearly. Don't let anyone conflate them. When you're building your own template, keep these practical considerations in mind. Always separate your fixed costs into short-term and long-term buckets. Short-term fixed costs are commitments you can change within a quarter. Long-term fixed costs are leases and contracts that lock you in for a year or more. A template that treats them the same will give you a break-even point that looks achievable today but is impossible to hit next quarter when a lease renewal hits. Enter the short-term number in one column and the long-term number in another, and calculate break-even for each scenario separately. Variable costs are where people get sloppy. They estimate material costs once and never update them. If you're running a template for a business that sources from multiple suppliers or deals with commodity pricing, set up a sensitivity table that shows break-even at five different cost-per-unit scenarios. Something like $4.50, $5.00, $5.50, $6.00, and $6.50 per unit. This takes about three minutes to set up in any spreadsheet and saves you from waking up at 2 AM realizing your variable costs jumped 15% and your break-even just moved by 400 units overnight.
Get the Full Details
Here's a counter-intuitive point that trips up beginners: raising your price doesn't always lower your break-even point in a straightforward way. If you raise the price and demand drops significantly, you might sell fewer units but each unit contributes more. Whether the break-even improves depends on the price elasticity of your product. For a commodity product, a small price increase barely moves the contribution margin but may lose you 20% of your customers. For a differentiated product with loyal customers, the same price increase could barely affect volume while significantly improving the margin. There's no universal rule. You have to model it with your actual estimated demand curve at each price point. The Free Break Even Analysis Template I designed includes a built-in scenario comparison tab where you can stack at least three different situations side by side. I call them conservative, base, and aggressive, but you can name them whatever makes sense for your business. Each scenario has its own fixed cost, variable cost, and price inputs. The template calculates the break-even for all three simultaneously and highlights the difference between them. This is genuinely useful when you're preparing for a pitch or a board meeting. Instead of saying "we break even at 2,000 units," you can say "we break even between 1,600 and 2,800 units depending on how market conditions play out." That's a more honest answer and it builds more trust than a single number ever will. Let me be clear about what this template cannot do. It cannot predict whether you will actually sell enough units. It cannot tell you if your market is large enough to support your break-even volume. It assumes your costs are linear, which means it doesn't account for economies of scale or step-fixed costs that jump when you cross a certain threshold. It doesn't factor in seasonality, which is relevant for businesses where revenue is heavily concentrated in certain months. If your business is seasonal, you need a monthly version of this analysis, not an annual one. The annual break-even number is meaningless if you only generate 70% of your revenue in four months.
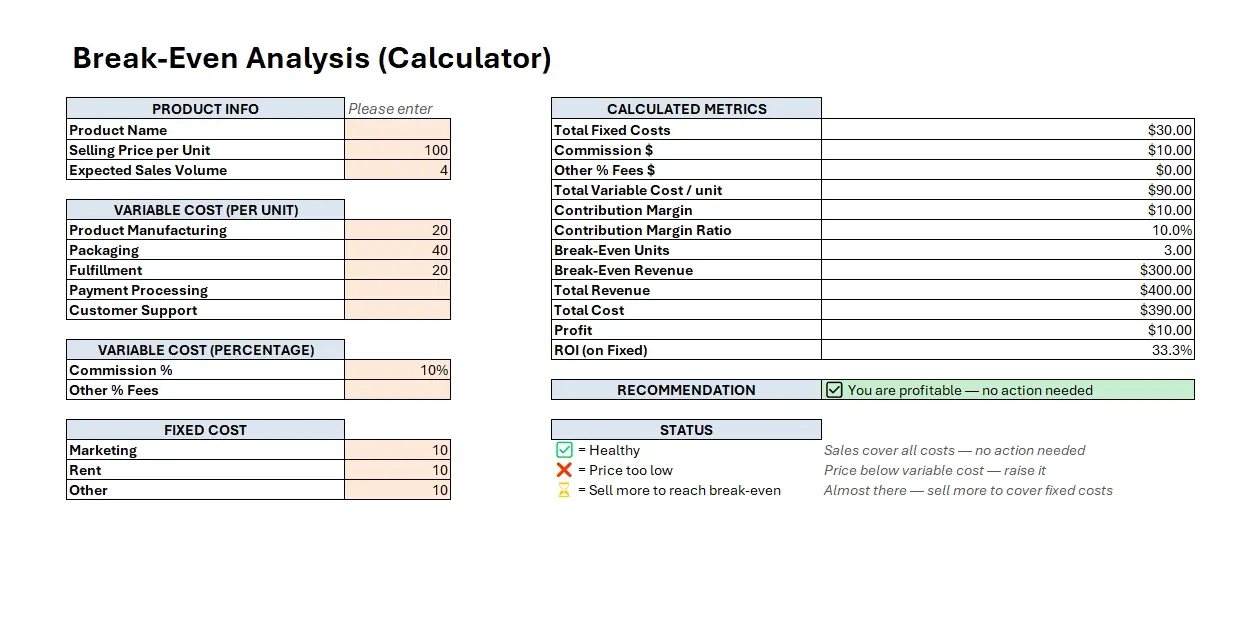
There are also scenarios where break-even analysis as a concept is simply the wrong tool. Service businesses with very high labor costs and low variable costs often have break-even points that are so close to zero that the number provides no guidance. A consulting firm where the main cost is the owner's time isn't really a variable cost in the traditional sense. Pricing strategies for subscription businesses require a different framework entirely, usually LTV:CAC ratios and churn-adjusted models. Don't force a break-even template onto a business model where it doesn't fit. For the template itself, the structure I recommend is straightforward. Input section on the left with labeled cells for fixed costs, variable costs per unit, selling price, and estimated monthly sales volume. Output section on the right showing break-even in units, break-even in revenue, margin of safety percentage, and a simple profitability projection at your estimated sales volume. Add a third section for scenario comparison if you want it. Keep the formulas explicit. Don't hide calculations behind complex nested functions. Future-you or anyone else who inherits this spreadsheet should be able to open it and understand every number within thirty seconds without tracing cell references across five sheets. One more practical note about data entry. Enter costs in the same currency and on the same time basis. If your fixed costs are monthly but your variable costs are quoted per annual batch purchase, convert everything to monthly before plugging it in. I've seen people mix annual and monthly figures and get break-even numbers off by a factor of twelve. The formula doesn't care about your mistakes. It will happily give you a precise wrong answer.
You can find the Free Break Even Analysis Template at the link below. It's structured for Google Sheets and Excel, includes the scenario comparison tab, and comes with a brief setup guide that walks through the coffee shop multi-product example I mentioned earlier. The setup should take about ten minutes if you already know your cost structure. If you're still figuring out your costs, budget another thirty minutes to research and fill in the inputs accurately. The quality of your break-even analysis is entirely dependent on the quality of your cost estimates. A perfect template with garbage inputs produces garbage outputs. That's not a limitation of the tool. That's just basic accounting.