Why Your Home Equity Math Is Probably Wrong
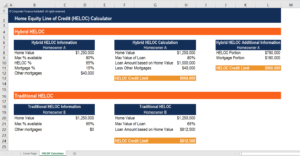
I've watched people plug numbers into free calculators and come out convinced they had $80,000 in available credit when they actually had about $32,000. The gap isn't magic. It's the difference between how a calculator models things and how lenders actually model things. The basic input set looks straightforward on the surface. You put in your home value, your outstanding mortgage balance, and sometimes your credit score. Hit calculate and it spits back a number. That number is useful as a starting point, not as a final answer. The real equation involves more than three fields. Lenders typically cap your total borrowing at 80 to 90 percent of your home's appraised value minus what you already owe. A lot of free calculators skip the appraisal adjustment and just use whatever list price or Zestimate you typed in. That single oversight can swing your result by tens of thousands of dollars depending on how much the market has moved since you last looked at your house.
Using a Free Home Equity Line Of Credit Calculator Correctly
Start by pulling your most recent property tax assessment or a formal appraisal rather than trusting a ballpark figure from a real estate website. Those automated valuations average within 3 to 5 percent of actual sale prices in normal markets, and we are not in a normal market right now. Plug that number into the calculator. Then subtract your current mortgage balance, any second mortgages, and any home equity loans you already carry. Multiply the remaining equity by 0.85 to get a realistic HELOC ceiling. From there, factor in your debt-to-income ratio. Most lenders want your total monthly debt obligations, including the new HELOC payment, to stay under 43 percent of gross monthly income. If you are already near that threshold, the calculator's output means almost nothing until you restructure your debts first. Here is the part nobody mentions when they are just looking for a quick estimate. The calculation ignores the fact that most HELOCs have a draw period of five to ten years where you only pay interest, followed by a repayment period where the full balance gets amortized over maybe ten more years. That means your monthly payment can triple without you borrowing an extra dollar. I ran into this exact scenario with a client last year. The calculator showed a comfortable $400 per month payment. At the start of the repayment phase, his payment jumped to $1,150 because he had drawn $62,000 and the lender was now amortizing it over 15 years at 8.75 percent. He was not prepared for the shift at all. The workaround was simple: I had him model the repayment phase payment inside the calculator by manually entering a hypothetical balance equal to his projected draw amount and setting the term to the expected repayment length, usually ten to fifteen years depending on the product. That gave him a number he could actually budget around instead of the bait-and-switch teaser rate his loan officer was quietly counting on him to ignore.
Another thing most online calculators gloss over is the variable rate component. HELOC rates move with the prime index plus a margin, and that margin is where the real negotiation happens. Two borrowers with identical credit scores and equity levels can get margins that differ by 1.5 to 2 percentage points just by shopping around. A free calculator will default to the national average rate, which in practice is usually 0.5 to 1 point higher than what competitive lenders are offering right now. That discrepancy eats into your usable equity every single month because your payment estimate will be artificially inflated, making you think you have less room to borrow than you actually do, or worse, making you price out of a project you could have affordably funded. There are also edge cases that break the calculator entirely. If your home has recently undergone major improvements that are not yet reflected in public records, the calculator will understate your equity. If you are on a USDA or VA loan with no stated mortgage balance because the financing works differently, the input field will mislead you. And if you have homeowner association special assessments pending, those count against your debt-to-income ratio even though the calculator has no field for them. I learned about the HOA issue the hard way. A borrower had a $12,000 special assessment coming due that she never disclosed because she assumed it was irrelevant. The lender pulled her financing two weeks before closing after the debt-to-income calculation went over 43 percent. Had she known to include it upfront, we would have either paid down part of the assessment beforehand or adjusted the requested loan amount to stay within the limit. The other counter-intuitive detail is that your credit score affects both your approval odds and your available credit limit independently of the rate. Some lenders will approve you at 680 but cap your line at 60 percent of your eligible equity instead of the full 85 or 90 percent. The calculator cannot predict this without knowing which lender program you are targeting, so treat the output as a range, not a guarantee. If you are sitting at the lower end of the acceptable score band, assume you will get the lower end of the LTV range unless you have strong compensating factors like significant cash reserves or a very low existing debt load.
Get the Full Details

If you want a practical alternative to pure online estimation, run the same inputs through a lender's prequalification tool after you have your numbers ready. Prequalification uses a soft credit pull and factors in your actual credit profile, which shifts the result more accurately than any static calculator can. It usually takes about ten minutes and gives you a real starting point that you can then refine with a full application if the terms look reasonable. So the free calculator is worth keeping in your workflow as a first pass. It gets you into the right neighborhood fast. But the moment you are serious about using it to make a decision, you need to layer in the appraisal adjustment, the repayment phase projection, the rate margin negotiation, and any hidden debt obligations sitting outside the standard input fields. Skipping any of those steps is how people walk away from closing with a product they did not expect and a payment they cannot sustain.