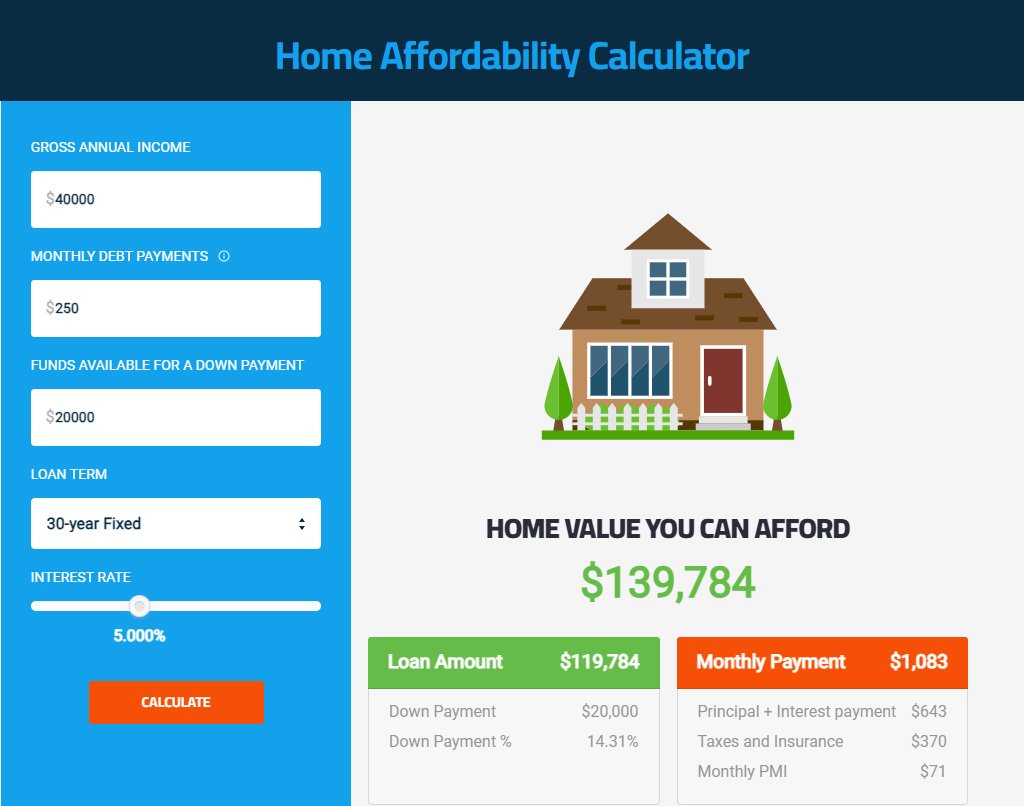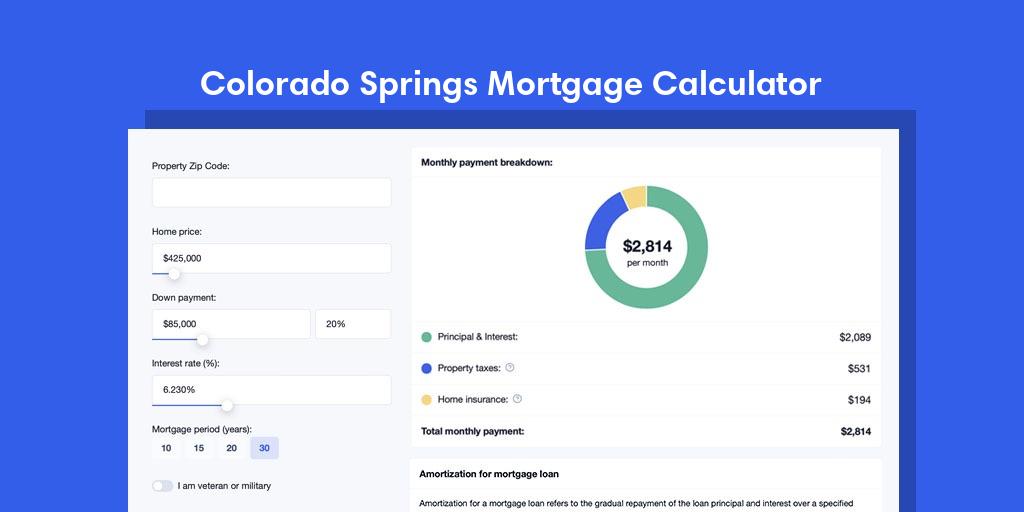
Mortgage calculators online are a starting point, not a decision tool.
I've watched more than a few people lock into a loan amount based on a free calculator, only to get a real quote later that was $40,000 to $60,000 lower than expected. The gap usually comes down to how these tools handle Colorado-specific variables, or don't handle them at all. Most generic calculators assume a flat 1.1 percent property tax rate nationally, which doesn't match Colorado well. Here we're looking at roughly 0.5 to 1.5 percent of assessed value depending on the county, plus the mill levy variations that change block by block. The other thing they consistently miss is how HOA dues factor into your debt-to-income ratio. A lender will include those monthly HOA payments in your DTI calculation if the community has mandatory assessments. That's not something most free calculators ask about, so the monthly payment you see on screen is often lower than what a lender will actually approve you for.
Free Mortgage Calculator Colorado
If you want something closer to reality, you need to account for a few things that change the output significantly. Property tax assessment in Colorado uses the actual market value divided by 7.15 percent, which is the statutory assessment rate for residential property. That means the taxable value is roughly 7.15 percent of what the home is worth, not the full sale price. A $500,000 home doesn't get taxed on $500,000. The mill levy then applies to that assessed value, and mill levies vary by municipality. Denver sits around 107 mills while some rural counties run higher or lower. Run the numbers with an effective tax rate of 0.7 to 1.2 percent of the purchase price and you'll land much closer to your actual annual tax bill. Second, Colorado has a conforming loan limit that differs from many other states. In 2024, the baseline conforming limit for most of Colorado is $766,550 for a single-unit property, but several high-cost counties like Eagle, Summit, and Pitkin have limits above $1,142,500. If you're buying in those areas and your loan exceeds the local conforming ceiling, you're looking at a jumbo loan with different rate structures and typically a 10 percent minimum down payment instead of the 3 to 5 percent you'd see on a conforming loan. Free calculators rarely flag this distinction, and jumping into a jumbo without knowing it upfront can delay your closing by weeks while the appraisal and underwriting process changes. I ran into this exact situation with a buyer last year. They were purchasing a condo in Aurora with an $82,000 annual HOA assessment, which breaks down to about $6,833 per month. Their calculator showed a comfortable payment at a $420,000 loan amount. When I pulled the numbers with the HOA factored into DTI, the approved loan amount dropped to $365,000. That's a fifty-five thousand dollar difference that came from one field the calculator never asked about. I just added a manual line for the HOA monthly cost and ran it through a different tool to confirm, then adjusted the purchase price target accordingly before they got pre-approved.
There's also the matter of Colorado's property tax circuit breaker, which caps annual property tax increases for long-term homeowners. That mostly affects refinancing decisions rather than purchases, but it's worth knowing if you're evaluating a home you plan to hold for fifteen years or more. Some calculators will project your tax increase at a flat annual rate, which ignores this cap entirely and can make older homes in established neighborhoods look more expensive than they actually will be over time. Down payment assistance programs are another Colorado-specific factor that most free calculators ignore. The Colorado Housing and Finance Authority runs multiple programs, including the CHFA Advantage loan with down payment help up to 3 percent of the purchase price, and the Homeownership Colorado program which provides a deferred second lien of up to $15,000. These programs have income limits that vary by household size and county. A calculator that doesn't factor in assistance will overstate the cash you need at closing, which can push some buyers out of the market prematurely because they think they can't afford the down payment when a program would cover a significant portion of it. The workaround for getting closer to a real number is straightforward. Take the free calculator result and then manually add or subtract these items: property tax at 0.9 percent of purchase price as a middle-ground estimate for most front-range counties, HOA dues if applicable, and whether you might qualify for a jumbo loan based on your county's conforming limit. Then take that adjusted monthly payment and call three local lenders for a Loan Estimate. That's the only document that matters for an actual purchase, and it will reflect your credit score, debt load, and the specific loan product you're considering. The calculator is useful for narrowing your price range before you start talking to lenders, but it is not a substitute for a real quote. The gap between the two is usually about 8 to 12 percent on the monthly payment side, and sometimes more if the property has unique tax or HOA characteristics.
Get the Full Details