Amortization Schedules: What They Actually Show and How to Get One That Works
I used to generate these by hand in Excel for every small business loan I reviewed. It took about 45 minutes per schedule, and more than once I caught a banker who'd copied the formula wrong and was charging the borrower an extra $200 a month for three years. The problem wasn't the math — it was the format. People kept printing tables that either cut off mid-loan or showed so many decimal places it looked fake. So here's what actually matters when you need a Free Printable Amortization Table, and where most free generators fail you.
How to Build a Free Printable Amortization Table That Doesn't Look Like Spreadsheet Output
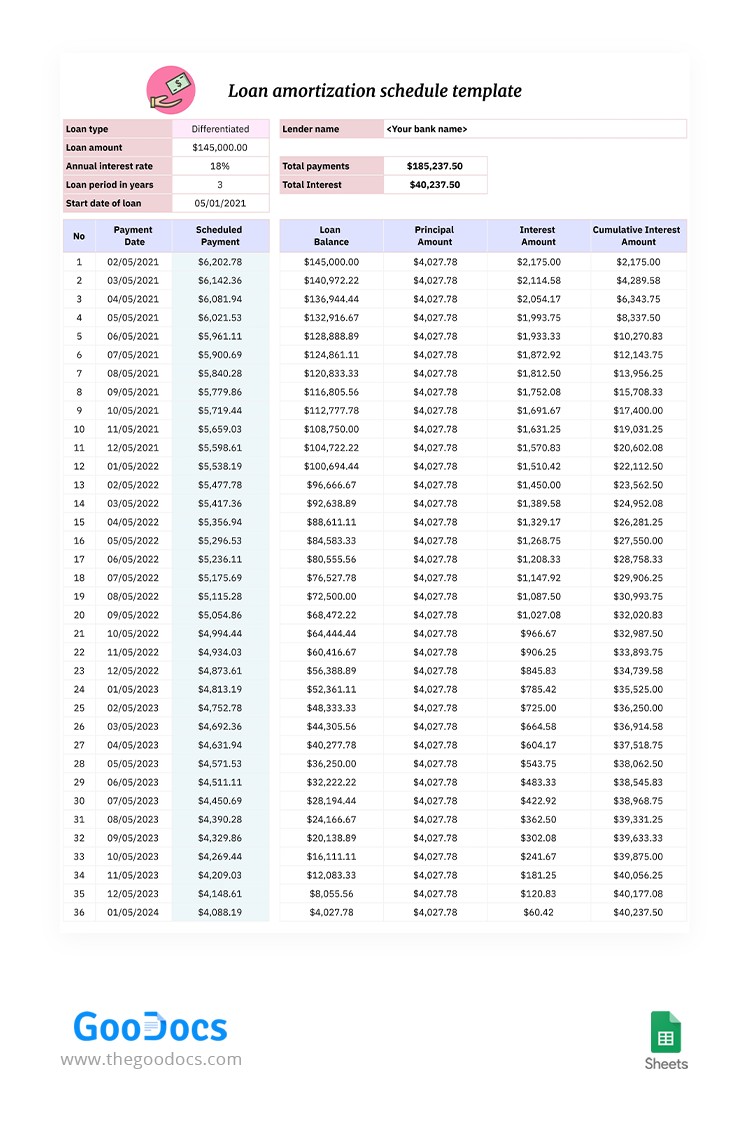
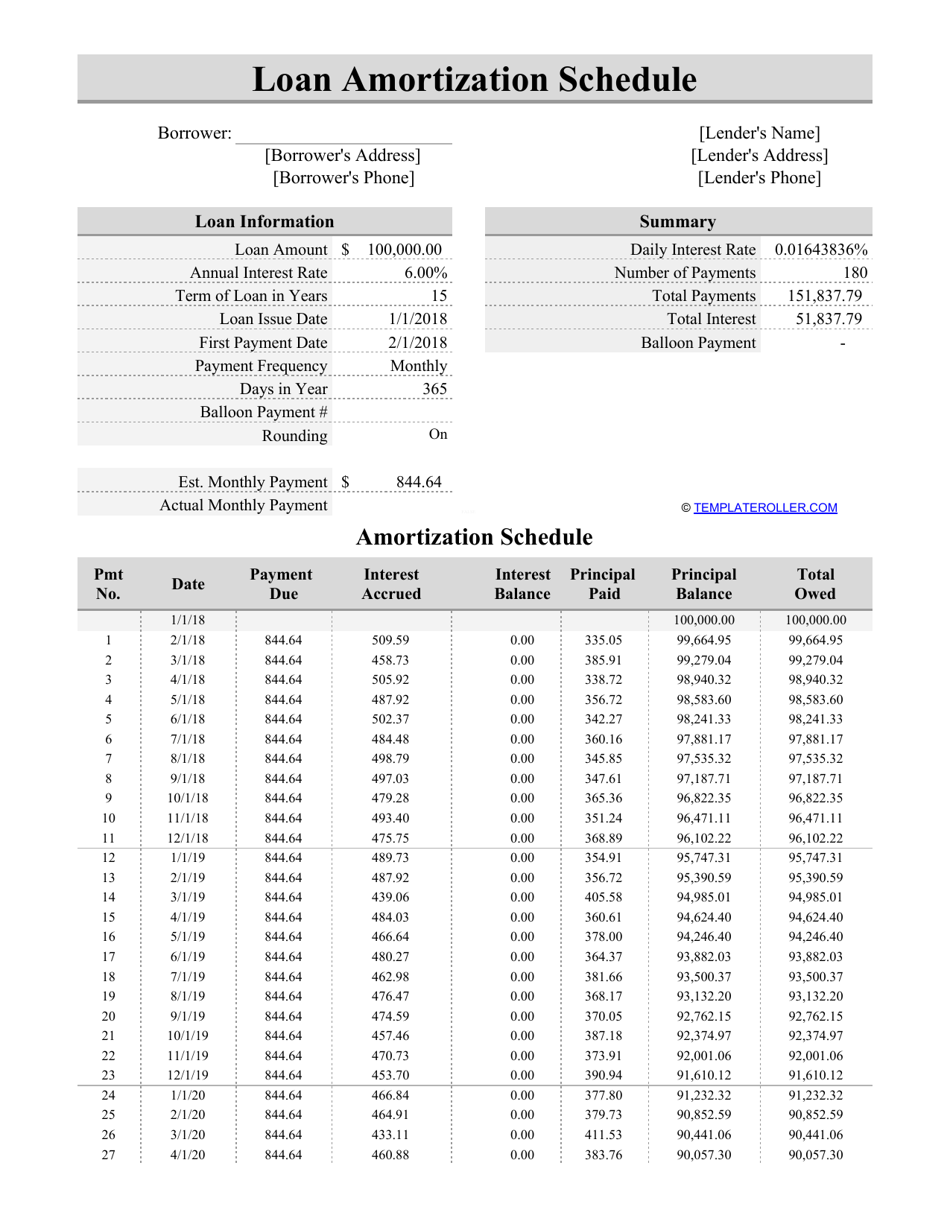
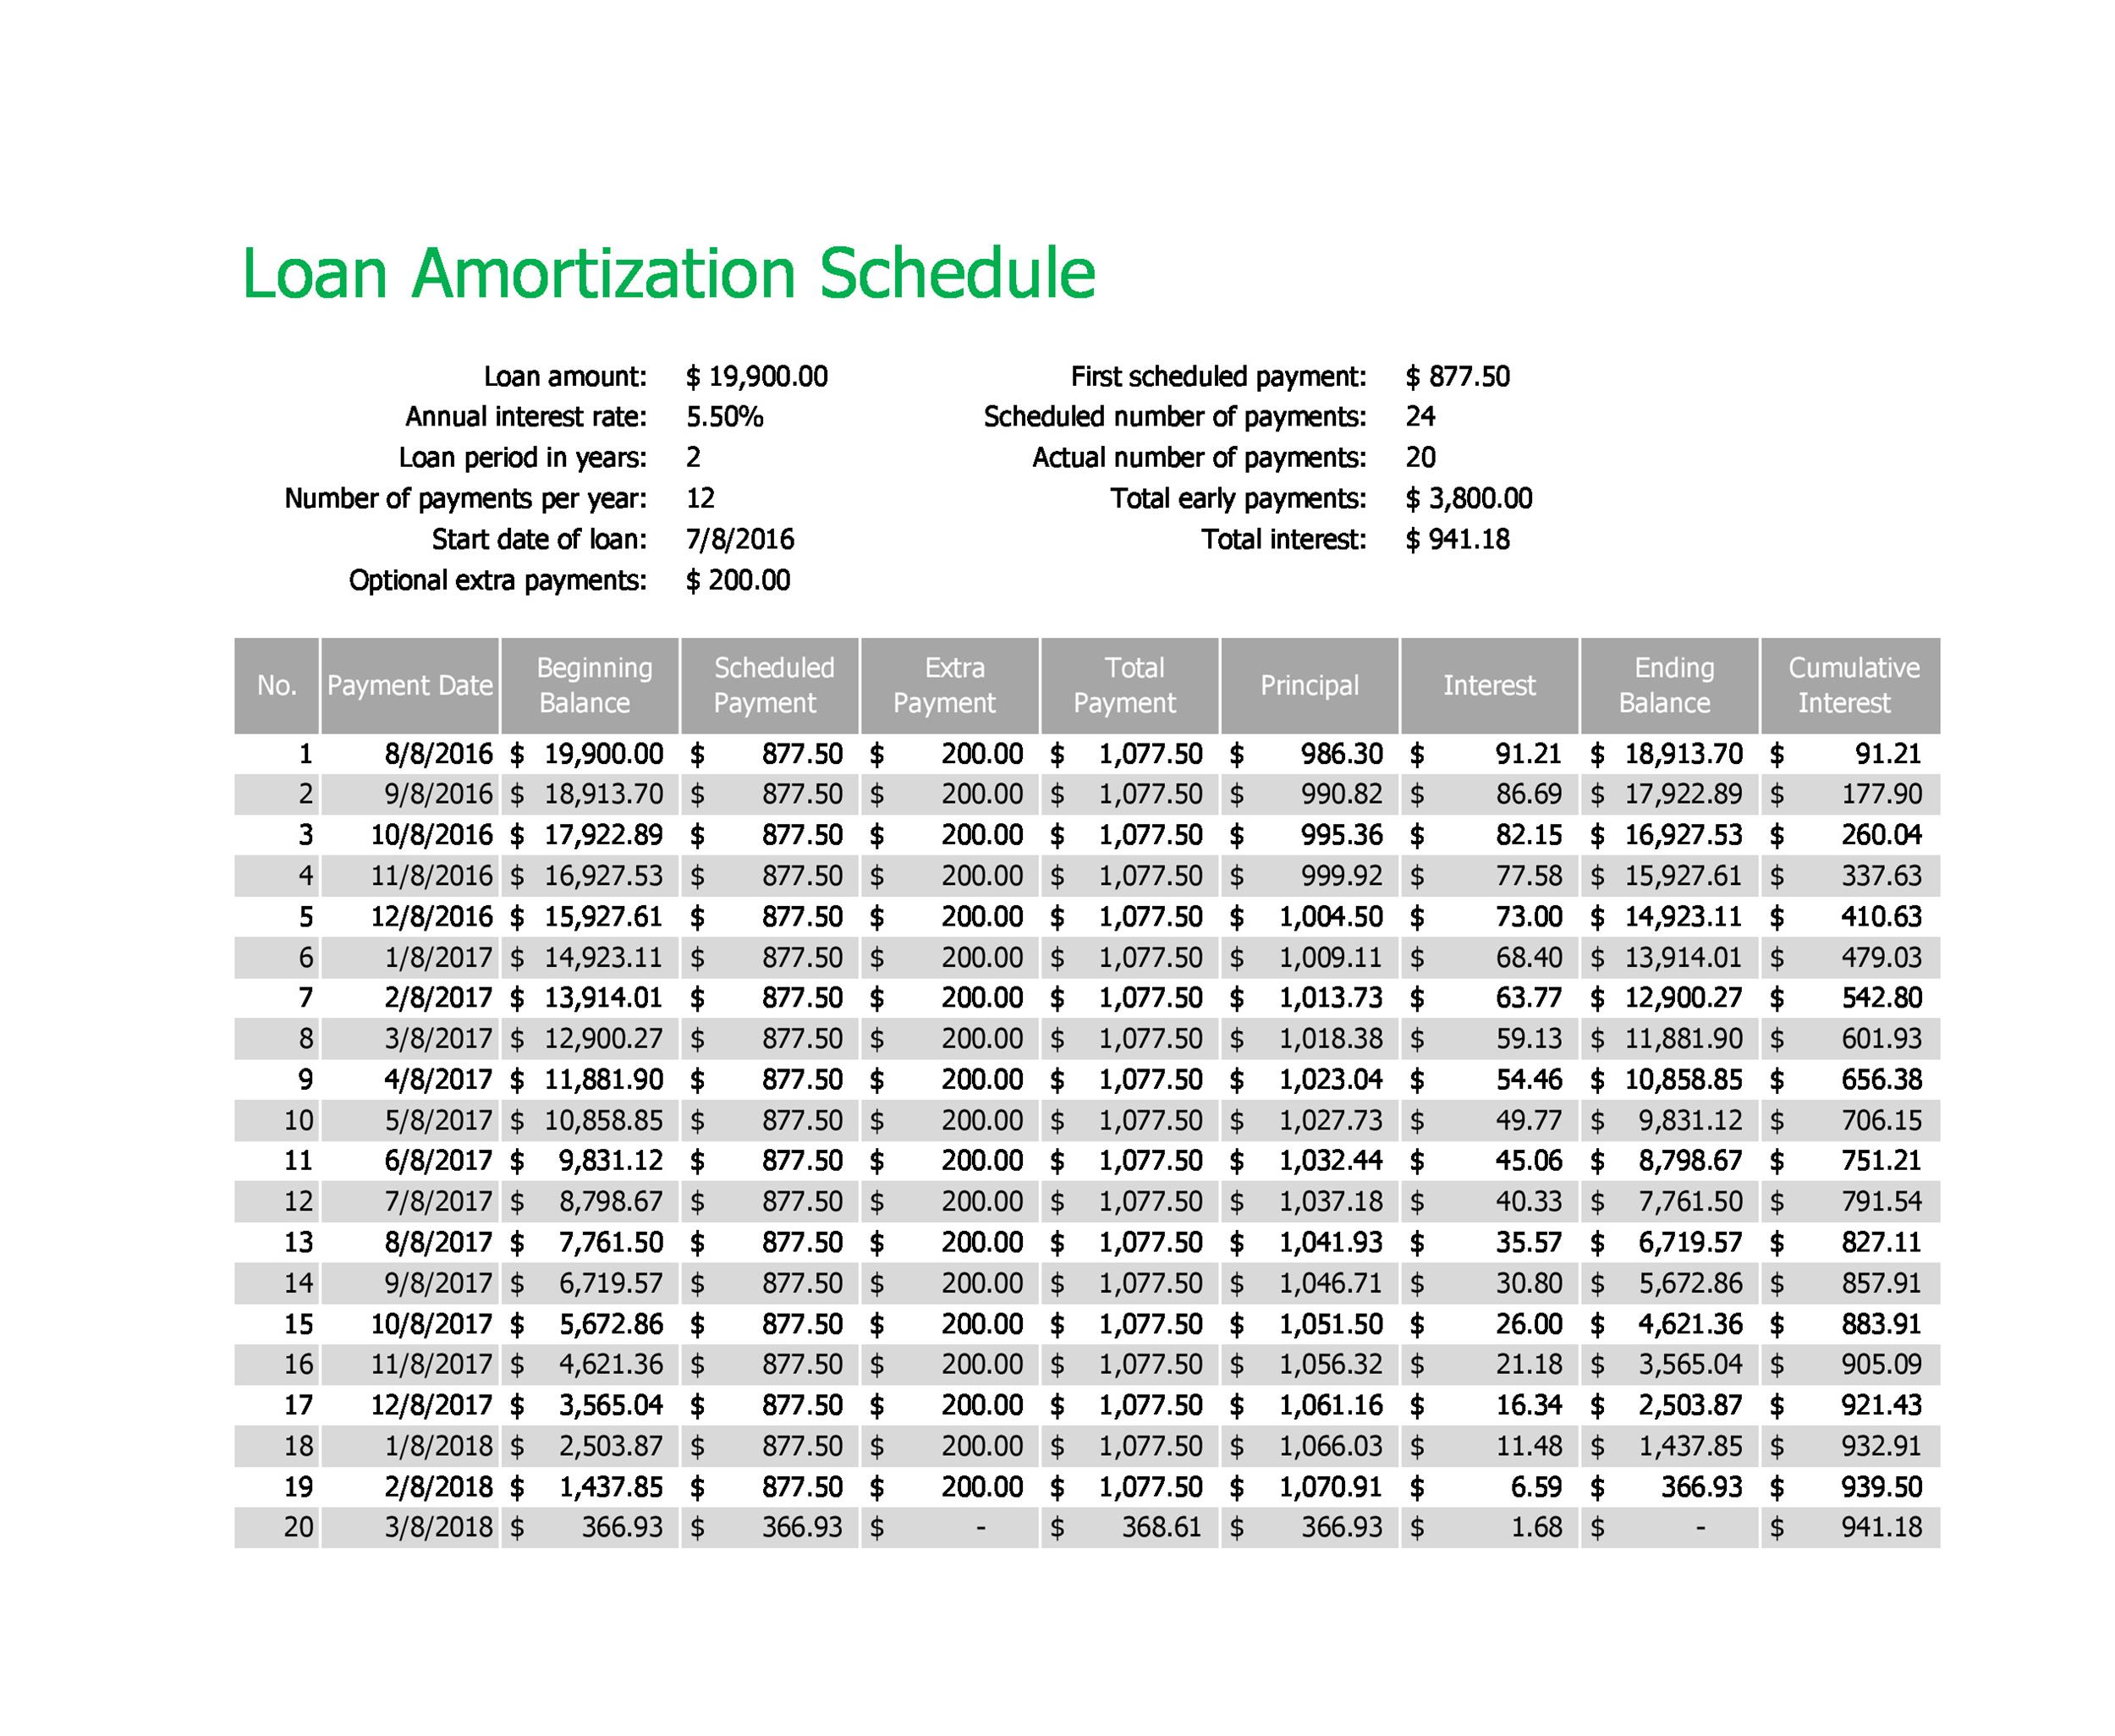
The core formula is straightforward. Monthly payment equals the principal times the monthly rate, divided by one minus one plus the monthly rate, all raised to the negative of the total number of payments. Most online calculators apply this correctly, but the ones you end up trusting are the ones that also let you customize what gets printed. A lot of free tools will give you the table but then bury the print button under a popup ad or force you through a sign-up wall. I found that about half the "free" amortization generators I tested either wanted my email address or stripped the last few rows when you switched to landscape mode. What I actually use now is a simple spreadsheet template I built after the first bad copy caught. The columns are payment number, date, beginning balance, payment amount, principal portion, interest portion, and ending balance. The first row has your loan terms as plain inputs at the top so anyone looking at the printout can see at a glance what rate and term it's based on. The formula chain is unbroken through every row. When I need to submit one to a client or a lender, this is what goes into the PDF.
Where Free Printable Amortization Table Tools Fall Apart
The biggest issue I ran into repeatedly is rounding. Standard generators round the interest portion of each payment to two decimal places, then carry that rounded figure forward. Over 360 months that creates a drift of maybe $0.30 to $1.50 depending on the loan size. Not enough to cause a problem in practice, but enough that if you're using the schedule for dispute resolution or audit purposes, the final payment won't zero out cleanly. The workaround is simple: set the last row's principal as the remaining balance instead of calculating it from the rounded interest figure. That last payment might be a few cents different from what the formula would give you, but it matches what the borrower actually owes. A second problem is payment date handling. Most free tools assume a fixed day of the month for every payment. Real loans don't always work that way. I had a situation where a borrower made their first payment 18 days into the period instead of 30, and the standard schedule showed every subsequent payment as if nothing had changed. You need a schedule that either flags the odd first period or lets you input exact dates. The spreadsheets I trust allow date input per row rather than assuming uniform intervals.
Get the Full Details
What to Check Before You Print
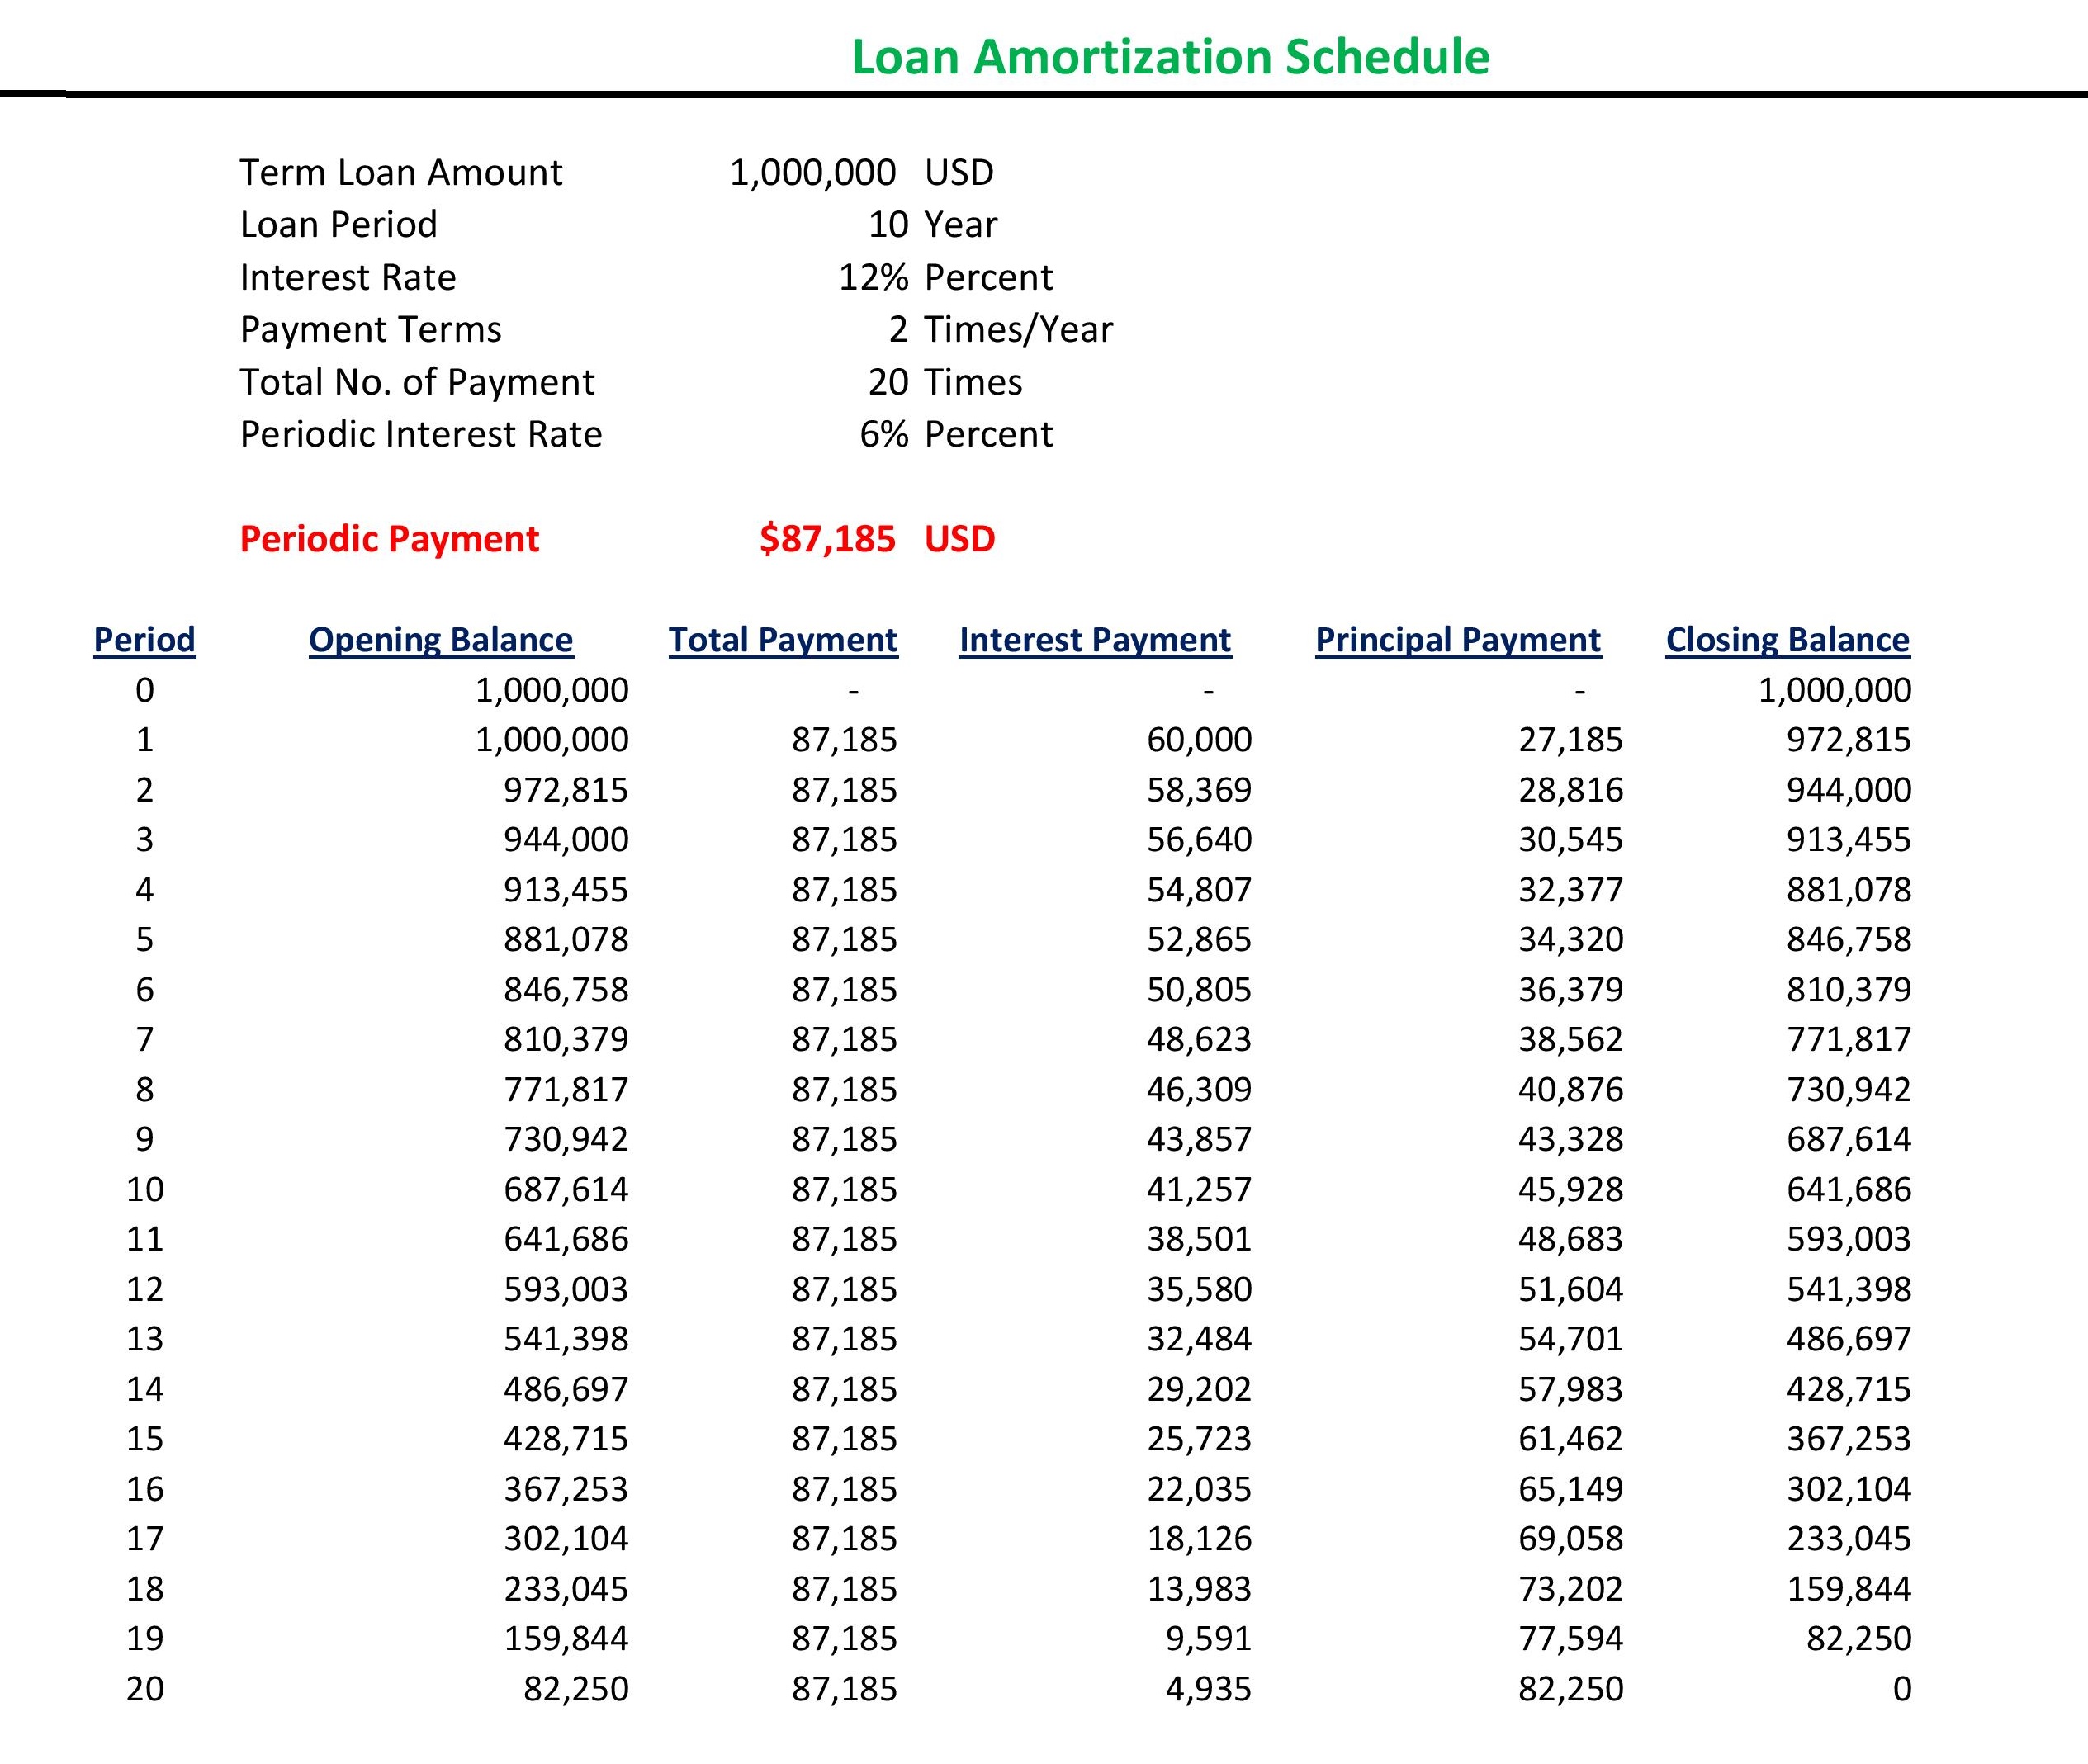
Make sure the schedule shows the payoff date explicitly. A lot of free generators list 360 rows but never state that row 360 lands on a specific calendar date. If you're working with a borrower who needs to prove when the loan ends for tax or refinance purposes, missing that detail will cost you time. Also verify the total interest column sums correctly. I've seen schedules where the "total interest paid" line at the bottom didn't match the sum of the interest column because someone accidentally excluded the first or last row from the calculation. Print in landscape orientation if the loan term exceeds 180 months. Portrait cuts columns too narrow and makes the principal and interest portions unreadable without magnifying glass. The standard letter-size landscape fit gives you about seven columns at a readable width. Anything wider than that starts compressing the numbers to two decimal places, which loops back to the rounding problem I mentioned above.
A Quick Downloadable Template
If you need something reliable right now, the approach I described works in any spreadsheet application. Set up the input cells at the top with principal, annual rate, and term in months. Build the payment formula once, then drag it down. Format the currency columns to two decimal places. Add a sum row at the bottom for total principal, total interest, and total payments. Test it against a known figure — a $100,000 loan at 6% over 360 months should produce a monthly payment of approximately $599.55. If your number is off by more than a dollar, check the rate division. Annual rate divided by 12 is the monthly rate; some generators mistakenly divide by 365 and then multiply by 30, which introduces tiny but compounding errors. The Free Printable Amortization Table you end up using regularly will probably look like this: clean inputs at the top, the table filling the page, totals at the bottom, and a single page count that doesn't require scrolling to find the payoff balance. That's the whole point. You print it once, you file it, and you know it's correct because you checked the last row yourself.
Edge Case: Balloon Payments
Most free generators assume a fully amortizing loan. They'll break silently if you try to input a balloon payment or a shorter term with a larger monthly figure. I had a commercial loan where the borrower paid a reduced amount for 60 months and then owed the remaining balance in one shot. The standard schedule showed zero remaining balance at month 60 because it recalculated the payment to match the full amortization. The workaround is to build two sections in the same spreadsheet: the regular payment rows, then a final row where the principal column equals the remaining balance and the payment column is whatever that balance plus the accrued interest comes to. Label it clearly as a balloon adjustment so anyone reading the printout understands why the final row looks different. I know that sounds excessive for a simple loan schedule, but here's the thing: generated tables are a black box. You trust the tool to apply the right formula, but you can't see where it went wrong unless you understand the structure. A spreadsheet you built yourself is transparent. Every cell has a label, every formula is visible, and if the lender asks you to explain a discrepancy you can point to the exact cell. That transparency matters more than the convenience of clicking a button and getting a PDF. The time investment is real. Setting up the template takes about 15 minutes the first time. After that, generating a new schedule for a different loan takes roughly three minutes: change the inputs, drag the formula down, verify the totals. Compared to hunting through five different generator websites, signing up for accounts, and dealing with popup ads, it's faster than most people expect and infinitely more reliable.