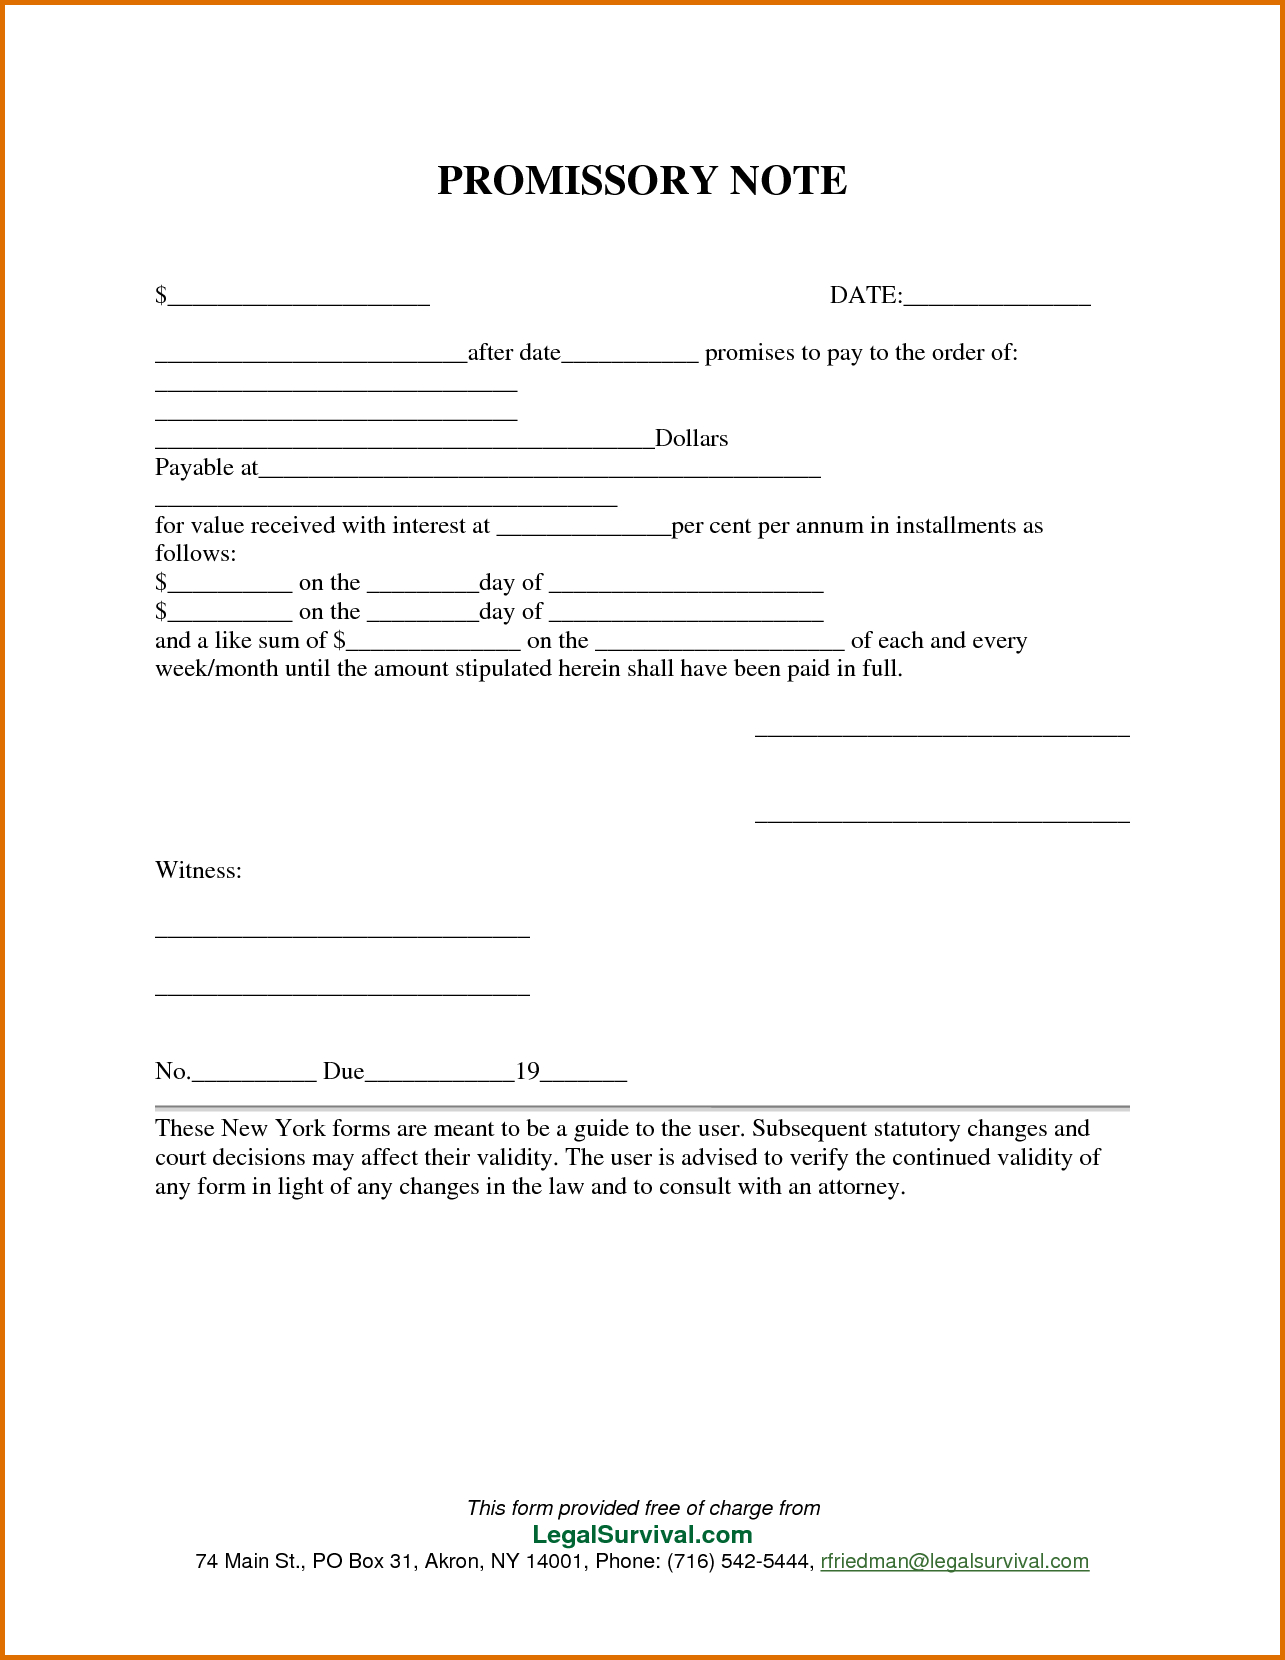
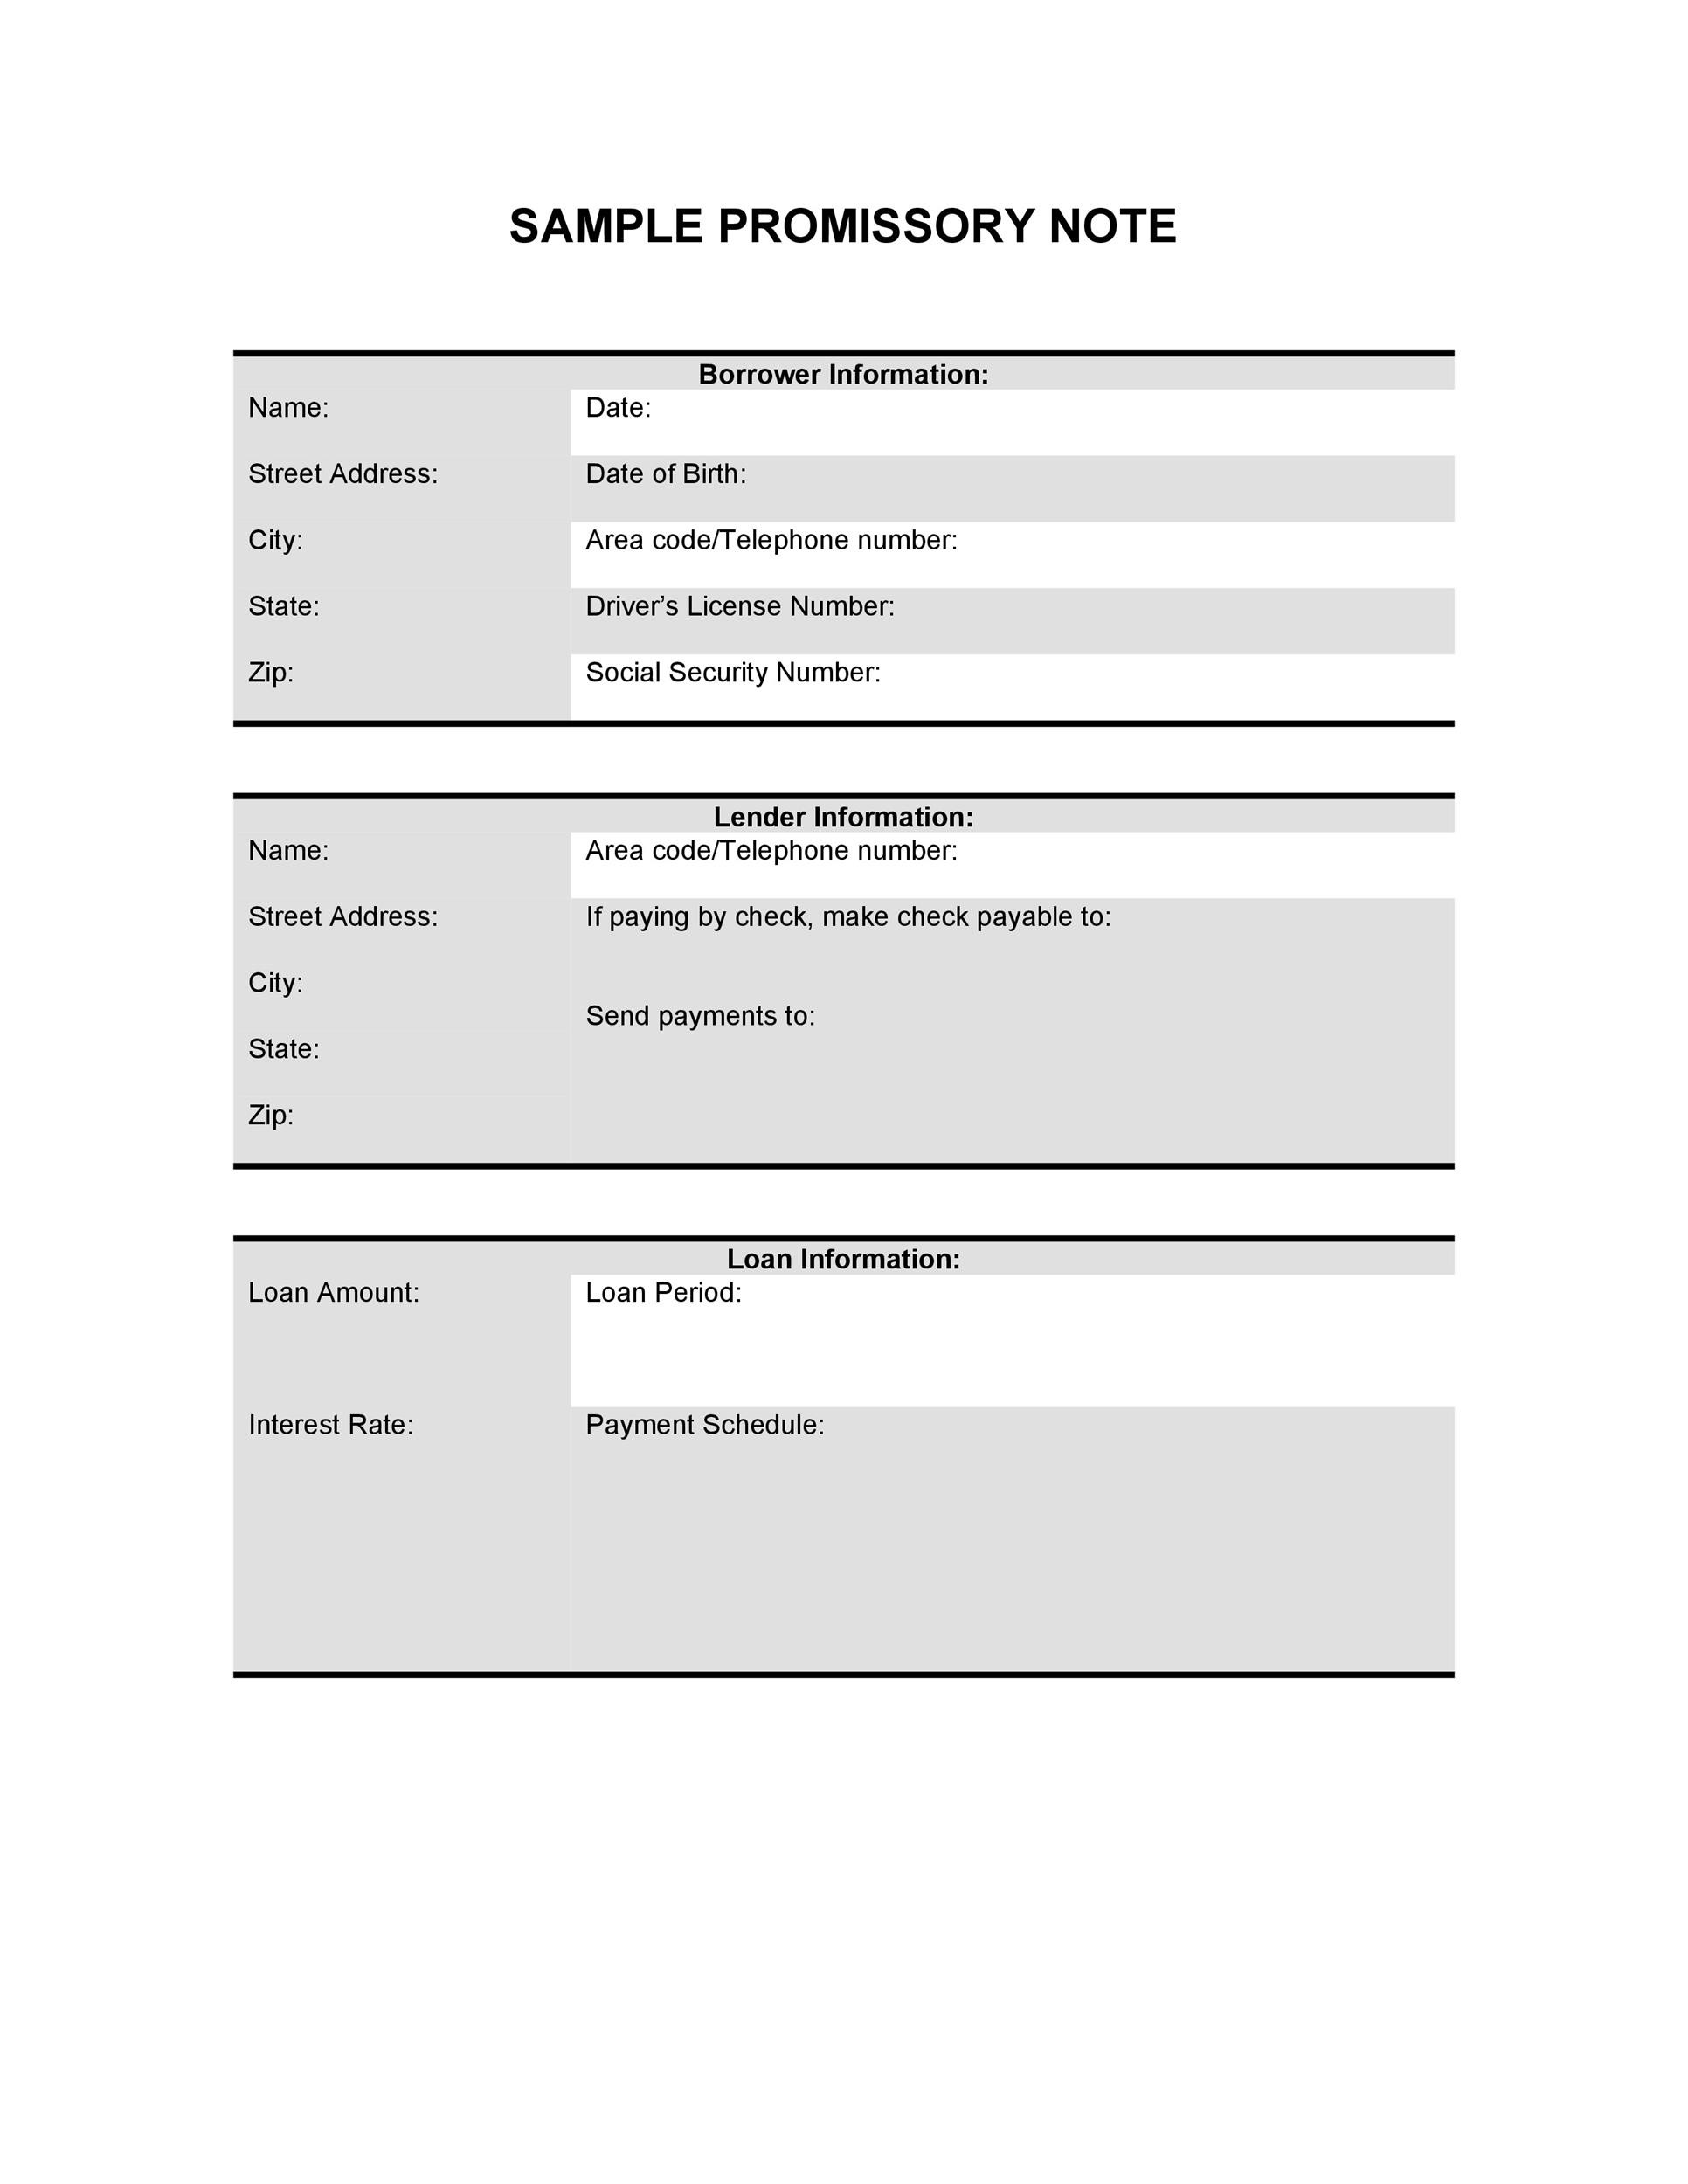
What a Free Promissory Note Template Actually Is
A promissory note is just a written promise to pay a specific sum of money back under defined terms. It's a legally enforceable IOU with teeth. When you search for a Free Promissory Note Template, what you're looking for is a document that lays out the borrower's obligation clearly enough that neither party can later squirm out of the terms. Most free templates you find online are either too generic to be useful or missing clauses that matter once things go sideways. I've filled out enough of these that I've learned which sections to actually pay attention to and which are just paperweight. The basic structure includes the parties involved, the principal amount, the interest rate if any, the repayment schedule, late fees, and what constitutes default. That's the skeleton. The real differences between a template that holds up and one that doesn't come down to jurisdiction-specific language and whether it accounts for things like prepayment penalties, acceleration clauses, and collateral descriptions.
How to Use a Free Promissory Note Template Properly
Start by filling in the core terms exactly as agreed between the two parties. Principal amount. Interest rate. Repayment start date and frequency. The tricky part is usually the default clause and the governing law section. I made the mistake once of using a template from a different state than where both parties lived, and when I tried to enforce it through small claims, the judge flagged the jurisdiction mismatch and asked me to amend it. Took an extra three weeks I didn't have. Since then I always check the governing law line before I even start typing. Another thing people skip is the signature block formatting. Some free templates just have a single line for each party. What you actually need is space for printed name, signature, date, and ideally a notary acknowledgment line. Even if notarization isn't required in your state, having it done costs about twenty dollars and makes the document substantially harder to challenge later on the grounds of forged signature or duress. I keep a mobile notary card in my desk drawer specifically for this reason. Once the fields are filled, review every clause with both parties before anyone signs. Not after. I learned that the hard way when a friend's brother signed a note for a $5000 loan, and three months later claimed he didn't understand the prepayment terms because they were buried in a footnote. We ended up renegotiating the note entirely instead of fighting it in court. That cost more in time than a proper review would have.
Common Problems with Free Templates
The biggest issue is that most free versions are written for personal loans between individuals. If you're doing anything business-related, or the amount exceeds a few thousand dollars, you need something more robust. A lot of templates also don't include usury compliance language, which means if the interest rate you set violates your state's maximum, the entire note could be unenforceable or at minimum reduced to the legal rate by a court. I had a case where a template had an annual percentage rate of eighteen percent and the state cap was fourteen. The lender thought they were securing extra interest. They weren't. The court just slashed it and moved on. Another problem is the lack of an acceleration clause. Without one, if the borrower misses a payment, you can't demand the full remaining balance upfront. You're stuck chasing individual missed payments. That's a slow grind that eats into collections energy. Make sure the template you're using has clear acceleration language, and that it's worded to trigger after a specific number of missed payments rather than immediately on the first one. Immediate acceleration on a single late payment looks punitive and can be challenged.
Get the Full Details
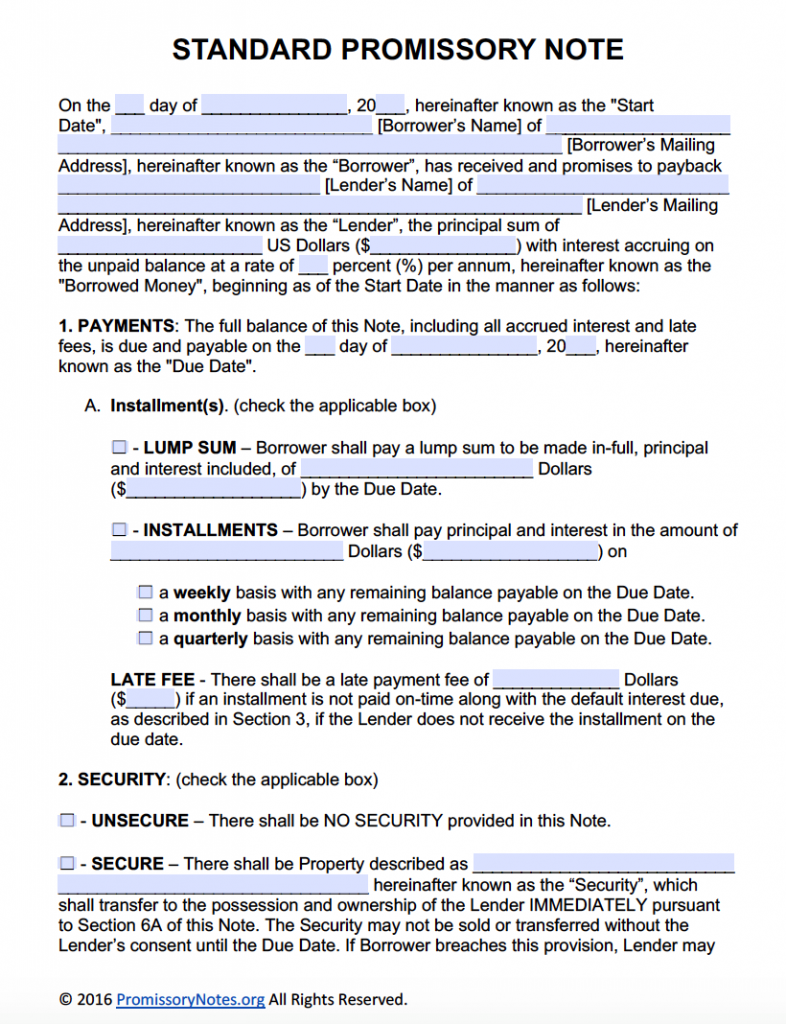
When to Walk Away From a Free Template
If the loan is over twenty-five thousand dollars, involves collateral, or spans multiple jurisdictions, a free template isn't worth the risk. The cost of a properly drafted note from a legal service or attorney is usually between one hundred and three hundred dollars. The cost of finding out it's flawed after default happens is significantly higher. I once saw someone try to enforce a free template note for a twelve thousand dollar equipment loan where the collateral description was vague enough that the court dismissed the security interest. The principal was still owed, but they lost their priority position in repayment. That note could have cost fifty dollars to do right. For smaller personal loans between family members or close acquaintances, a solid free template works fine. Just make sure you customize the governing law, interest rate, and default provisions to your situation. Don't leave placeholders filled with generic language like "interest shall accrue at a reasonable rate." Courts don't like reasonable. They like specific numbers.
Where to Find a Free Promissory Note Template
There are a few decent sources. LawDepot and Nolo both have free versions that are at least structurally sound, though you'll want to customize the details. Your state's court website sometimes offers approved forms, which is the safest bet if they exist. The key is not assuming that just because it's free, it's inadequate for your needs. Check the clause list against what I mentioned above, fill in the specifics, get it notarized if possible, and both parties should keep a signed original. That's really all there is to it.