How Seller Financing Actually Works When You Throw a Balloon Into the Mix
Seller financing is when the property owner acts as the bank. Instead of walking into a credit union or dealing with a mortgage broker, the buyer signs an agreement directly with the seller and makes payments over time. It's straightforward enough until someone introduces a balloon payment, which is where things get messy quick. A balloon payment is a large lump sum due at a specific point during the loan—usually after three to seven years of regular payments. The idea is that the buyer refinances or sells the property to cover it. In theory this works. In practice it falls apart more often than people admit.
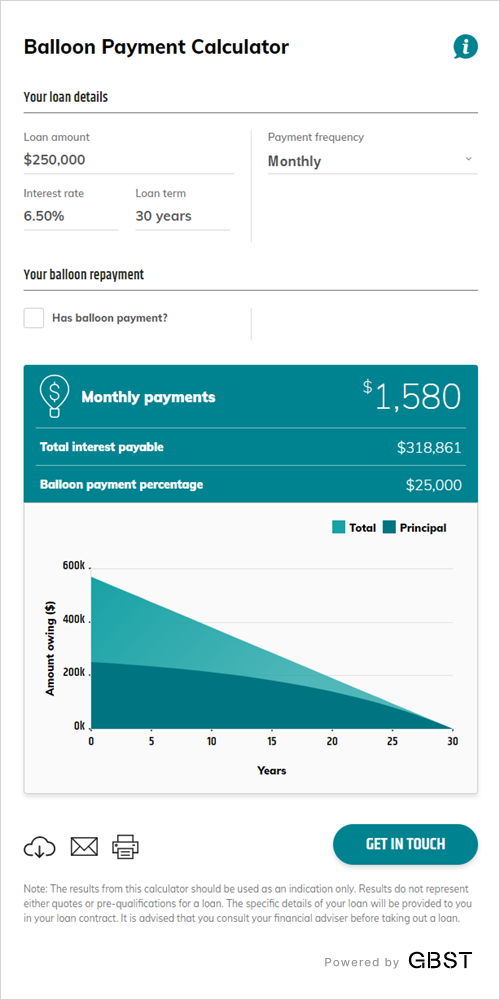
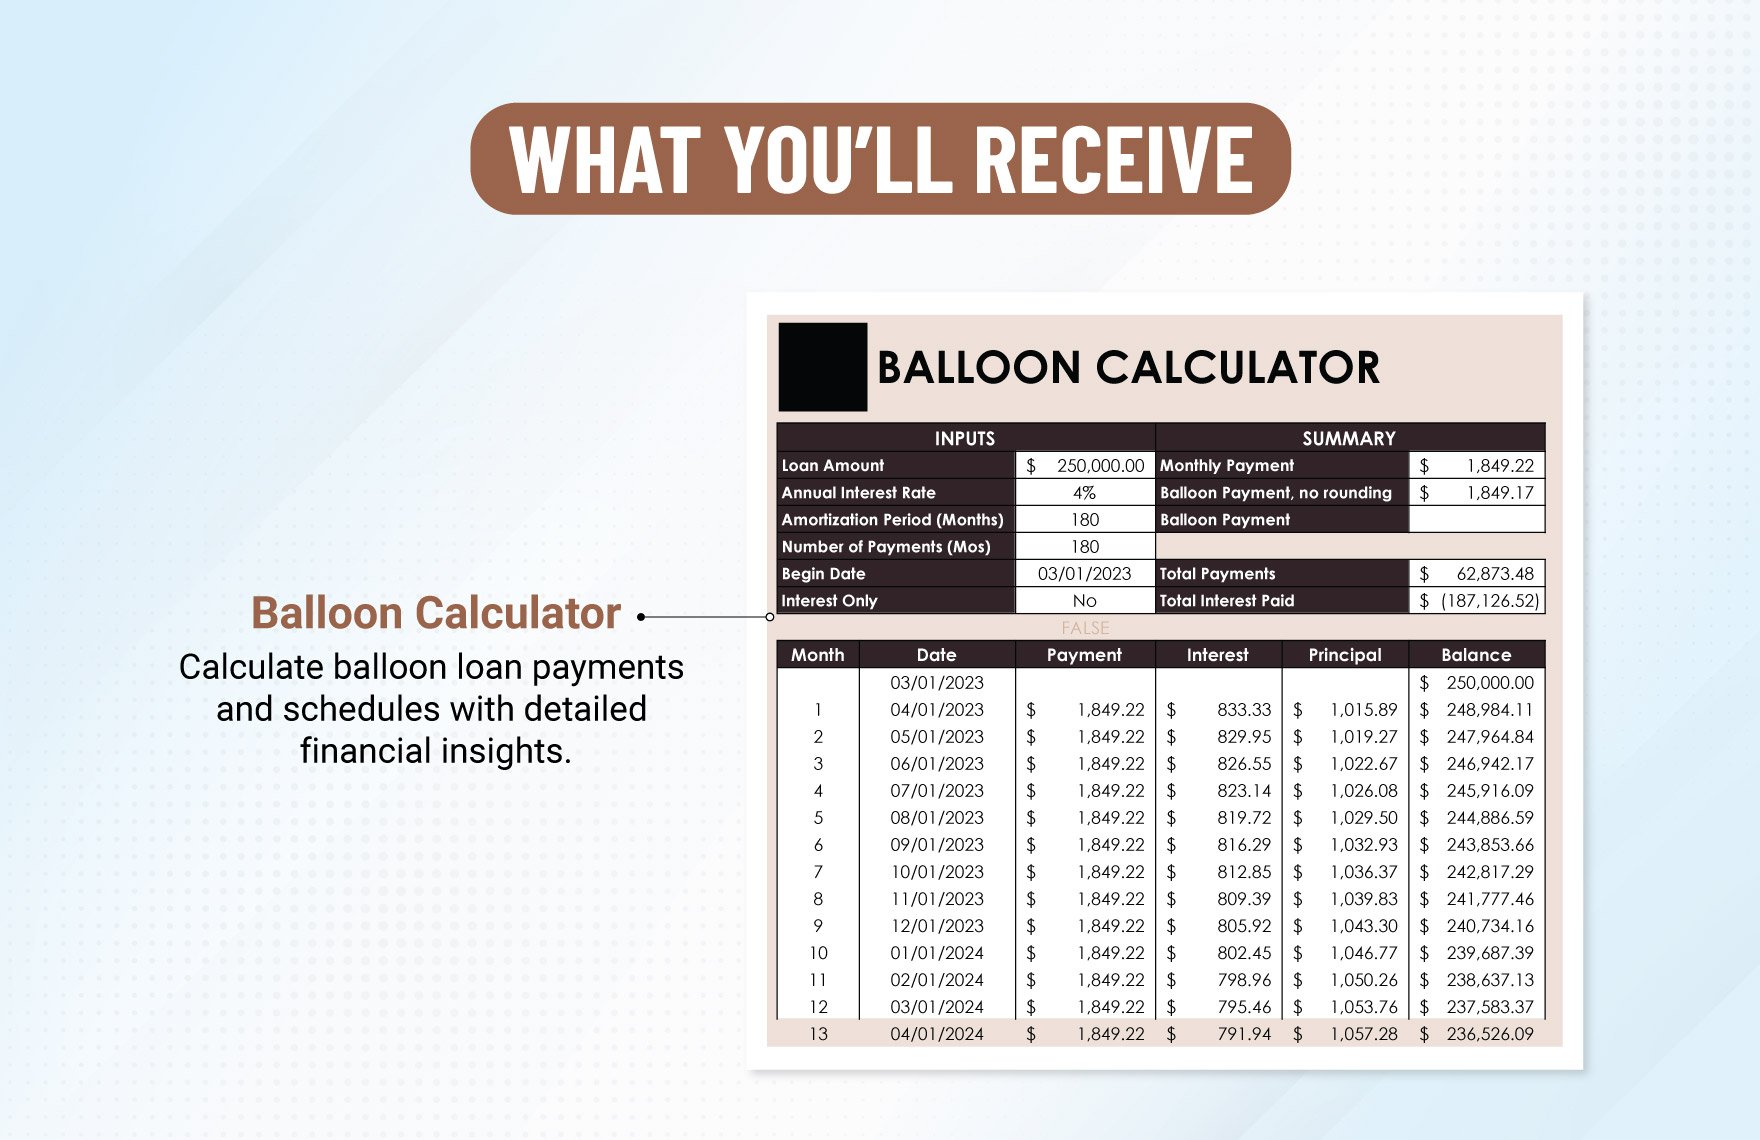
How to Use a Free Seller Financing Calculator With Balloon Payment
The mechanics are simpler than most sellers realize. You need five numbers, and most free calculators will ask for all of them upfront: 1. Purchase price — the agreed sale amount, not what the house was listed for or what the appraisal says. 2. Down payment — typically 20 to 40 percent in seller-financed deals because the seller is taking on risk that a bank would never touch.
3. Interest rate — this is your call as the seller. Most people start around 6 to 9 percent, but check local rates and what you could earn elsewhere before committing. 4. Amortization period — how long the loan would theoretically take to pay off. Fourteen years, twenty years, whatever. This determines your monthly payment size. 5. Balloon date — when the large final payment is due. Most common terms are three, five, or seven years, and this is where your calculator needs to compute a remaining balance that isn't zero.
Get the Full Details

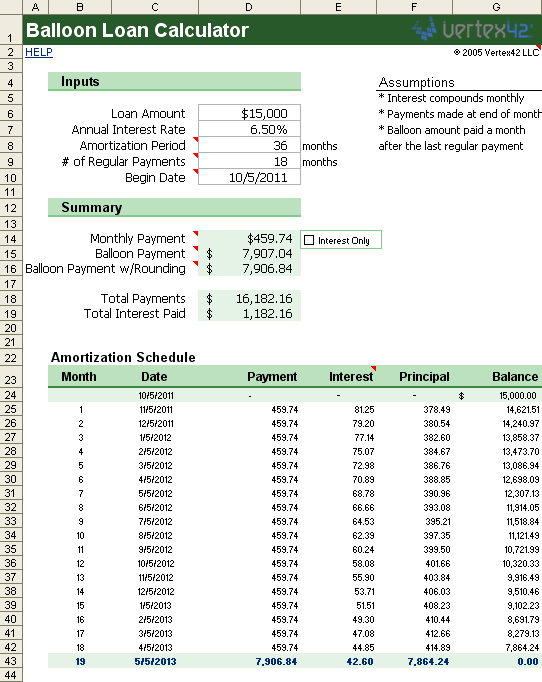
Plug those in and the calculator tells you two things: your monthly payment based on the full amortization schedule, and what the balloon balance will look like when the term hits. That second number is usually the most important one because it determines whether the buyer can actually pay you or whether you're stuck with a property dispute. I use a basic spreadsheet now instead of any online calculator. The free ones out there tend to handle the math correctly, but they rarely show you what happens when payments are late, when the buyer skips a month, or when the interest rate is adjustable. One specific calculator I kept running into gave wrong balloon figures because it rounded the monthly payment before calculating the remaining balance. The difference looked small at first—like fifty dollars here and there—but compounded across thirty-six payments and it added up to over two thousand dollars in errors. I switched to building my own and locked the decimal precision so the balloon number never drifts.
Things People Miss About Balloon Payments
The biggest misconception is that the balloon balance is just whatever's left after the payments. It's not. Because amortization is calculated over the full term, the remaining balance at the balloon date is often significantly higher than sellers expect. If you set a five-year balloon on a fifteen-year amortization, the buyer will have paid down maybe fifteen to twenty percent of the principal. That means a sixty thousand dollar loan could still carry a forty-eight thousand dollar balloon. Make sure your calculator shows that clearly, not buried in fine print. Another thing nobody warns you about: the tax implications. When a seller finances a deal with a balloon, the IRS views the unpaid balance as part of the sale proceeds, and depending on how the note is structured, you might be able to spread capital gains recognition over the life of the loan using the installment method. But if the balloon is too aggressive or the payment schedule looks disguised, the IRS can reclassify it. Talk to a CPA before you finalize terms, especially if the balloon is larger than twenty-five percent of the selling price. That threshold tends to trigger closer scrutiny. Here's a practical example. I worked through a transaction last year where the seller wanted a forty-five thousand dollar balloon at year three on a hundred and twenty thousand dollar property with fifteen percent down and eight percent interest amortized over twenty years. The monthly payment came to about seven hundred and ten dollars. After thirty-six payments the remaining balance sat around thirty-eight thousand. The buyer refinanced through a credit union at the balloon date and paid it off without issue. The whole process from calculator to closing took about six weeks. Not bad, but only because we double-checked the balloon number three different ways before anyone signed anything.
When This Approach Breaks Down
Seller financing with a balloon is not a universal solution. It fails most often when the buyer's income is unstable or when the property type makes refinancing difficult. A single-family home in a stable market can usually be refinanced within a few years. A mobile home, a commercial unit in a declining area, or a property that needs major repairs—those become nightmares because no traditional lender will touch them when the balloon hits. The biggest bottleneck is the refinance assumption. You're not really getting paid back by the monthly payments. You're getting paid back when the balloon comes due and the buyer either pays you or walks away. If they walk away, you've lost the buyer, the property is yours again, and you've spent years collecting payments that barely covered your carrying costs and interest. That scenario played out for a friend of mine who financed a triplex. The buyer stopped paying at month twenty-eight, claimed he couldn't refinance, and walked. The property had been sitting vacant for nine months by the time I helped him work through the foreclosure process. He ended up recovering about sixty percent of what he was owed after legal fees. Because of that risk, I always recommend requiring a larger down payment—closer to thirty percent if possible—and structuring the balloon no earlier than year five unless the buyer has documented refinancing capability. Some sellers also add a prepayment penalty clause to the note so the buyer can't just pay off early and leave you short if the deal was structured around the interest income. That's not a popular move with buyers, but it protects you if you're counting on that yield.

What to Look for in a Calculator
Not every free tool does balloon calculations correctly. Some divide the balloon amount by the remaining term and call it a monthly payment, which is wrong. The correct method calculates the amortizing monthly payment first, then applies it against the principal until the balloon date, leaving whatever balance remains as the lump sum due. If a calculator doesn't show both the monthly payment and the final balloon balance separately, it's probably not doing the math right. A good calculator will also let you adjust the amortization period independently from the balloon term. Those two numbers should never be forced to be the same. If your balloon is set for year five but the amortization is fifteen years, the calculator needs to reflect that gap clearly in the results. Anything that ties them together automatically is giving you a simplified answer that won't match your actual note. My working checklist before I run any numbers: purchase price minus down payment gives the loan amount. Loan amount times the monthly interest rate divided by one minus that result raised to the negative power of total payments gives the monthly. Then I take the remaining balance at the balloon date by running the same formula backwards for the remaining term. The result should match whatever the calculator shows, give or take a dollar from rounding. If it doesn't, I don't use it.