Understanding How Front And Back End DTI Calculators Actually Work
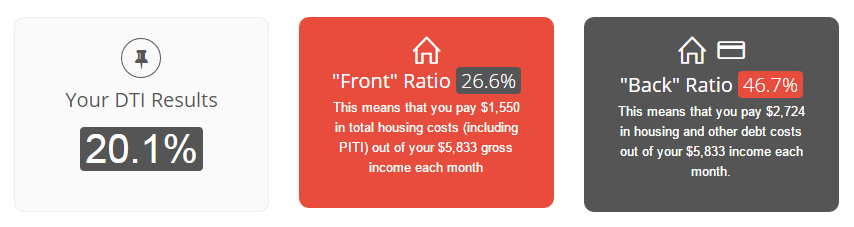
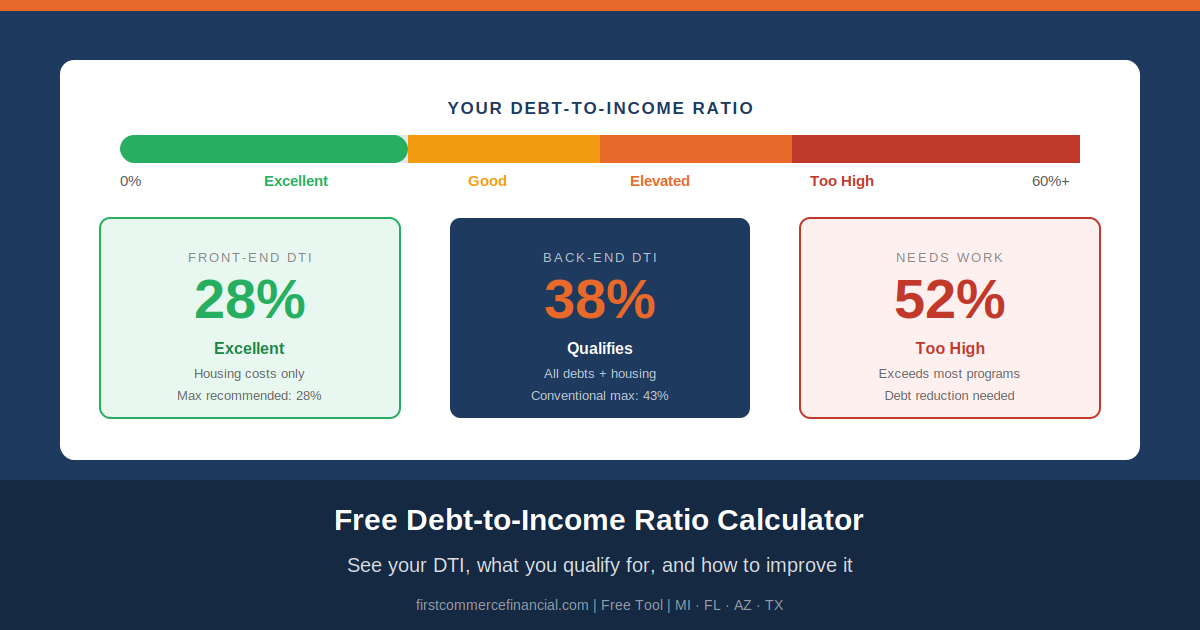
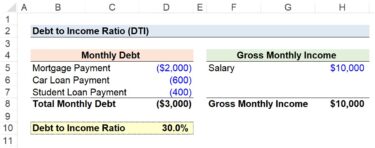
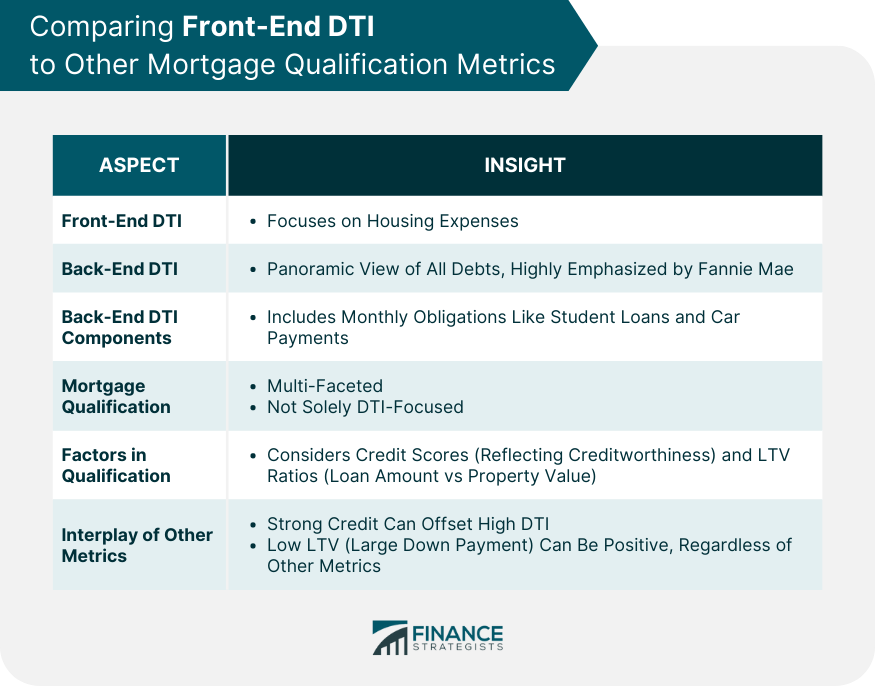
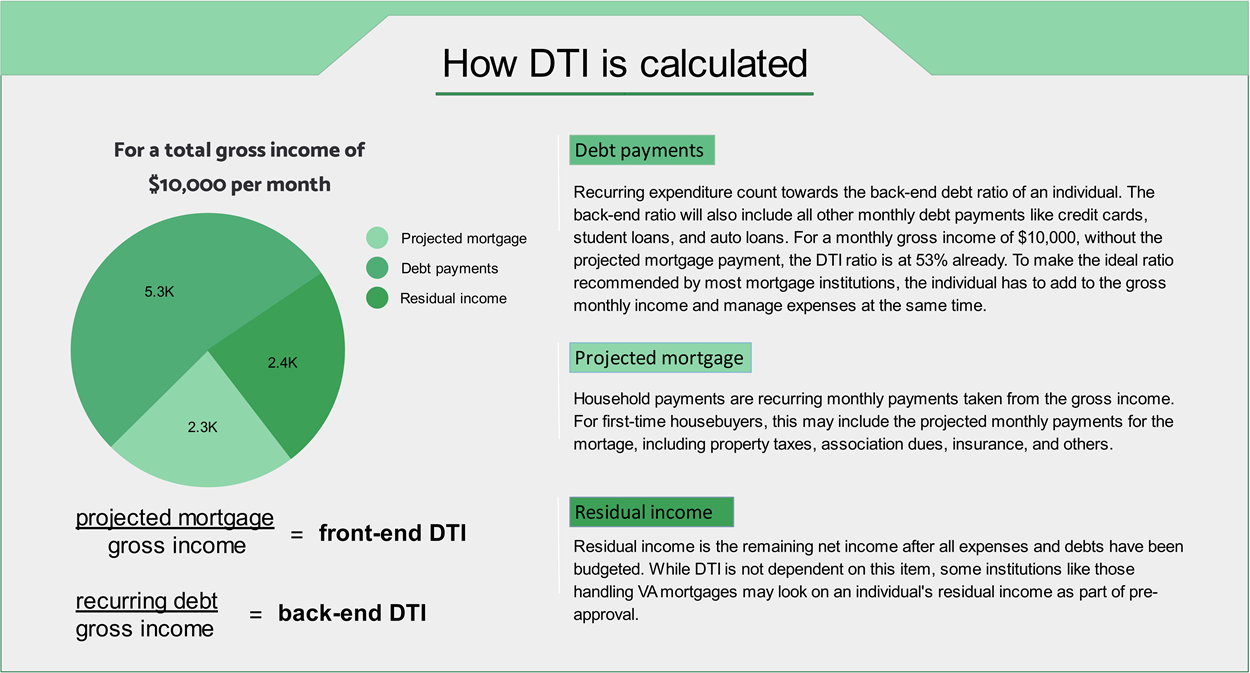
Most people think a DTI calculator just divides one number by another and spits out a percentage. It does that, but the devil is in the details, and the details are where almost every online tool gets things wrong. I built my first DTI calculator around 2014 for a small mortgage brokerage, and honestly the hardest part wasn't the math, it was deciding what to include and what to exclude. A front-end DTI looks at housing expenses only, principal, interest, taxes, insurance, and sometimes HOA fees, divided by gross monthly income. A back-end DTI adds everything else, credit cards, car payments, student loans, child support, minimums on revolving accounts. Both numbers get compared against lender thresholds, usually 28 percent for front-end and 36 percent for back-end in conventional lending, though some programs go up to 45 or 50 percent.Building Your Own Front And Back End Dti Calculator
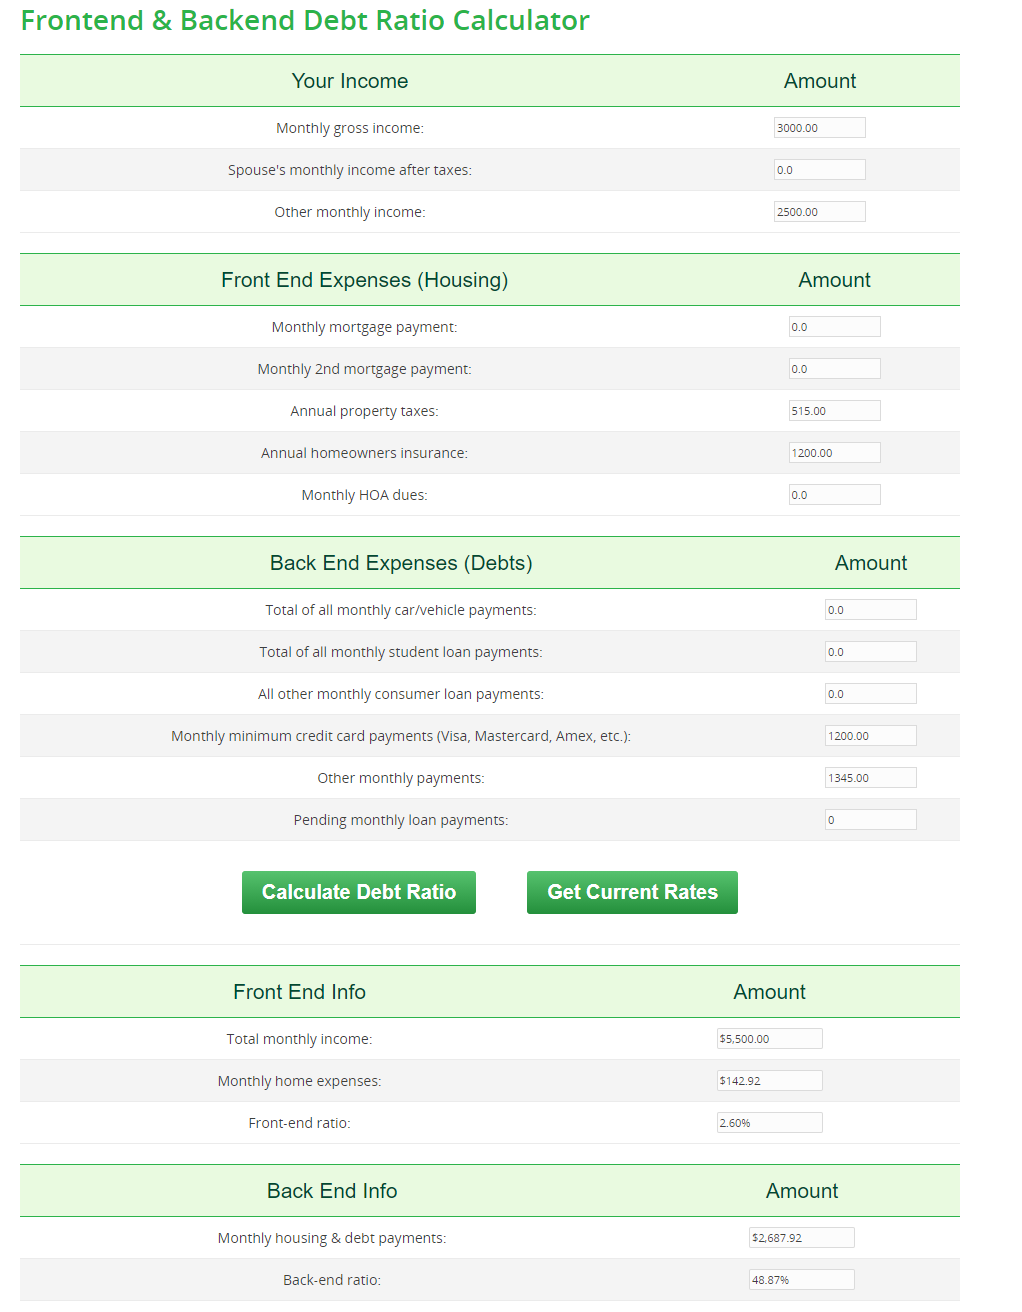
I started with a simple spreadsheet because the requirements kept shifting. Clients would bring in bonus income, self-employment earnings, or alimony, and the calculator had to handle each case differently. A hardcoded approach falls apart fast. The real implementation needs decision logic for which income types to count and which debts to include at full balance versus the minimum monthly payment. Here is the structure I settled on. The calculator should accept gross monthly income as a base input, then have separate sections for housing costs and all other debts. Each debt category needs a field for the minimum monthly obligation. The output produces two percentages, front-end and back-end, side by side, because lenders care about both independently. A good calculator also flags which one is the binding constraint. The housing section requires careful handling of PITI. Taxes and insurance are often bundled into an escrow estimate rather than billed directly, so the calculator should allow the user to either enter actual escrow amounts or approximate them as a percentage of the principal and interest payment. I usually default to 1.2 percent annually for property taxes and 0.5 percent for homeowners insurance when the user leaves those fields blank, but that is a rough estimate and can be way off depending on the state.
Common Pitfalls That Break Most Calculators
The first issue I ran into was revolving debt. Some calculators use the full balance divided by 20 or 30 as a proxy for the minimum payment. That is a lazy approximation. Real minimum payments depend on the card's terms, which vary widely between issuers and over time. A better approach is to ask the user for the actual minimum monthly payment, or if they do not know it, use a standard formula like 1 to 3 percent of the balance, but only as a fallback. The calculator should show a warning when it is using an estimate. The second issue is income stability. A calculator that treats all income the same will overstate qualification for borrowers with variable earnings. Self-employment income, overtime, bonus income, and alimony each have different underwriting rules. I added a dropdown next to each income source asking whether it is stable, seasonal, or one-time, and the calculator adjusts the effective monthly amount accordingly. Seasonal income gets averaged across 12 months, one-time income is usually excluded entirely, and overtime needs two years of history in most lending scenarios. I encountered a specific edge case that cost us a deal. A borrower had a deferred student loan with zero reported monthly payment. The standard calculation treated it as nonexistent debt, which inflated her back-end DTI favorable-looking. When the underwriter pulled the full credit report, they found the deferred loans and recalculated the DTI using a hypothetical payment, pushing her over the threshold. The fix was straightforward after that, the calculator now flags any debt marked deferred or in forbearance and automatically applies a standard payment estimate from the total balance divided by 60 months. It is not perfect, but it prevents the kind of embarrassing mismatch that happens when a calculator and an underwriter produce different numbers for the same person.
What This Tool Cannot Do
A DTI calculator is a screening tool, not a qualification guarantee. It does not know your credit score, your reserve requirements, your loan program, or the specific lender overlays. Two borrowers with identical DTI numbers can receive completely different outcomes based on those factors. I have seen people cleared with a 43 percent back-end DTI on an FHA loan and rejected with a 38 percent DTI on a conforming loan because the credit profile or reserves were weak. The calculator also cannot account for upcoming debt changes. If a borrower is about to finance a car or open a new credit card, the current DTI number is irrelevant. Lenders look at the projected DTI at closing, and that requires knowing future obligations, which the calculator cannot predict. The honest answer is to treat the output as a rough estimate and run a full application to get a real determination.
Get the Full Details
Practical Usage Tips
Enter debts in order of impact. The back-end DTI is usually the binding constraint, so listing credit cards and installment loans first helps you see which balances move the needle. Paying down a $5,000 credit card balance by $2,000 might reduce your monthly minimum by $40, which could drop your back-end DTI by half a percentage point. That is often more impactful than a small increase in income. Track both numbers separately over time. A common mistake is focusing only on the back-end DTI while ignoring the front-end. Some loan programs have strict front-end limits even when the back-end looks fine. If your housing payment is creeping up due to property tax reassessment or insurance premium increases, the front-end ratio can surprise you later in the process.
If you want to build something practical, I used a combination of a simple HTML form with vanilla JavaScript for the client-side calculation and a lightweight Python backend to validate inputs and log results. The frontend runs instant calculations with no page reload, and the backend handles any edge cases that require additional business logic, like income verification rules or program-specific caps. The whole thing took about two days to build and has been reliable since.