What Actually Moves Stock Prices
Most beginners approach stocks like slot machines. They check the ticker, look at a chart pattern, maybe check if a celebrity tweeted about it, and then buy. The stocks that actually last aren't chosen this way. They're chosen by people who read financial statements the way an accountant reads a grocery receipt — not because they love numbers, but because numbers are the only honest part of a company's story. Fundamental Analysis For Beginners starts with one assumption: a company's stock price should eventually reflect the real value of what the business actually does. That sounds obvious until you watch a profitable company's stock drop 40% in three weeks because management missed revenue guidance by $2 million. The fundamentals didn't change overnight. The market did.
The Three Financial Statements You Actually Need To Read
You don't need all of them memorized. You need the income statement, the balance sheet, and the cash flow statement. Everything else is decoration. The income statement tells you whether the company makes money. Not whether it reports profit — whether it makes money. There's a difference. Revenue sits at the top. Then costs get subtracted layer by layer: cost of goods sold, operating expenses, interest, taxes. What's left is net income. That's the number everyone quotes in the news. It's also the number most easily manipulated. The balance sheet is a snapshot. Assets equal liabilities plus equity. Everything the company owns, everything it owes, and what's left for shareholders if everything were liquidated tomorrow. A healthy company usually has more assets than liabilities, but that's the simplest possible reading. Look at the quality of those assets. Cash is fine. Inventory can be a trap. Goodwill — the premium paid above book value in acquisitions — is where companies hide impairment losses quietly over time.
The cash flow statement is the one beginners skip and professionals don't. It shows actual cash moving in and out, broken into operations, investing, and financing. A company can report positive net income and still run out of cash. I learned this the hard way with a mid-cap manufacturing stock in 2019. The income statement showed steady profitability for four straight quarters. The balance sheet looked clean. The cash flow statement revealed the company was paying suppliers in 90-day terms while collecting from customers in 30, and the gap was widening. Free cash flow had turned negative for two consecutive quarters. I sold before the earnings call that exposed a working capital crisis. The stock dropped 31% that week.
Get the Full Details

Key Ratios That Separate Signals From Noise
Ratios compress months of financial data into single numbers you can compare across companies. They're not predictions. They're diagnostic tools, like blood work for a business. Price to Earnings (P/E) is the most famous ratio and the least informative on its own. A P/E of 15 doesn't mean a stock is cheap. It means the market is paying 15 dollars for every dollar of annual earnings. Compare that P/E to the company's historical average, to its industry peers, and to the broader market. A P/E of 15 for a utility company is expensive. A P/E of 15 for a tech company might be reasonable. Context is everything. Debt to Equity (D/E) measures leverage. A D/E ratio above 2.0 in most industries signals uncomfortable levels of borrowing. But capital-intensive businesses like utilities and telecom naturally carry higher debt. A D/E of 1.8 for an electric company is normal. For a software company, it's a red flag.
Return on Equity (ROE) tells you how efficiently a company uses shareholder money. An ROE above 15% sustained over five years usually indicates a competitive advantage. An ROE above 30% is worth investigating further — it might be genuine excellence, or it might be the result of excessive debt inflating the ratio. Check the D/E ratio before you celebrate. Free Cash Flow Yield is free cash flow per share divided by the current stock price. It tells you how much actual cash the business generates relative to what you'd pay for a share. A yield above 5% is generally attractive. Below 2% and the stock might be overvalued relative to its cash generation. This ratio matters more than P/E for long-term investors because cash can't be reclassified or deferred the way accounting earnings can. Gross Margin is revenue minus cost of goods sold, divided by revenue. It shows pricing power. A company that can maintain or expand gross margins while raising prices has a moat. A company whose gross margins compress year after year is losing competitive position, regardless of what net income says.
Reading Between the Lines of Earnings Reports
Public companies file quarterly reports called 10-Qs and annual reports called 10-Ks. These are publicly available on the SEC's EDGAR database. They're dense, dry, and absolutely necessary if you want to do this properly. The management discussion and analysis section, or MD&A, is where leadership explains what happened during the quarter. Read it carefully. Pay attention to what they emphasize and what they minimize. If revenue grew 12% but management spends three paragraphs explaining why foreign exchange rates hurt them, the underlying business might not be as strong as the top-line number suggests. Footnotes matter more than beginners expect. Footnote 4 might detail lease obligations not shown on the balance sheet before recent accounting changes. Footnote 7 might reveal that a significant customer accounts for 18% of revenue. Losing that customer would be catastrophic and the income statement won't warn you about it directly. I once held a consumer goods stock for eight months because the earnings looked solid. The footnote about customer concentration came out during an earnings call Q&A session. The CEO mentioned casually that the company was negotiating a new distribution deal with its largest retailer, who had been pressuring for deeper discounts. Two months later, gross margins compressed by 400 basis points. The stock fell 27%. I should have read footnote 12 in the previous 10-K.
Compensation discussions in the proxy statement — the DEF 14A — reveal whether executive incentives are aligned with long-term value creation or short-term stock price manipulation. If bonuses are tied primarily to EPS targets without cash flow hurdles, management has an incentive to buy back shares or cut R&D to hit numbers. That's not always bad, but it's a structural bias you should know about.
Common Mistakes That Cost Real Money
The biggest mistake beginners make is treating fundamental analysis as a one-time event. You read a report, calculate some ratios, buy the stock, and then check back six months later. The business has changed. New competitors emerged. Supply chains shifted. Interest rates moved. The thesis you had six months ago is probably outdated. Another mistake is focusing exclusively on forward-looking projections. Analyst reports full of five-year growth models sound impressive. They're almost entirely speculative. A company's management will give you guidance for the next quarter or two. Beyond that, it's fiction dressed in spreadsheets. Build your analysis on what has already happened, not on what someone hopes will happen. Data dependency is a real constraint. Fundamental analysis requires access to accurate, timely financial data. Free sources like Yahoo Finance provide enough for basic screening, but they strip out the footnote detail and operational breakdowns that separate superficial analysis from actual understanding. Paid services like Bloomberg Terminal or even Midas offer better data, but even those have gaps for smaller companies. For individual investors, the SEC's EDGAR database and the company's investor relations page are the most reliable sources, even if the formatting is archaic and the navigation is frustrating.
Fundamental analysis also has a timing problem. A stock can remain undervalued for years while the market stays irrational. Benjamin Graham wrote this in The Intelligent Investor, and it sounds like a warning rather than advice until you're sitting on a position that's correct but deeply unprofitable. In 2020, several consumer staples companies traded at P/Es below 12 while the broader market was bidding technology stocks to P/Es above 40. The fundamentals were sound. The valuations were reasonable. The stocks underperformed the Nasdaq by double digits for 18 months. Value investors who stuck with their analysis were right and broke in the short term. This method works best for long-term holding periods of three to five years or more. If you're trading on shorter timeframes, technical analysis or momentum strategies will serve you better. Fundamental analysis is not a day-trading tool. It's a business ownership framework, and treating it like anything else will produce poor results. The final limitation is that fundamental analysis cannot predict black swan events. A pandemic, a natural disaster, a sudden regulatory change, a geopolitical conflict — none of these appear in financial statements. Warren Buffett keeps a cash reserve specifically for this reason. He knows his analysis is powerful but incomplete. A beginner should operate with the same humility. Screen carefully, position conservatively, and accept that no amount of reading will protect you from everything.
Getting Started Practically
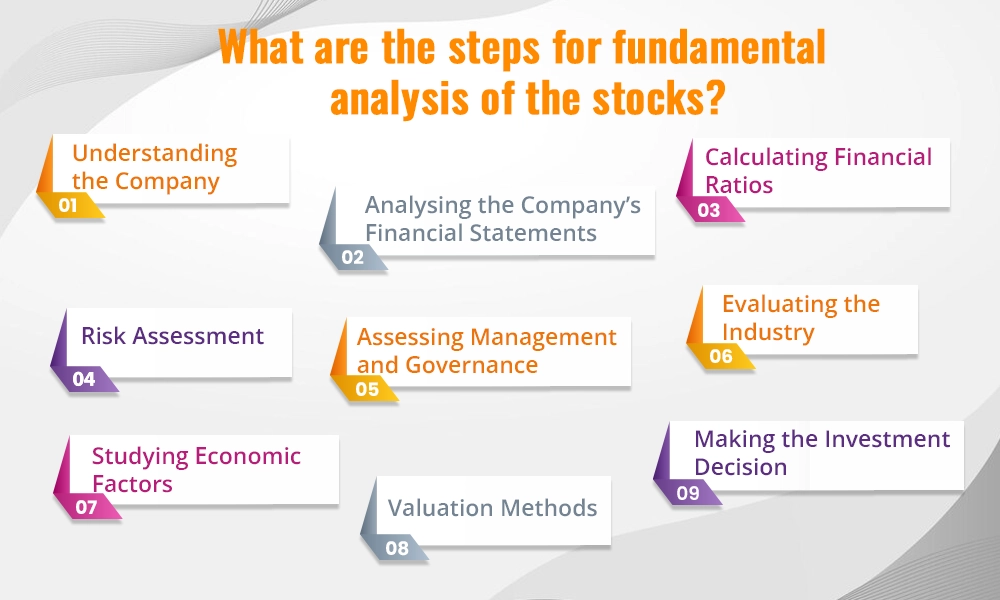
Start with companies you understand. If you use a product daily, look at the company that makes it. Read the latest 10-K. Check whether revenue is growing, whether margins are stable or expanding, and whether debt is manageable. Do this for five companies before you buy anything. The process of reading ten pages of financial data for a company you interact with regularly takes about 45 minutes. After a few iterations, it drops to roughly 20 minutes per company. Use a screener to narrow your universe. Finviz offers a free tier that lets you filter by P/E, debt to equity, ROE, and revenue growth. Set reasonable parameters — P/E between 10 and 25, D/E below 1.5, ROE above 12%, revenue growth above 5% — and see what comes back. Most screens return 50 to 200 results. That's a starting list, not a buy list. From there, pick three companies and pull their annual reports. Read the income statement, balance sheet, and cash flow statement for the last five years. Look for trends, not single-year snapshots. A single bad quarter is noise. Five years of declining margins is a pattern.
Write down your thesis in one paragraph before you buy. State why the company is valuable, what assumptions you're making, and what would invalidate your thesis. When that invalidation happens — and it will — you'll know when to sell instead of hoping the market recovers. Fundamental analysis doesn't guarantee returns. It guarantees that your decisions are based on something real rather than something hopeful. That distinction matters more than most beginners realize until they've already lost money on a hopeful bet.