What Actually Happens When You Open a Stock Screener
You see revenue numbers, earnings reports, balance sheets full of rows you don't know how to read yet. The temptation is to stare at P/E ratios until your eyes glaze over. I did that for three years straight, pulling up spreadsheets, cross-referencing metrics, thinking that if I just collected enough data the answer would appear on its own. It never did. The truth is simpler and slightly more frustrating than anyone will tell you. Fundamental analysis isn't about collecting every ratio ever calculated by a finance professor. It's about asking whether a business can survive the next five years and whether the current price reflects that reality or completely misses it.
Getting Started With Fundamental Ideas Of Analysis
Start with the income statement. Not because it's the most important document, but because it tells you whether the company is actually making money from selling something rather than manipulating accounting figures. Revenue growth above 10% year-over-year for three consecutive years suggests real demand. Below 5% and you're looking at a mature or declining business. Both are fine if the price is right, but they require completely different expectations. Then look at gross margins. Companies that maintain or expand gross margins while competitors compress theirs usually have genuine competitive advantages. This is where most beginners get fooled. A company can grow revenue by discounting heavily and appearing successful on the surface, but gross margins tell you whether that growth is actually profitable or just expensive. I learned this the hard way with a mid-cap manufacturing company in 2019. Revenue was up 22%. Management was issuing press releases about market expansion. The stock had climbed 40% that year. But gross margins had compressed from 38% to 29% over four quarters. The growth was entirely price-driven, not volume-driven. The company was essentially buying revenue at a loss. I sold within a week. The stock dropped 55% the following year when the margin story caught up to reality.
The Metrics That Actually Matter
Return on equity is one of those metrics everyone mentions and almost no one uses correctly. A 25% ROE sounds impressive until you realize the company achieved it by running at 80% debt-to-equity. Leverage inflates ROE artificially. The clean way to think about it is whether a company generates strong returns without needing excessive borrowed money to do so. Free cash flow conversion matters more than free cash flow itself. A company converting 80% or more of net income into free cash flow regularly is telling you something important about the quality of its earnings. Low or negative conversion despite reported profitability usually means either heavy capital expenditure requirements, growing receivables that might not get collected, or inventory building that could become obsolete. This is where audit fraud tends to hide. Debt maturity profiles are another detail beginners ignore at their peril. A company with $2 billion in debt maturing in six months and weak cash generation faces a fundamentally different risk profile than the same company with $2 billion in debt maturing over ten years. Check the next debt maturity date. If it's within two years and the company is barely generating positive free cash flow, that's a red flag regardless of what the P/E ratio says.
Get the Full Details
What Fundamental Analysis Gets Wrong
The biggest limitation nobody admits openly is that fundamental analysis assumes markets eventually correct mispricing. This works most of the time but fails catastrophically during periods where sentiment overrides fundamentals for years. The Japanese market from 1990 to 2020 is the textbook example. Even companies with reasonable valuations, solid cash flows, and low debt trades below 2010 levels for three decades. Being right fundamentally doesn't save you if the macro environment stays hostile. Another blind spot is the assumption that financial statements reflect economic reality. They don't. Accounting is full of estimates and choices. Inventory valuation methods, depreciation schedules, revenue recognition policies, pension assumptions. Companies can legitimately choose different approaches that produce very different numbers. Understanding what choices the company made and whether they seem conservative or aggressive relative to peers takes actual reading of the footnotes, not just the summary ratios. Here's a practical example from my own work. In 2021 I analyzed a software company that reported clean earnings with strong margins. The P/E was reasonable. Free cash flow looked solid. But the footnotes revealed the company was capitalizing development costs that most competitors expense. This inflated reported profits and depressed apparent growth. Once I adjusted for this, the real margin profile was significantly worse. The stock later downgraded its guidance and the market corrected aggressively. The fundamental numbers weren't fake. They were just presented in the most favorable accounting framework available.
A Working Process That Doesn't Waste Time
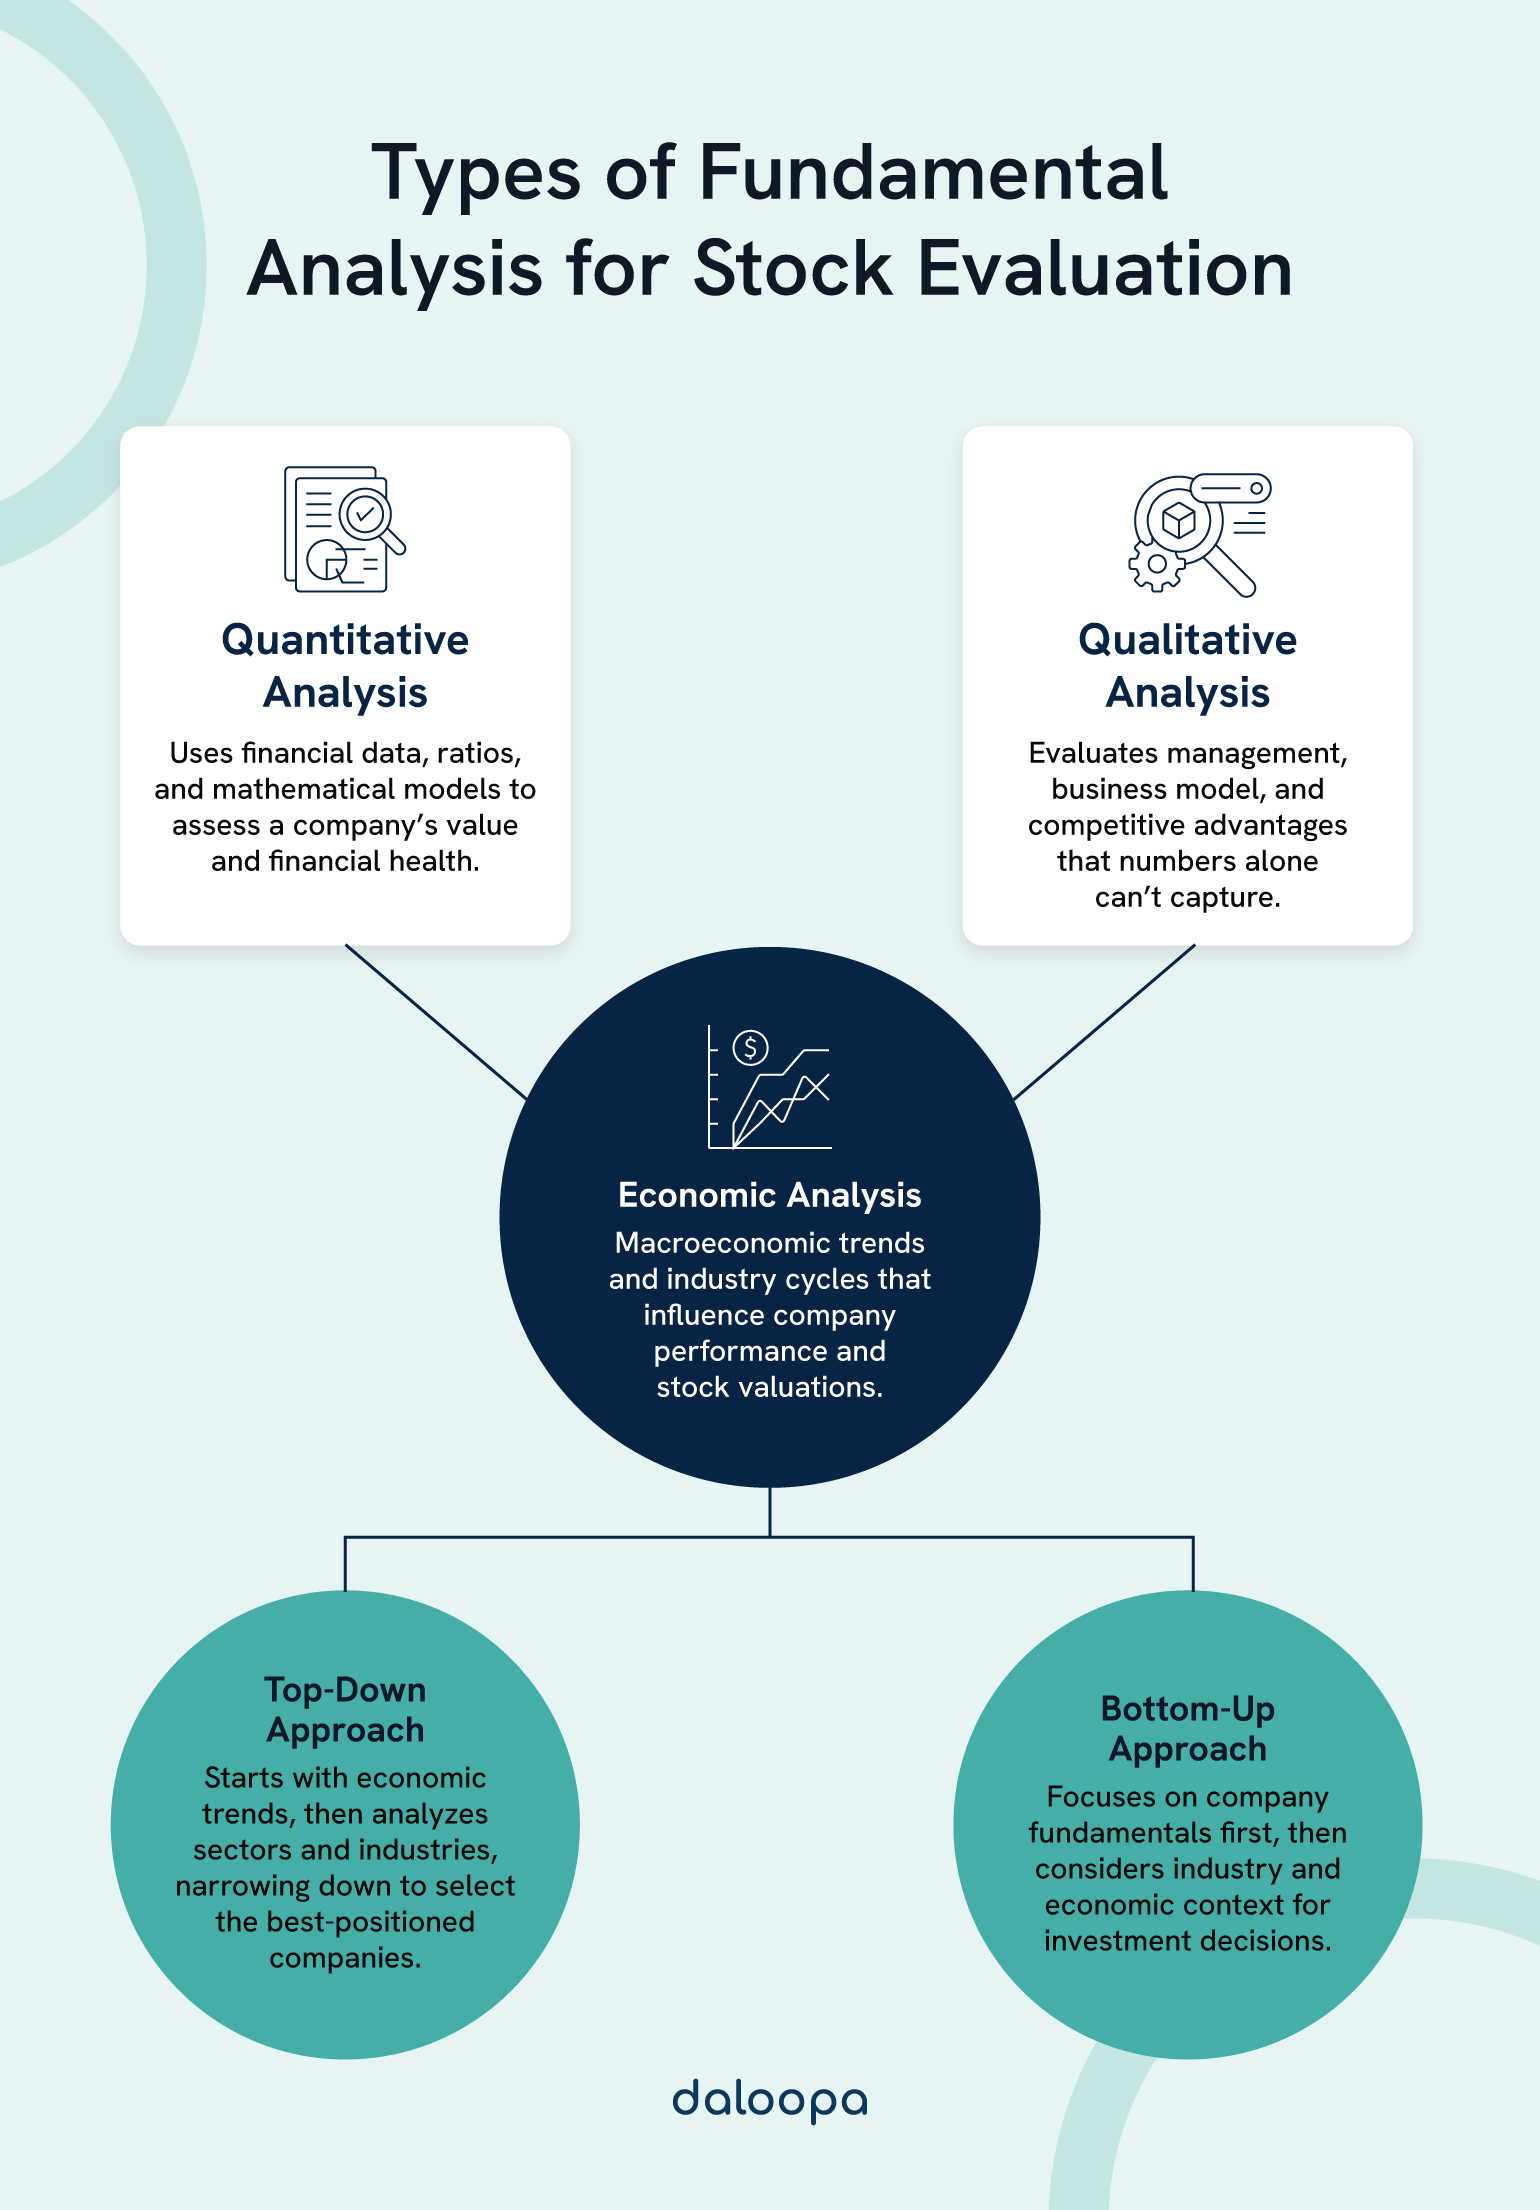
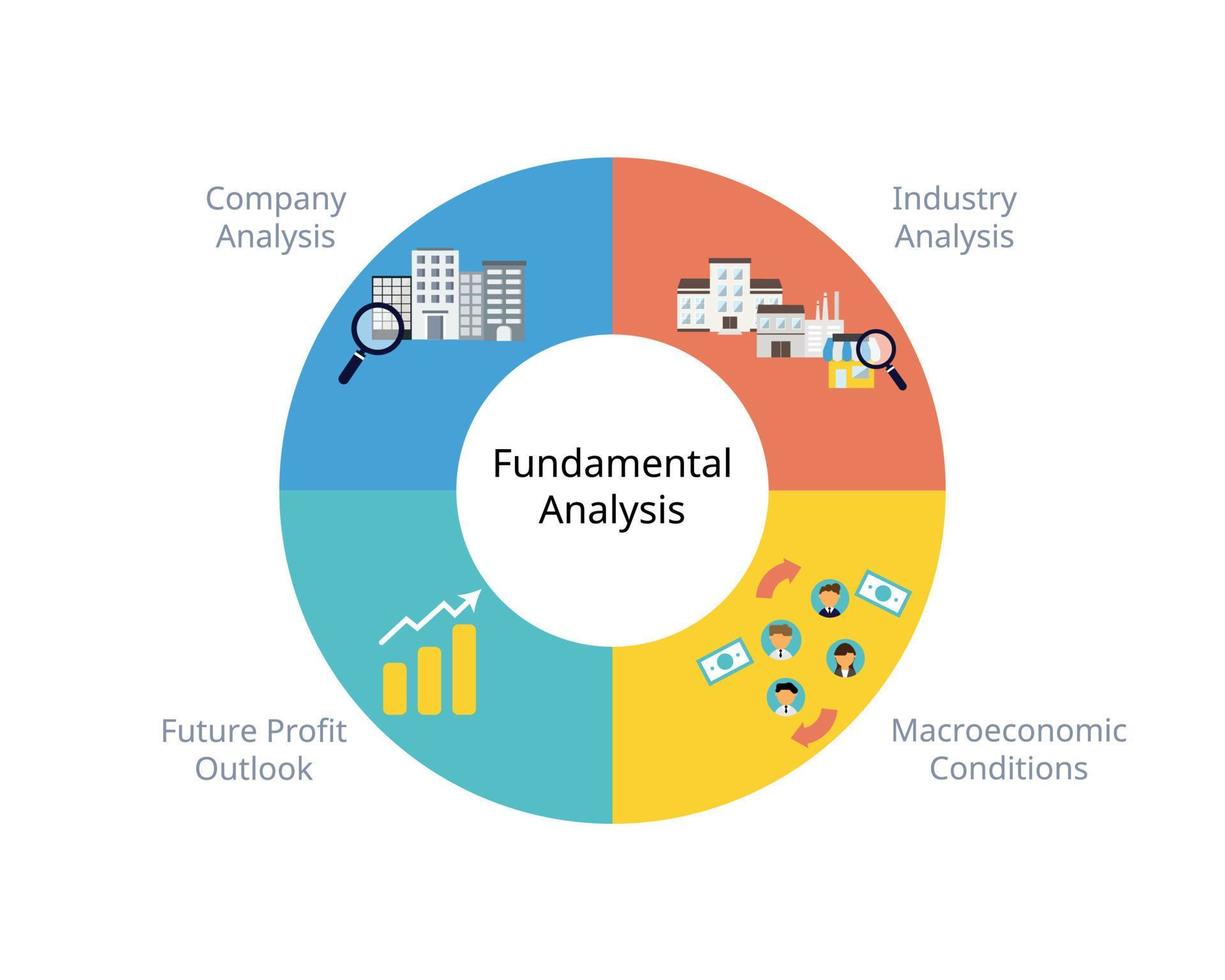
Most analysts spend hours chasing every metric available. A more efficient approach is to limit your screening to five or six numbers that actually differentiate good businesses from bad ones. Revenue growth rate, gross margin trend, free cash flow conversion, debt-to-equity ratio, and return on invested capital. If a company passes those five filters, then dig deeper. If it fails any of them, investigate why rather than proceeding as if it might still be attractive. Industry context matters enormously but gets underweighted. A 40% gross margin in software is normal. In retail it's suspicious. A debt-to-equity ratio of 2.0 might be fine for utilities but terrible for a consumer company. The numbers mean different things in different industries. Learn the typical ranges for whatever sector you're analyzing before applying them rigidly. Valuation is where most people get stuck because there's no single correct answer. Price-to-earnings ratios, price-to-book ratios, enterprise value multiples, discounted cash flow models. All of them have useful moments and all of them fail at other times. The practical approach is to use at least three different valuation methods and only buy when they converge around similar values. If one method says the stock is cheap and another says it's fair but not attractive, that disagreement usually signals something you haven't understood yet. Figure out what it is before buying.
When to Stop Analyzing and Just Buy
There's a point where additional research produces diminishing returns that aren't worth the time. After three or four hours of work on a position that represents less than 2% of your portfolio, stop. The probability of discovering something material after that threshold is low, and the opportunity cost of your time is real. Some of my best investment decisions came from companies I only spent an hour researching because the numbers were clear and the thesis was obvious. Conversely, some positions that seemed attractive after casual review turned out to have serious problems once I dug into the details. This is why I set a minimum research threshold of two hours for any position larger than 5% of the portfolio. Smaller positions get lighter treatment. Bigger ones demand proportionally more scrutiny. The allocation size should drive the depth of analysis, not the other way around. Fundamental analysis isn't a crystal ball. It's a tool for reducing uncertainty in an uncertain world. Used properly it helps you avoid obvious mistakes and identify genuine opportunities. Used obsessively it paralyzes decision-making. The key is knowing when you have enough information to act and when additional research will only delay that action without materially improving your odds.