Understanding the Connection Between Derivatives and Integrals
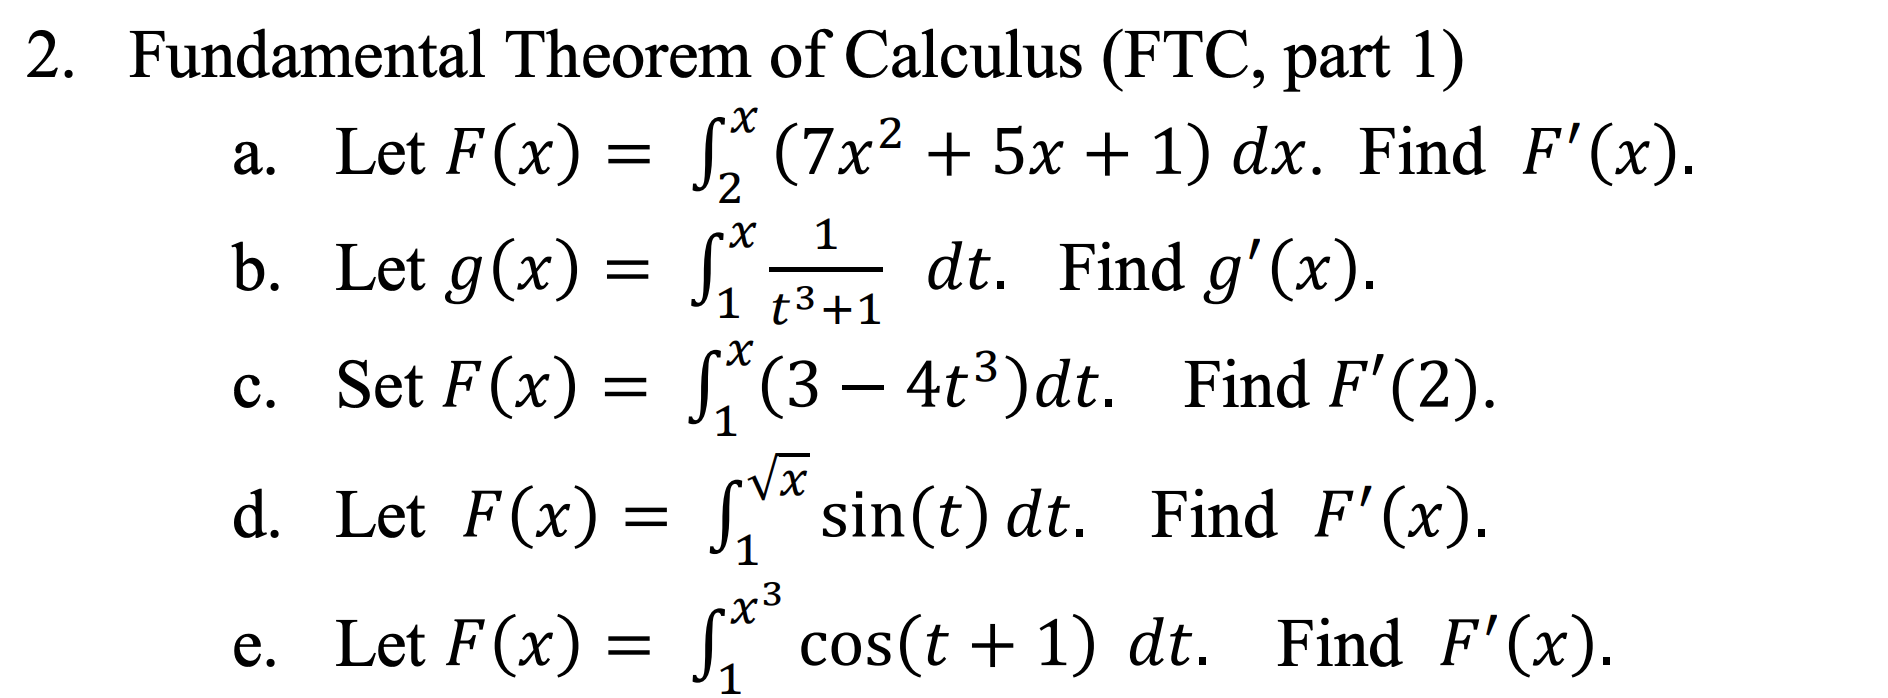
When I first encountered calculus, the two main operations felt completely separate. Differentiation was about slopes and rates. Integration was about areas under curves. They operated independently, each with their own rules and techniques. Then came the realization that they're actually inverse processes, which changed how I approach practically every problem. The formal statement goes like this. If f is continuous on [a,b], then the function F defined by F(x) = integral from a to x of f(t)dt is continuous on [a,b] and differentiable on (a,b), with F'(x) = f(x). In plain language, taking the derivative of an integral essentially undoes the integration. This feels counter-intuitive at first because integration and differentiation are both abstract operations. The theorem tells us they're inverses in a very specific sense. When you integrate a function from a fixed lower bound to a variable upper bound, the result is itself a function. Differentiating that function returns you to the original integrand.
I spent weeks wrestling with this concept before it clicked. The confusion came from treating definite and indefinite integrals as the same thing. They're not. The Fundamental Theorem Of Calculus Part 1 specifically deals with definite integrals that have variable upper limits. The output is a function, not a number.
How It Works in Practice
Here's a concrete example that made everything click for me. Take f(t) = 2t. The integral from 0 to x of 2t dt equals x^2. Now differentiate x^2 with respect to x and you get 2x, which is exactly your original function f(x). The process works because the accumulation rate at any point equals the height of the curve at that same point. This matters enormously when dealing with physics problems involving position, velocity, and acceleration. If acceleration is constant at 9.8 m/s^2, integrating gives velocity, and differentiating velocity returns acceleration. The theorem guarantees this works without requiring explicit computation of limits. I remember encountering a particularly nasty problem involving a piecewise continuous function where the lower limit kept changing. The standard textbook examples all use fixed bounds, but real problems rarely cooperate. I needed to find the derivative of integral from sin(x) to cos(x) of e^(t^2) dt. Direct computation seemed impossible because e^(t^2) has no elementary antiderivative.
Get the Full Details

The workaround I discovered involved splitting the integral into three parts using a constant middle point c, then applying the Fundamental Theorem to each piece separately. The result combined with the chain rule gave me e^(cos^2(x))*(-sin(x)) - e^(sin^2(x))*cos(x). This technique proved essential for handling boundary conditions in differential equations.
Common Misunderstandings and Pitfalls
Students frequently confuse Part 1 with Part 2. Part 1 establishes the relationship between differentiation and integration. Part 2 provides the evaluation technique using antiderivatives. Mixing them up leads to circular reasoning when proving results. Another trap involves assuming continuity everywhere. The theorem requires continuity on the closed interval. Discontinuities create problems that require careful handling. I've seen students apply the theorem to functions with jump discontinuities and get nonsensical results. The derivative simply doesn't exist at those points. There's also the issue of variable lower bounds. Most textbooks emphasize variable upper bounds, but the lower bound can vary too. The sign flips depending on which bound moves. I encountered this in an optimization problem where both bounds depended on the variable, and misapplying the chain rule cost me significant time.
When This Approach Fails
The theorem breaks down when f isn't continuous. Step functions, functions with infinite discontinuities, and certain pathological cases require different tools. Lebesgue integration handles some of these, but that's beyond standard calculus. Numerical integration becomes necessary when antiderivatives don't exist in closed form. Functions like e^(-x^2), sin(x)/x, and 1/ln(x) resist symbolic integration. The Fundamental Theorem still applies in principle, but computing the integral requires approximation methods like Simpson's rule or Gaussian quadrature. I found that for many engineering applications, numerical differentiation of numerically computed integrals amplifies errors dramatically. Small inaccuracies in the integral evaluation compound when you differentiate. Regularization techniques or smoothing filters often become necessary to stabilize the results.

Advanced Applications and Insights
The theorem extends naturally to higher dimensions through vector calculus. Green's theorem, Stokes' theorem, and the divergence theorem all generalize this core idea. Recognizing these connections helps when moving beyond single-variable calculus. In differential equations, the theorem provides existence and uniqueness results. The integral equation form y(x) = y(a) + integral from a to x of f(t,y(t))dt often reveals properties that the differential form obscures. Fixed-point iteration methods exploit this reformulation. Probability theory relies heavily on this relationship between derivatives and integrals. The probability density function and cumulative distribution function are connected through exactly this mechanism. Differentiating the CDF recovers the PDF, and integrating the PDF reconstructs the CDF.
When working with improper integrals, convergence issues complicate direct application. I once spent an afternoon verifying whether a particular parameter regime satisfied the continuity requirements before safely applying the theorem. Some integrals converge conditionally rather than absolutely, which changes what techniques remain valid.
Practical Computation Strategies
For computational work, I usually verify continuity first, then check whether the bounds create complications. Symbolic systems like Mathematica or Maple handle straightforward cases well, but they sometimes produce incorrect results when boundary conditions aren't properly specified. When implementing numerically, I recommend computing the integral and derivative separately rather than trying to combine them. Automatic differentiation frameworks handle this elegantly, but manual implementation requires care with finite difference approximations near boundaries. The relationship between accumulation and rate of change applies across disciplines. Economics uses it for marginal analysis. Biology applies it to population dynamics. Understanding the underlying mechanism proves more valuable than memorizing the formal statement.