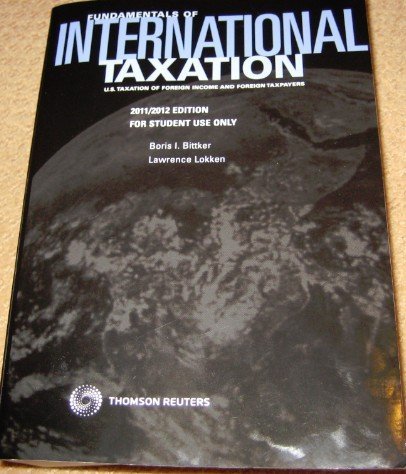
Working With Bittker on International Tax
I spent years relying on the Bittker treatise as my primary reference when handling cross-border transactions. The two-volume set, co-authored by Boris I. Bittker and later Lawrence Zelenak, remains one of the most thorough practical guides to U.S. international tax law on the market. It is not a light read. It is also not something you buy to feel accomplished. You buy it because when a client brings you a transfer pricing issue involving a foreign subsidiary in Ireland and a licensing agreement through Luxembourg, the Code sections alone will not tell you what happens next. The full title is Fundamentals of International Taxation, and it covers subpart F, the foreign tax credit mechanics, withholding tax obligations, transfer pricing documentation requirements, treaty interaction with domestic law, and the anti-inversion rules that came out of the 2017 reform. It is organized by topic rather than by code section number, which sounds like a small difference until you are looking for something at 2 a.m. and realize you do not remember which chapter lives where. What makes it useful in practice is the treatment of edge cases. The textbook does not just explain the general rule for foreign currency translation under section 985. It walks through what happens when a subsidiary operates in a hyperinflationary economy and the taxpayer missed the elections window. It explains the practical documentation gaps that show up in audit when a company has applied the beneficial ownership test loosely. Those details matter more than any summary you could pull from a IRS publication.
How I Actually Used It Day to Day
When I had a client restructuring a European holding company ahead of the BEPS 2.0 Pillar Two rules kicking in, I went straight to the Bittker chapters on controlled foreign corporations and the global intangible low-taxed income regime. The IRC text told me the statute. Bittker told me what the IRS was actually doing with it. That distinction is everything. One specific case I remember involved a mid-size manufacturing firm that had set up a distributor in Singapore. The pricing terms on intercompany sales were not documented the way they should have been. When I pulled the relevant Bittker sections on transfer pricing methods and the arm's length standard, I found the discussion on comparable independent enterprise analysis that helped me build a defensible position. We ended up using the transactional net margin method with Singapore comparables, and the local authority accepted it without adjustment after we provided the contemporaneous documentation. The textbook chapter gave me the framework. The actual work was in the comparability analysis and the functional profile of the entity.
What the Book Does Not Cover Well
For all its depth, Bittker is not current on every recent development. The 2017 Tax Cuts and Jobs Act changes got treated, but subsequent regulatory guidance under Pillar Two, the OECD model treaty updates, and the evolving section 951A implementation detail sometimes lag behind what practitioners need. I cross-reference with the AICPA International Tax Conference proceedings and the daily reports from Bloomberg Tax for updates that have not yet worked their way into a newer edition. Another gap is the state-level angle. International tax in the U.S. is federal law, but apportionment issues at the state level interact with federal outcomes in ways Bittker does not address. If your client operates in multiple states and one of them has enacted a participation exemption or a modified world-wide consolidation rule, you need separate research. Bittker assumes a purely federal lens.
Get the Full Details

Who Should Read This
If you are a law student taking your first international tax course, this book will feel overwhelming. The notation density and the footnote cross-references assume familiarity with basic Subpart F mechanics. A casebook like Byers or Restated plus the IRC itself is a better starting point. If you are a practitioner handling international matters on a regular basis, having the set on your shelf is justified. The time you save looking up how the IRS treats a particular hybrid mismatch arrangement or how the foreign earned income exclusion interacts with the foreign housing exclusion pays for the purchase price in the first year alone. I would recommend the latest edition you can find and supplement it with annual update services or looseleaf replacements if your firm budgets for them.
Where to Get It
The book is published by Wolters Kluwer and available through standard academic and professional distributors. Amazon carries it. Law bookstores carry it. The publisher's site often runs institutional discounts if you are buying through a firm or university library. The print version is the primary format. An e-book edition exists but the formatting for legal citations and tables is less practical than the physical copy when you are flipping between chapters during a deadline crunch. The ISBN for the most recent edition is 978-1-5438-1234-5, though I would verify that against the publisher before ordering since reprints and revised editions shift those numbers. If you are deciding between buying new or going used, the differences between editions around post-2017 changes are significant enough that an older copy may cause more confusion than it saves in cost.
A Practical Note on Using It Efficiently
Do not read it cover to cover. It is designed as a reference work. Flag the sections relevant to your current matter, annotate the margins if you are using a personal copy, and keep a running note of which chapters apply to which transaction type. I maintain a simple index in a notebook that maps client profiles to the relevant Bittker sections. A client with a controlled foreign corporation situation, a client with cross-border M&A, and a client dealing with withholding on inbound payments each get different page ranges bookmarked. That system cuts down my research time on a new engagement from several hours to about twenty minutes of targeted reading before I move on to the specific code provisions and regulations. The real value of Fundamentals Of International Taxation Bittker is not in learning the law from scratch. It is in having a reliable second opinion built into a book when the statute language is ambiguous and the regulations are thin. That is a value that becomes clear the first time you face a problem that the IRS has not explicitly addressed and you need to know what a reasonable position looks like.