Using the Fundamental Theorem of Calculus in Practice
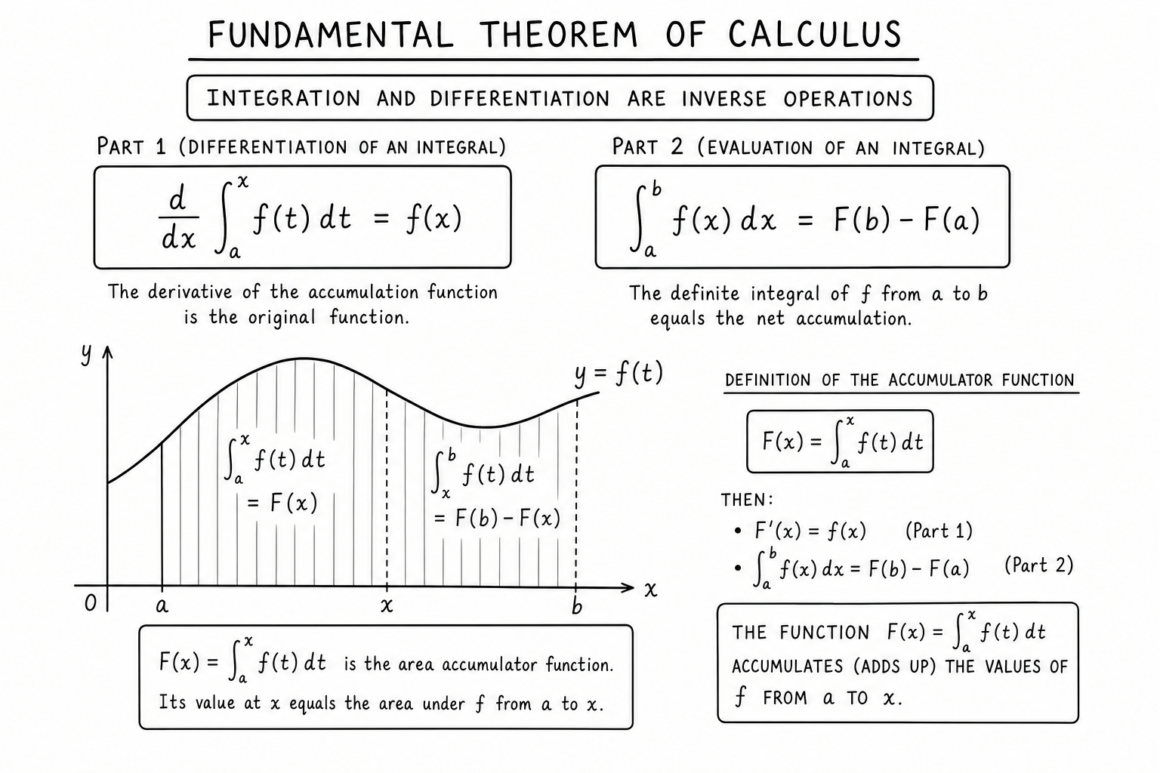
The Fundamental Theorem Of Calculus connects two operations that students spend months learning separately, and most people never fully trust the connection until they hit it again in a real problem. It says, in plain terms, that differentiation and integration are inverse processes. That is it. The theorem comes in two parts, and both parts are used constantly, but the way engineers and physicists actually apply it is different from the way textbooks present it. Part one states that if f is continuous on [a, b] and you define F(x) as the integral from a to x of f(t) dt, then F is differentiable on (a, b) and F prime equals f. This is the version that lets you turn an integral equation into a differential equation. I used this version last year debugging a signal processing pipeline where someone had written a convolution integral and needed its derivative for a stability analysis. The integral had variable limits on both ends, which meant the basic textbook statement did not apply directly. I applied the Leibniz integral rule, which is the generalized form that handles variable bounds: d/dx of the integral from g(x) to h(x) of f(t) dt equals f(h(x)) times h prime(x) minus f(g(x)) times g prime(x). That saved about forty minutes of re-deriving the relationship from first principles. The part one theorem is deceptively simple. The continuous function requirement is not a suggestion. If f has a jump discontinuity, the derivative of the integral does not exist at that point in the usual sense. I learned that the hard way when working with piecewise constant data from sensor readings. The numerical integrator would produce a continuous output, but the derivative at the transition points was undefined. The workaround was to smooth the input with a low-pass filter before integrating, which made the function effectively continuous for the purposes of the calculation.
Part Two and the Evaluation Method
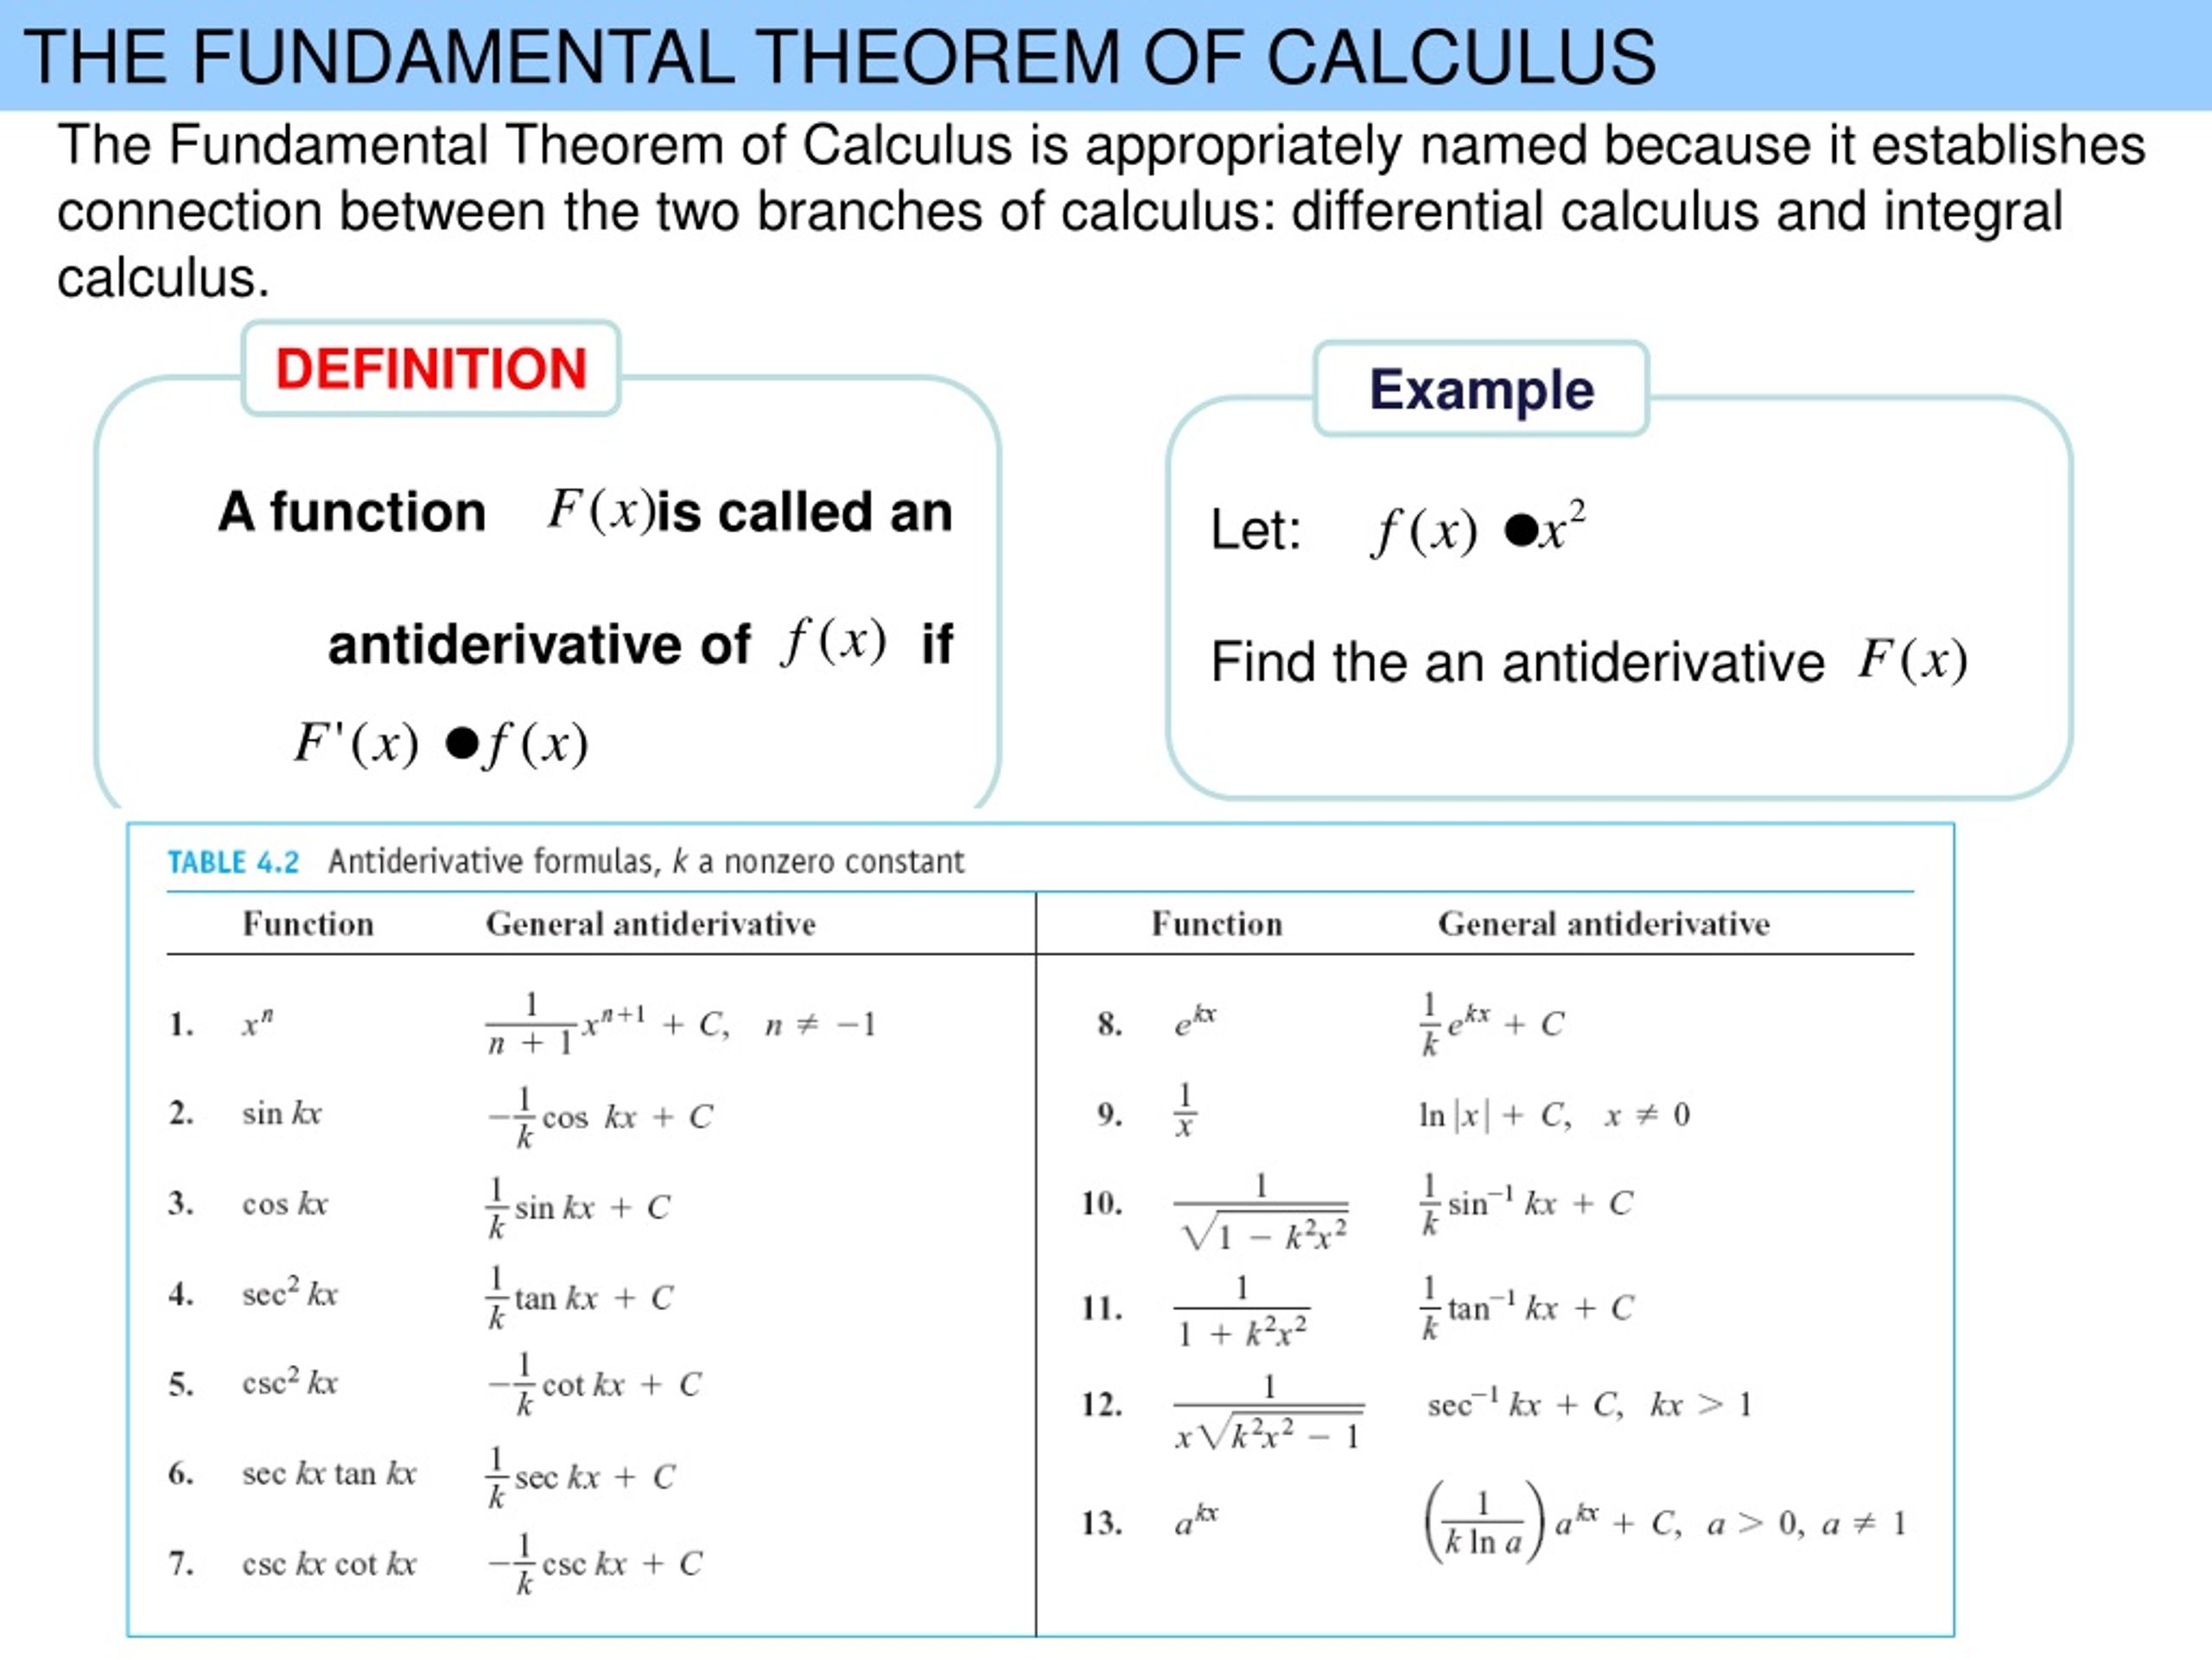
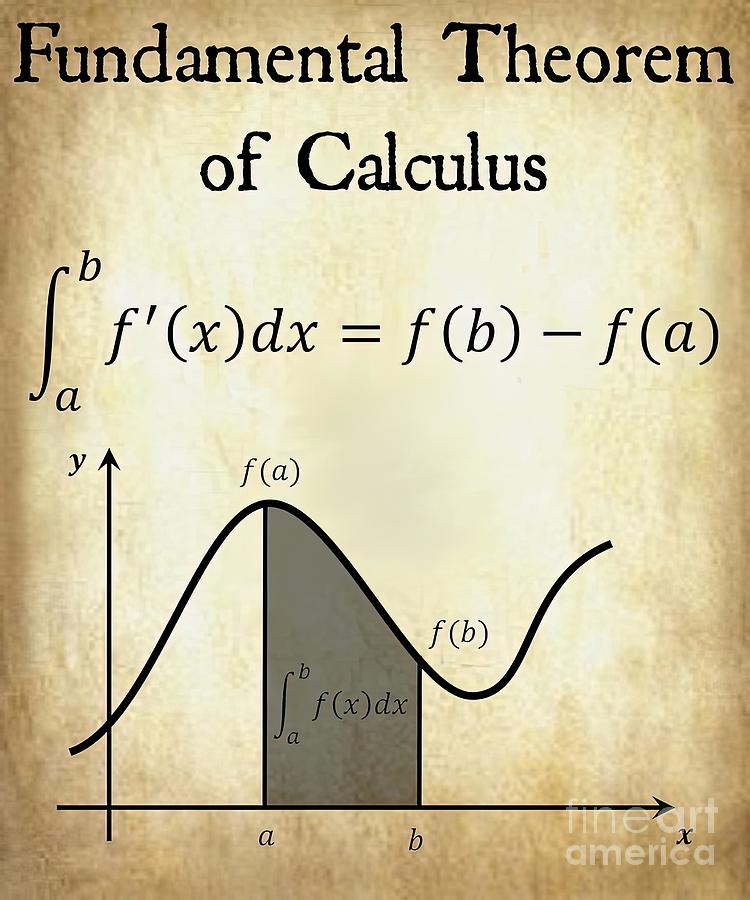
Part two states that if f is continuous on [a, b] and F is any antiderivative of f, then the definite integral from a to b of f(x) dx equals F(b) minus F(a). This is the computational workhorse. You find an antiderivative, plug in the bounds, subtract. The reason people stumble is that part two does not tell you how to find the antiderivative. That remains the hard part of calculus. The theorem guarantees that one exists for any continuous function. It does not guarantee that you can write it down in terms of elementary functions. A common misconception is that part two applies whenever you have an antiderivative, regardless of continuity. That is not true. If f has an infinite discontinuity inside the interval, the integral is improper and part two does not apply in its standard form. I ran into this when calculating the integral of 1 over the square root of x from 0 to 1. The function is unbounded at zero. The integral converges to 2, but you have to treat it as a limit, not as a straightforward application of part two. The result happens to be the same, but the justification is different and examiners will mark you wrong if you skip the limit step.
When the Theorem Fails or Becomes Impractical
There are several scenarios where the Fundamental Theorem Of Calculus does not help you much. The first is when the function is not integrable in any conventional sense. Riemann integrability requires the function to be bounded and continuous almost everywhere. The Dirichlet function, which equals 1 on rationals and 0 on irrationals, fails both conditions in a way that makes the Riemann integral impossible. Lebesgue integration handles this, but the fundamental theorem in its basic form assumes Riemann integrability and continuous derivatives. The second scenario is when the antiderivative exists but cannot be expressed with elementary functions. The integral of e to the negative x squared is a classic example. The function is perfectly continuous everywhere, so the theorem applies, but there is no closed-form antiderivative using polynomials, exponentials, logarithms, or trigonometric functions. In practice, this means you need numerical integration or special functions like the error function. The theorem still justifies the existence of the integral, but it gives you no computational shortcut. The third limitation is worth noting for anyone doing applied work. Numerical integration routines often approximate the integral directly using methods like Simpson's rule or Gaussian quadrature rather than finding an antiderivative and evaluating it at the endpoints. This is sometimes more accurate because it avoids the accumulation of rounding errors that happens when you compute a high-degree polynomial antiderivative and then subtract two large nearly equal numbers. For the integral from 0 to 100 of e to the negative x dx, computing the exact antiderivative gives you 1 minus e to the negative 100, which is essentially 1. But if your numerical method has limited precision, the subtraction can lose significant digits. In those cases, computing the integral directly with a numerical quadrature method is the better approach.
Get the Full Details

Practical Tips That Actually Matter
Check continuity before you start. Spend thirty seconds verifying that the integrand is continuous on the interval of integration. If it is not, identify the discontinuities and split the integral at those points. This alone prevents about half the errors I see in undergraduate assignments. Use substitution carefully. The theorem applies to the transformed integral, not the original one in a way that ignores the bounds change. When you substitute u equals 2x plus 1 in an integral from 0 to 3, the bounds become 1 to 7. Forgetting to update the bounds is the most frequent mistake, and it is a zero-point error that costs more marks than any sophisticated misunderstanding. Keep the Leibniz rule in your toolkit. The basic statement assumes constant bounds, but real problems rarely have constant bounds. The generalized form covers every case you will encounter in engineering mathematics, physics courses, and most applied probability work. Memorizing just the basic version leaves you stranded on anything with a variable upper limit.
The theorem does not require you to find the most general antiderivative with the constant of integration. Part two works with any single antiderivative because the constant cancels out in the subtraction. Writing F(x) plus C and then seeing C vanish every time is a useful sanity check, but carrying C through the calculation is unnecessary overhead. Be aware that the theorem guarantees existence, not computability. Knowing that an antiderivative exists is mathematically satisfying. It does not help you evaluate a definite integral if you cannot write down the antiderivative explicitly. In those cases, numerical methods are not a failure of the theorem. They are the standard tool, and relying on them is correct practice rather than a compromise.