How to Handle Credit Card Surcharges Under GAAP
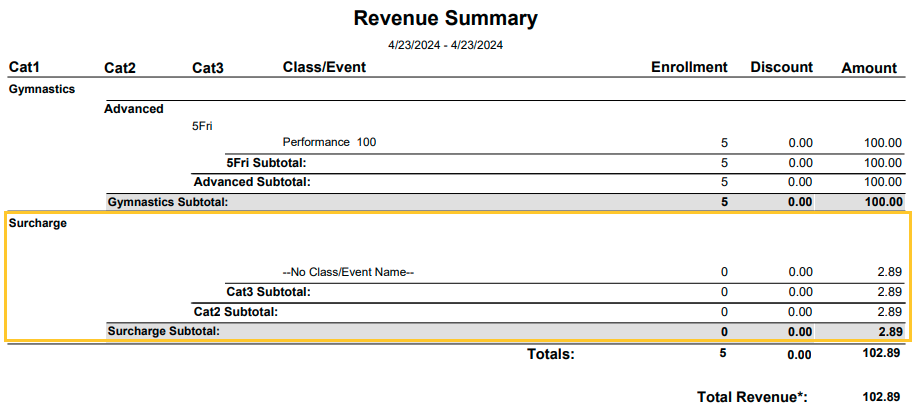
Most people walk into this thinking it is straightforward because it technically is, but the practical accounting side has enough wrinkles that getting it wrong will mess up your monthly close. Credit card surcharges are not the same thing as credit card discount fees, and that distinction matters for every journal entry you will write. A credit card surcharge is a fee the merchant passes directly to the consumer at the point of sale when they choose to pay with a card. It is typically capped at the merchant's actual processing cost or 3%, whichever is lower, depending on your network and state rules. The surcharge is collected from the customer and remitted to the processor. That flow of money determines how it gets recorded. Under GAAP, the critical question is whether the surcharge is treated as revenue or as a reduction of the processing expense. The answer depends on the contractual arrangement with your payment processor and how you present the transaction to the cardholder. Most small and mid-market merchants end up netting the surcharge against their credit card discount expense on the income statement. This is the more common and defensible approach because the surcharge is functionally a reimbursement for the processing cost, not income earned from a distinct performance obligation.
Here is the journal entry pattern for a $100 sale with a 3% surcharge when you net it against expense: Debit Cash $103
Credit Sales Revenue $100
Credit Credit Card Discount Expense -$3 That negative expense credit is what trips people up. It is not revenue. It is a contra-expense. If you credit it to income instead, your gross margin percentages will be inflated and your auditors will ask questions during a revenue recognition walkthrough.
What Beginners Get Wrong About the Setup
The biggest mistake I see repeatedly is treating the surcharge as a separate line item in the chart of accounts that gets buried in other income. This looks plausible on the surface because the money does come in, but it violates the substance-over-form principle that GAAP actually expects you to apply here. Your processing statements already show the discount fee as a line item. Your surcharge collection is the offset. Keeping them together in one contra-expense account mirrors how the economic event actually plays out. Another common error is recording the surcharge at the time the processor batches and deposits the funds. The surcharge is collected at the point of sale, not at settlement. You need to accrue it in the same period as the underlying sale. If you wait until the deposit hits your bank account, you are delaying revenue recognition and creating a timing mismatch between when the sale is recorded and when the related offset gets booked. Book it on the transaction date, not the deposit date.
Get the Full Details

The Edge Case I Dealt With Last Year
I ran into a situation where a client was running a mixed payment operation, part physical POS and part online cart, with two different processors handling the cards. The online processor allowed surcharging. The in-store processor did not. The accounting team had one bank account receiving commingled deposits, and the surcharge revenue was getting swept into the general deposit batch without any identification tag. The workaround was to build a reconciliation file directly from each processor's API data. I pulled the daily settlement reports from both processors and matched them to the sales records by transaction ID. The surcharge amounts came out as a separate column in the extract, and I used that to auto-generate the daily journal entries. Anything that did not match up between the two data sources was flagged for manual review. This took about 15 minutes per day once the automation was in place, compared to the original two-hour manual effort of digging through PDF statements. The underlying principle here is that commingled deposits are a red flag for any audit of surcharge accounting. Processors issue separate tax documents for surcharge collections in some jurisdictions, and your bank deposit schedule should be able to trace back to the individual transaction level. If it cannot, you have a compliance gap.
State Law and Network Rules Are a Separate Problem
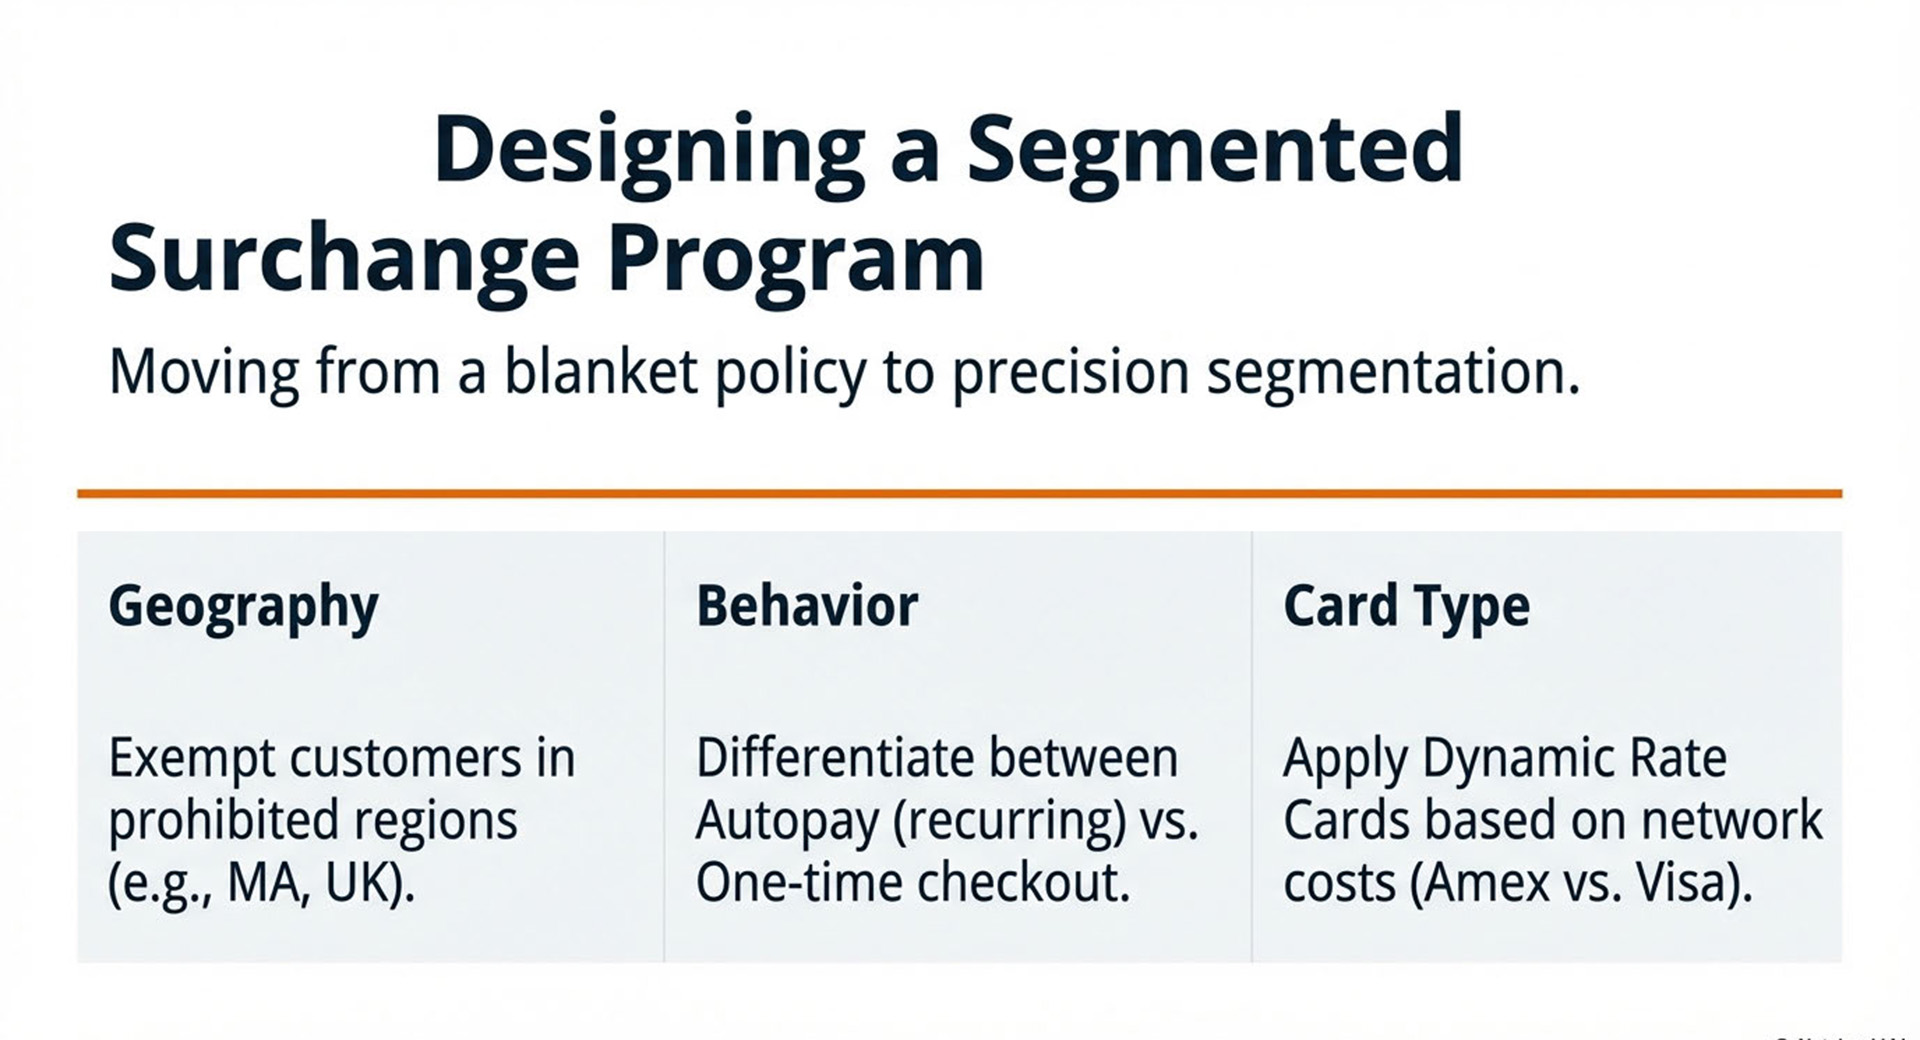
GAAP compliance and legal compliance are not the same thing. You can have perfect journal entries and still be operating illegally in your state. Eight states prohibit credit card surcharges entirely: Colorado, Massachusetts, Connecticut, Kansas, Maine, New York, Oklahoma, and Texas. California allows them but with stricter caps than the federal 3% ceiling. Even within states where surcharging is legal, the Visa and Mastercard rules require specific disclosure at the point of sale, both in-store and online, and they vary slightly by network. If you process surcharges in a restricted state, the accounting treatment becomes irrelevant because you are exposing the business to network fines and potential regulatory action. I would recommend running a state-by-state legal review before restructuring your chart of accounts for surcharge tracking. The fix for a legal problem is never a better spreadsheet.
What Happens at Tax Time
Sales tax treatment of surcharges varies by state. Some states consider surcharges taxable as part of the sales price. Others treat them as nontaxable reimbursements. This is a state-specific determination that your CPA needs to make based on your jurisdiction, not something you can derive from GAAP guidance alone. Getting this wrong means either over-collecting and creating a liability or under-collecting and owing back taxes plus penalties. The same applies to income tax. Since you are netting the surcharge against expense rather than recognizing it as income, your taxable gross is the sale amount only. If you booked the surcharge as revenue, you would be inflating your gross and potentially paying more in state and local taxes than necessary.
When Netting Is Not the Right Approach
There are scenarios where you should record the surcharge as separate revenue instead of netting it against expense. If your surcharge exceeds your actual processing cost, the excess portion is not a reimbursement. It is income. In that case, you split the entry: the portion equal to your discount fee goes to contra-expense, and the remainder goes to a surcharge revenue account. This usually happens when you are charging the maximum allowed 3% surcharge but your actual processor discount rate is only 1.8%. Another scenario is if you operate in a industry segment where the surcharge is considered a distinct service fee rather than a cost pass-through. This is rare for standard retail but more common in B2B transactions where the surcharge is presented as a financing fee. The distinction matters for revenue recognition under ASC 606 because it affects whether the surcharge is part of the transaction price or a separate performance obligation.
Practical Tracking Recommendations
Whatever approach you choose, make sure your accounting system can generate a monthly report that shows surcharge collected, surcharge remitted to processor, and the net impact on your discount expense. This report is what you will hand to your auditor and what you will need if you ever face a processor audit or a state tax inquiry. A simple trial balance excerpt is not sufficient documentation. Integrate the surcharge data directly into your general ledger rather than tracking it in a separate spreadsheet. The spreadsheet will eventually get out of sync with the GL, and you will lose the audit trail. If your ERP does not natively support surcharge tracking, use a dedicated payment reconciliation tool that exports directly to your accounting system. The monthly close should not require manual reconciliation of surcharge data across three different files.
Where This Approach Breaks Down
The net-against-expense method works cleanly for standard card-present and card-not-present retail transactions. It breaks down quickly if you deal with chargebacks, refunds, or partial refunds on surcharged transactions. When a customer returns a $100 item that included a $3 surcharge, you need to refund both the purchase price and the surcharge. The journal entry reverses both sides simultaneously. If your system only refunds the net deposit amount, you are either over-refunding the customer or absorbing the surcharge cost yourself. Both outcomes are worse than the correct approach of reversing the full original entry. Another limitation is that the netting approach obscures the true cost of payment processing. If you are comparing processor quotes or evaluating whether to accept cards at all, the net expense figure does not tell you your actual discount rate. You need to maintain a separate calculation of the gross processing cost before the surcharge offset for decision-making purposes. The income statement figure is for financial reporting. The operational figure is for management analysis. Do not conflate them.