What GASB 75 Actually Requires You to Do
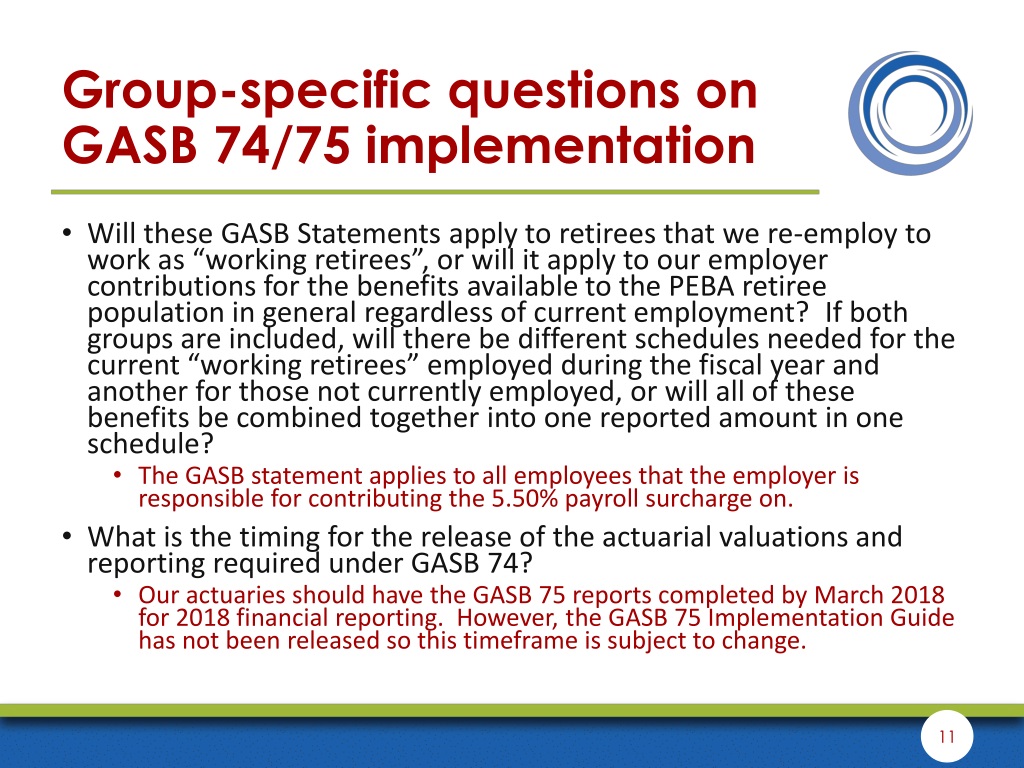
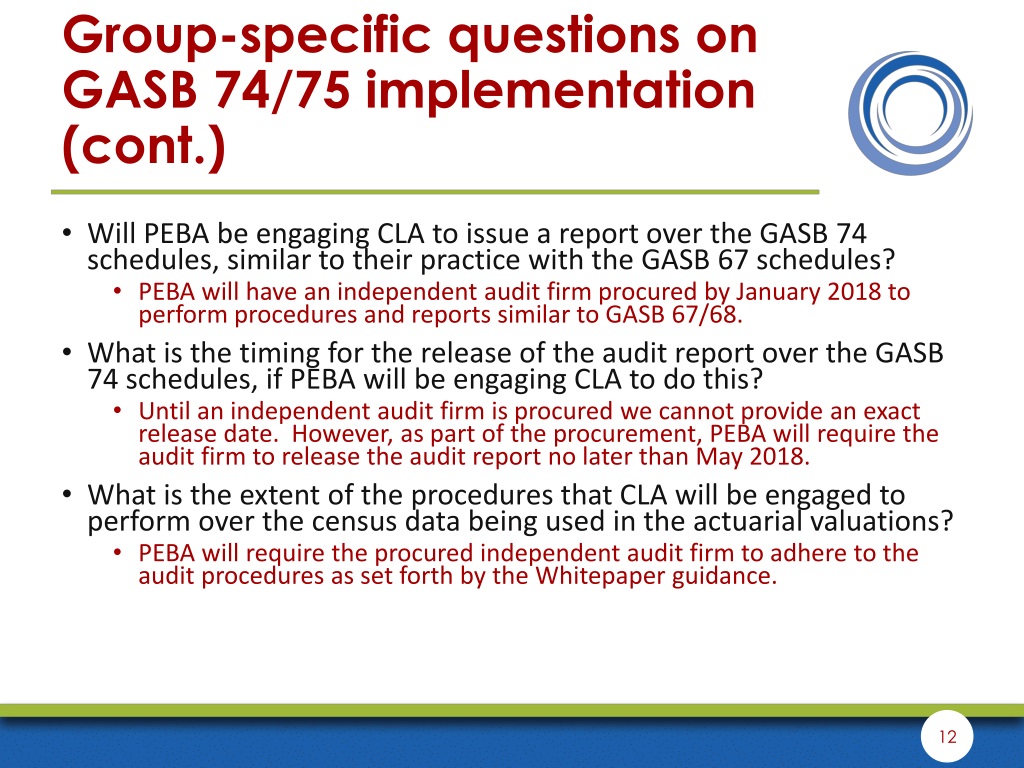
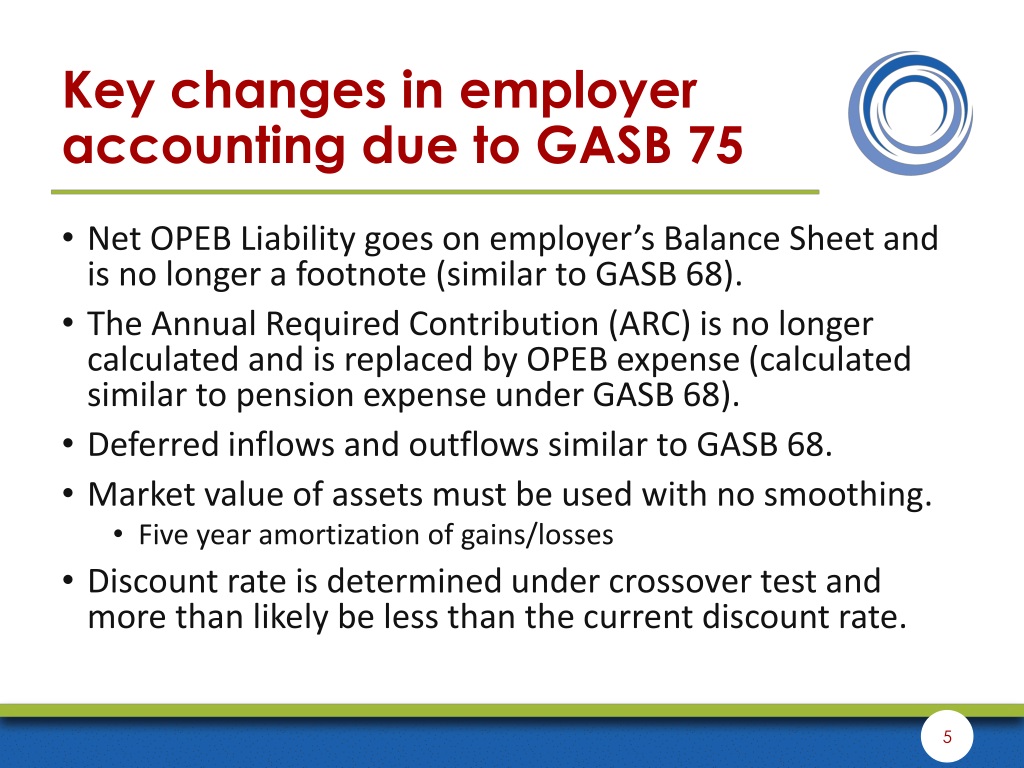
GASB Statement 75 changed how state and local governments report OPEB liabilities. Unlike GASB 67 for pensions, which had a phased rollout, GASb 75 Implementation Guide requirements landed in FY2017 and they were not gentle. The standard forces employers to recognize the net OPEB liability on the face of their financial statements, use actuarial valuations, and apply discount rates tied to municipal bond indices. Most plans don't have the infrastructure for that from day one. I spent two fiscal years implementing this. The first cycle was brutal. Here is what actually happened. The implementation starts with the plan design inventory. You need to catalog every benefit, every eligibility rule, and every funding mechanism your jurisdiction operates. I learned this the hard way when we had a standalone healthcare subsidy program that wasn't formally documented in any plan document. It was buried in a municipal code section that predated the modern health plan. If you miss that, your Actuarial Assumed Rate of Return and your liability calculation will be wrong, and your auditor will catch it during the financial review.
The discount rate is where most people stumble. GASB 75 uses a single discount rate methodology. If your plan is fully funded, you use the expected rate of return on plan investments. If it is not, you blend the expected long-term investment return with the municipal bond index rate. That blend changes every year based on your funding status. We used GFOA modeling tools initially, but the spreadsheet-based approach created version control nightmares. I switched to a dedicated actuarial software integration that pulls directly from our pension actuarial vendor and pushes the output straight into the financial statement schedule. That cut our annual processing from roughly three weeks to about four days, excluding the actuarial valuation itself. Employer contributions after the measurement date are a minefield. GASB 75 requires you to adjust for contributions made between the measurement date and the end of the fiscal year. If you do not account for these, your liability gets overstated. I have seen multiple entities miss this entirely because their payroll system runs on a different schedule than their fiscal year. We built a reconciliation routine that maps contribution payments to the exact measurement period and flags any payment made outside the window. It catches errors before they reach the audit stage.
Common Mistakes That Will Cost You
The actuarial assumptions are not suggestions. They must be reasonable and supportable. I watched a city use a 7 percent expected return without a documented investment policy that justified it. The auditor rejected it. They had to go back, hire a new actuary, and restate the liability. That added six months to the reporting timeline and roughly $200,000 in professional fees. Another issue is the treatment of non-employer contributing entities. If a higher-level government or another agency contributes on behalf of the primary employer, GASB 75 requires you to report those contributions separately. Many jurisdictions lump everything together. The financial statements become a mess, and the notes to the financial statements do not reconcile with the actuarial valuation. I keep a contribution mapping table that tracks every dollar to its source entity. It takes about an hour per quarter to update, but it prevents three days of restatement work during audit season. The measurement date is fixed. It is the last day of the prior fiscal year. You cannot shift it to align with your plan year or your budget cycle. If your plan year ends June 30 and your fiscal year ends September 30, you are stuck with a September 30 measurement date regardless of what makes logistical sense. This creates a timing mismatch with your benefit data. I learned to pull actuarial data at least thirty days before the measurement date so we can interpolate any changes. Waiting until after the measurement date introduces unnecessary variability into the liability calculation.
Get the Full Details
What the Standard Does Not Cover Well
GASB 75 Implementation Guide guidance is thorough on the core calculations but thin on multi-employer plan coordination. If you participate in a regional health benefit pool with multiple member jurisdictions, the reporting gets complicated quickly. Each employer must report its own proportionate share, but the pooled plan may not break down costs by participant in a way that satisfies GASB 75 disclosure requirements. We solved this by negotiating a quarterly cost allocation report from the pool administrator. It is not perfect, but it gives us the granularity we need for footnote disclosures. Small employers face a disproportionate burden. The actuary minimum fee for a standalone GASB 75 valuation runs anywhere from $8,000 to $25,000 depending on complexity. A municipality with fewer than five active participants is paying the same flat-rate valuation as a system with five hundred. There is no scaled pricing built into the standard. I have recommended that smaller jurisdictions share actuarial resources through a joint powers authority. It reduces per-entity cost and ensures consistent methodology across participating employers. Post-retirement life insurance benefits under Section 115 trusts add another layer of complexity. The tax exemption on investment earnings creates a favorable environment for plan growth, but it also means the trust assets are tracked separately from general government funds. The discount rate for a Section 115 trust uses the same blended methodology, but the contribution patterns are often irregular. Beneficiaries may elect lump-sum payouts or annual premiums, and those elections affect the projected benefit stream. We built a beneficiary election tracker that feeds directly into the actuarial model. Without it, the liability projection assumes static elections that rarely match reality.
A Practical Implementation Checklist
Here is what I do every cycle, and it usually takes about two weeks of focused work if nothing breaks. First, confirm the measurement date and lock it in your planning calendar. Second, pull the prior year actuarial valuation and verify the assumptions against your current investment policy and demographic experience. Third, map all employer and non-employer contributions to the correct period. Fourth, run the discount rate calculation with the current municipal bond index data from the Federal Reserve. Fifth, reconcile the net OPEB liability with your general long-term liabilities schedule. Sixth, draft the footnote disclosures using the exact language GASB 75 requires. Do not paraphrase. Auditors check for exact compliance. If you are starting from scratch, do not attempt a DIY valuation. The standard requires a qualified actuary, and any valuation not signed by one is worthless for reporting purposes. Budget for the actuarial engagement early. The market fills up fast between January and April. I have seen jurisdictions stuck waiting until May because they delayed the engagement, and missing the audit deadline is not a defensible position.
The financial statement impact can be material. A mid-sized city with a partially funded health plan might see a net OPEB liability appear on the balance sheet for the first time, measured in tens or hundreds of millions of dollars. It does not affect cash flow, but it affects debt covenants, credit ratings, and statutory compliance. Treat it with the same seriousness as a pension liability. It is just as real.
Where the Process Actually Breaks Down
Data integrity is the weakest link. GASB 75 depends on accurate employee census data, including retirement dates, salary levels, and benefit elections. Many jurisdictions discover mid-cycle that their HRIS system has not been reconciled in three years. Retired employees who died years ago are still showing as active beneficiaries. New hires without proper benefit enrollment are missing from the participant list. The actuary will flag these, but fixing them requires coordination across human resources, payroll, and benefits administration, and that coordination is slow. The annual component of cost calculation is another area where assumptions drive big swings. A one-half percent change in the discount rate can alter the reported liability by millions. I recommend sensitivity analysis that shows the liability range across a band of reasonable discount rates, not just the single best estimate. It gives stakeholders a clearer picture of the uncertainty involved. The standard does not require it, but it prevents panic when the rate shifts slightly from one year to the next. There is no official free template from GASB for the implementation. The official standards documents are dense and written for actuaries and financial reporters. Some consulting firms sell implementation toolkits, and a few state associations publish their own guides. I found the Texas Comptroller's OPEB handbook and the GFOA practice notes the most useful. They are free and practical. The GASB implementation guide itself is available on the GASB website, but it reads like a legal document. Use it as a reference, not as a step-by-step walkthrough.
One last thing. The transition disclosure requirements are strict. If this is your first year of adoption, you must restate prior comparative information. That means recalculating last year's liability using the GASB 75 methodology and presenting it alongside the current year. It is work, but it is required. Skipping it is an audit qualification waiting to happen. I budget two weeks for the restatement work and assign it to someone who understands both the actuarial output and the governmental accounting framework. Trying to do it alone while also managing the current cycle is a recipe for mistakes.