So You Need to Actually Implement GasB 87
GasB 87 is the government accounting standard for leases that took effect for reporting periods beginning after December 15, 2021. If you're working with municipal or state-level entities, you've probably already felt the headache. The requirement is straightforward on paper: put every lease where the government controls the use of identified property, plant, or equipment on the balance sheet as both a right-of-use asset and a lease liability. The catch is that "straightforward" assumes you have clean data, and most governments don't. The official guidance document broke down into clear sections - scope, measurement, classification, and disclosure. But reading the standard alone won't save you when you hit the practical problems. The measurement rules require discounting future lease payments at the rate implicit in the lease or, if that's not determinable, the government's incremental borrowing rate. For most mid-sized municipalities, finding a clear implicit rate is nearly impossible because lease contracts rarely spell it out. You end up building your own rate assumption, which audit teams will immediately question. Classification matters too. Short-term leases under twelve months get an exception, but "short-term" means something very specific and your legal department probably hasn't been distinguishing between lease terms and renewal options the way the standard requires. That's where most of the initial pushback comes from during implementation.
Practical Steps That Actually Work
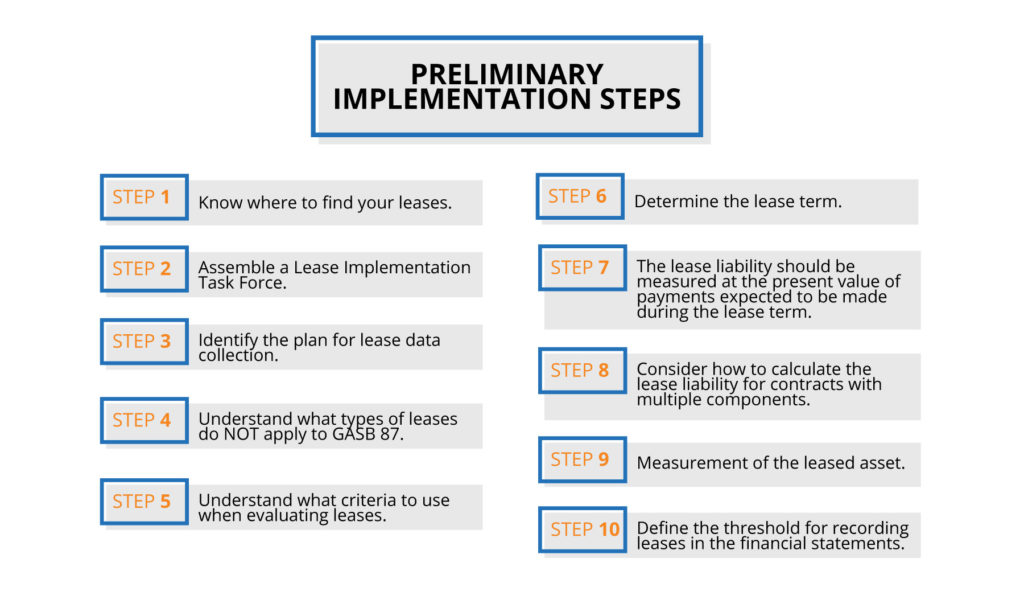
Start by pulling every contract that could possibly qualify as a lease. I've seen teams miss vendor agreements for IT equipment, snow removal services with dedicated equipment, and even certain construction arrangements that technically meet the definition. Your first task is compiling a complete lease schedule, which sounds simple until you realize some of these contracts are buried in procurement systems, filed under different departments, or written in plain language that doesn't scream "lease." Once you have the schedule, you need to extract the key data points from each contract: lease term, payment amounts, payment dates, escalation clauses, and any residual value guarantees. Build a standardized template for this. I used a spreadsheet with columns for contract number, counterparty, asset description, commencement date, termination date, payment frequency, annual payment amount, escalation percentage, and discount rate assumption. It took about three weeks to get through a typical mid-sized municipality's full portfolio. For the discount rate, pick your incremental borrowing rate and apply it consistently across the portfolio unless you have a reason to deviate. Document that decision clearly. Auditors expect a single, well-reasoned approach more than they expect you to chase individual implicit rates for every contract.
Edge Cases That Will Trip You Up
Here's something the standard doesn't make obvious: lease modifications. When a government renegotiates rent, extends the term, or adds space, that's a lease modification under GasB 87, and you have to remeasure the liability. I ran into this when a county renegotiated its fleet lease mid-year. The original lease had a 12 percent escalation clause baked into the payments. During the modification, they reduced the annual payment but extended the term by two years. If you just plug the new payment amount into the old schedule, your liability number will be wrong. The correct approach is to remeasure using the remaining lease term at the modification date, apply the current discount rate, and recalculate both the asset and liability from scratch. Take it from someone who learned that the hard way during an audit review - the modification handling section is where most implementation errors surface. Another tricky area is lease versus service contracts. A maintenance agreement for a building HVAC system is usually a service contract. A lease of the HVAC system itself is different. The line between them gets blurry when the vendor provides both installation and maintenance in one contract. My workaround was to pull the contract language apart section by section and tag each clause separately. If the government has the right to direct the use of specifically identified equipment, it's a lease component. Everything else might not be. Document the analysis, don't just decide and move on.
Get the Full Details

Common Pitfalls to Avoid
The biggest mistake I see is starting the implementation too late in the fiscal year. GasB 87 requires restating comparative periods, which means you need to go back and apply the standard to prior year financials if you're presenting full comparative statements. If you wait until spring to begin, you'll be working backward through twelve months of data while also preparing current-year numbers. That timeline almost never works out cleanly. Another issue is treating the right-of-use asset as a depreciable fixed asset without considering the lease structure. Some governments just amortize the asset straight-line over the lease term. That's fine for most operating leases, but if the lease transfers ownership or contains a bargain purchase option, the asset should be depreciated over its useful life, not the lease term. Misclassifying that difference will show up in your depreciation schedule and throw off your expense recognition for the entire lease life. Data quality is the unglamorous bottleneck. You will encounter contracts where the payment amount changes every few years due to escalations tied to an index you can't easily verify. I've used reasonable estimates based on historical CPI data when the contract language was ambiguous, but you need to document the assumption and be prepared to defend it. Audit teams won't accept "we guessed" as an answer, even though that's exactly what happened half the time.
Disclosure Requirements
The disclosure section is where GasB 87 gets tedious. You need to report the weighted average discount rate, maturities of lease liabilities, and significant terms and conditions. The maturity schedule should break down payments by year for the next five years and then in total for years beyond that. Make sure your schedule reconciles to the total liability on the balance sheet. I've seen mismatches of a few thousand dollars that seemed trivial until the auditor flagged them as evidence of sloppy work across the entire implementation. There's also a requirement to disclose finance leases separately from operating leases, though under GasB 87 most government leases are classified as operating. If you have any leases that meet the finance lease criteria - transfer of ownership, bargain purchase option, lease term covering substantially all of the asset's life, or present value of payments reaching substantially all of the fair value - those need different treatment in the notes.
What the Guidance Gets Wrong
The standard assumes a level of contract centralization that simply doesn't exist in most local governments. Departments operate independently, procurement processes are fragmented, and lease documents live in different systems or physical folders. The implementation guide acknowledges this but offers limited practical advice on how to gather the data at scale. If you're working with a city that has fifty departments each managing their own equipment leases, plan for significant coordination effort. The discount rate guidance is another area where theory and practice diverge. The standard says to use the rate implicit in the lease when readily determinable, otherwise use the government's incremental borrowing rate. In practice, very few government leases have a readily determinable implicit rate, and the incremental borrowing rate varies by maturity and credit profile. Pick a single blended rate if it's reasonable for your situation, but be consistent and document why. Some large school districts use a portfolio-wide rate based on their bond yield curve. Smaller municipalities often just pick a rate and stick with it. Both approaches work if they're defensible. One final note: if your entity has a large volume of short-term leases that you're exempting under the twelve-month rule, keep a separate tracking log. Exemptions need to be reviewed each period to confirm they still qualify. I know of a county that let twenty-three vehicle leases roll past the twelve-month mark without updating their exemption list. The auditor caught it during the annual review, and they had to restate several line items. A simple quarterly review of exemption eligibility would have prevented that.