Getting GASB 96 right without losing your mind
GASB 96 is probably the simplest standard most government entities will touch in the last decade, and also the one that trips people up the most. The standard itself is straightforward. A subscription based information technology arrangement is just an agreement that gives a government the right to use software or data for a set period. That qualifies as an SBITA. You recognize a subscription liability and an intangible right to use asset on the balance sheet, then amortize over the subscription term. The complexity never comes from the definition. It comes from figuring out which contracts actually fall under the standard and which ones don't, then extracting the right data from systems that were never built to support it.
What Gasb 96 Subscription Based Information Technology Arrangements Actually Means in Practice
The recognition threshold is a subscription with a value of at least $500,000. That triggers the accounting. Everything below that stays off the balance sheet. You might think this is easy to filter, but contract values are messy. A single agreement might have a base fee of $200,000 with add-ons and optional upgrades that push it over the line. The question becomes whether those options are reasonably certain to be exercised. Here is what most people miss. The $500,000 test looks at the subscription payments over the full term, including renewal periods that are reasonably certain to occur. If you have a three year initial term with automatic renewals and a history of always renewing, the full extended term counts toward the threshold. I worked with a mid-sized county that had a contract structured as a one year agreement with mandatory annual renewals. They initially excluded it because the first year was only $180,000. We ended up consolidating the automatically renewable periods and it crossed the threshold at $720,000. Their auditors caught the error during a spot check about eighteen months later, and they had to restate part of their financials. The initial measurement is simpler than it sounds. You calculate the present value of the subscription payments using the government's incremental borrowing rate, or the implicit rate if the vendor tells you what it is. Most SaaS vendors don't disclose an implicit rate, so the incremental borrowing rate is your default. That rate varies by entity and by maturity, so pick something defensible rather than pulling a rate out of thin air.
The practical problems no textbook covers
The hardest part of SBITA accounting is not the math. It is the contract review process and getting reliable data from procurement. I spent about three weeks on a comprehensive SBITA inventory for a regional transit authority last year. They had somewhere around forty IT service agreements on the books. Maybe half qualified. The problem was that their contract management system stored agreements in a shared drive with inconsistent naming conventions. Some were labeled "license agreement," others said "service contract," and a few were just titled with the vendor name and a date. You cannot reliably identify SBITAs by keyword search alone. The workaround I used was to pull a complete vendor payment report for the prior fiscal year, then match each vendor against a list of known subscription providers. Salesforce, ServiceNow, AWS, Microsoft 365, Workday, Workforce Management systems, cloud infrastructure, cybersecurity platforms. Once I had a candidate list, I pulled the actual contract terms for each one and checked for the key indicators: does the government have the right to take possession of the software, is there a defined subscription term, and is there a subscription fee that covers the right to use the specified asset?
Get the Full Details
Ownership and data portability are two areas that confuse people. If the government can take delivery of the software at the end of the subscription term without additional payment, that might push the arrangement into a different classification. If the data has to be reformatted or cannot be extracted in a usable format, the subscription might not meet the definition of providing a right to use a specified IT asset.
How to actually track these after initial recognition
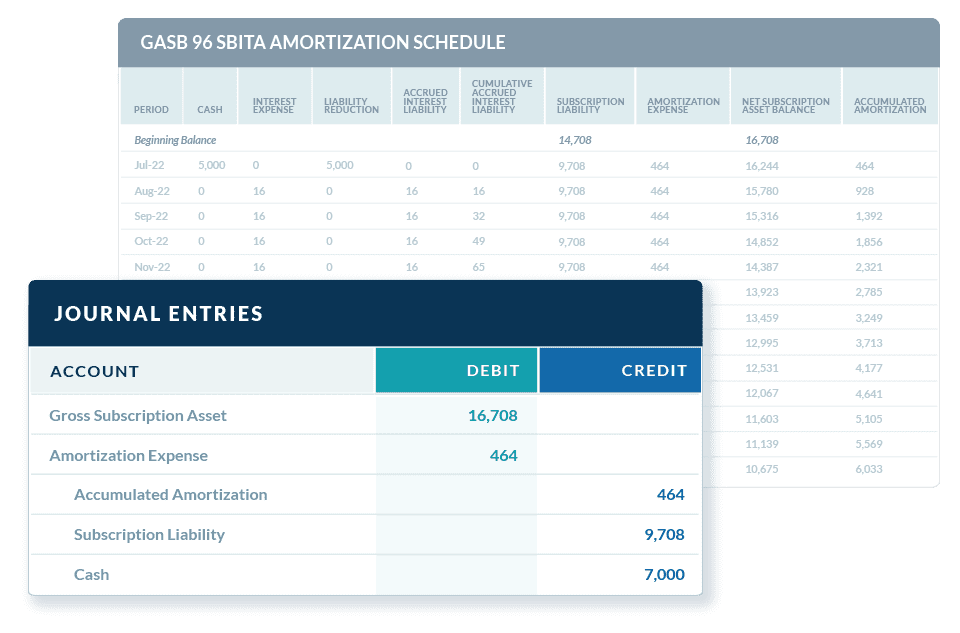
Once you have identified the SBITAs and recorded the initial liability and asset, the ongoing accounting is mostly mechanical. You amortize the intangible asset on a straight line basis over the subscription term. You accrete the liability using the discount rate you applied at inception. The interest expense portion shows up in the statement of revenues, expenses and changes in net position, and the amortization hits the same statement. The part that causes problems is contract modifications. A vendor raises the subscription fee mid-term. They add users. They extend the term. Any of these changes may require remeasurement of the liability and the asset. You recalculate the remaining payments, discount them at the current incremental borrowing rate, and adjust both accounts. The difference between the old and new balances goes through expense in the period of modification. I encountered a situation where a school district renegotiated a student information system contract. The vendor increased the per-student fee and added a new analytics module. The amendment was drafted as a side letter rather than a full contract replacement, which made it easy to overlook during the annual SBITA review. The fee increase alone pushed the remeasured liability up by about $85,000, and the new module had to be evaluated separately to determine if it was a distinct SBITA or just an enhancement to the existing one. We classified it as an enhancement and adjusted the existing asset basis rather than setting up a separate subscription liability. The auditors accepted that treatment after we documented the reasoning, but it took two conference calls and a formal memo to get there.
Where SBITA accounting breaks down
This standard does not solve every problem with IT spending accounting. It only covers subscriptions. Capital purchases of software still get capitalized under other guidance. Maintenance and support fees bundled with a subscription need to be separated out if they are distinct from the right to use the specified asset. If you cannot separate them, you include them in the subscription liability, which overstates the SBITA balance. The biggest structural weakness is that the $500,000 threshold creates a cliff effect. An entity with fifty contracts at $490,000 each recognizes nothing. One contract at $510,000 triggers full balance sheet recognition. This means the standard captures only a fraction of actual IT subscription spending for most governments. It does not reflect the total economic commitment to cloud and software services, which for many entities runs significantly higher than the aggregate SBITA liability would suggest. Another issue is the discount rate. Many small governments do not have a well-documented incremental borrowing rate for every maturity level they might need. Using a placeholder rate introduces measurement error that compounds over time. I recommend maintaining a schedule of rates by term and updating it annually, even if you do not have an active SBITA that requires it in a given year. When the time comes, you will not be scrambling to justify a number.

If your organization has a high volume of smaller IT subscriptions, the most practical approach is to maintain a running log that includes every qualifying and non-qualifying contract, with the dollar threshold and reasoning for exclusion documented. This log saves time during the audit and protects you when contract values fluctuate near the threshold from year to year. Government spending patterns shift. A $480,000 contract this year might become $520,000 next year when renewal pricing kicks in, and without documentation the change looks arbitrary.
A practical step-by-step that actually works
Step one: Pull your complete vendor payment listing for the fiscal year. Exclude one-time purchases and pure maintenance contracts. Keep everything with a recurring component. Step two: For each recurring vendor, obtain the contract and identify the subscription term, the payment schedule, and any renewal or termination options. Pay attention to side letters and amendment documents. Those are where modifications hide. Step three: Apply the $500,000 threshold using the full term including reasonably certain renewals. Record the liability and asset for qualifying arrangements.
Step four: Set up a schedule to track amortization and accretion monthly. Most entities get lazy here and only do it at year end, which makes corrections much more painful. Step five: Review any contract modifications during the year for remeasurement triggers. Update your SBITA log with the revised terms and recalculate the discounted payments. The whole process for a typical mid-size government takes about two to four weeks for the initial identification and measurement work, then roughly four hours per month going forward for tracking and modifications. That is assuming you have your contract documents organized. If they are not, the initial review phase can stretch to six or eight weeks depending on how fragmented your procurement records are.
There is no central database or public filing where you can download a ready-made SBITA schedule. Every entity builds its own tracking model based on its specific contracts. Spreadsheets work fine if you keep them clean, but I have seen too many entities rely on shared files with broken formulas and inconsistent discount rate assumptions. Version control matters more than people realize in this area.
What to watch for next
Implementation has been fairly smooth overall since the standard became effective for fiscal years beginning after June 15, 2021. The main pressure point remains data collection from procurement. A few state oversight bodies have started asking for SBITA disclosures in their routine monitoring reviews, which means entities that treated it as a low priority are now facing questions they are not prepared to answer. Having a documented methodology and a maintained log before anyone asks is the difference between a twenty minute explanation and a two week scramble. The standard also intersects with other reporting requirements. If your government reports under PCAB guidelines or prepares component unit financials, the SBITA treatment may need to be evaluated at that level as well. Not every subsidiary or joint venture will have the same contracts, but consolidating the view across entities is where errors tend to surface.