Why your spreadsheets are lying to you about growth
I spent three years rebuilding a national accounts dataset for a sovereign wealth fund, and the single biggest source of error wasn't in the raw data. It was in how I handled the transition between real and nominal calculations. We caught it when the year-over-year growth rate for a mid-sized economy showed 8.2% in nominal terms, but the real figure came out negative. The discrepancy looked plausible until you traced the chain. It was a deflator mismatch. Some components used a fixed-weight Laspeyres approach while others shifted to chain-weighted. The methodological inconsistency inflated the nominal trajectory and made it look like the economy was booming when prices alone accounted for nearly all of that movement. This is the practical reality behind Gdp Real Vs Nominal that nobody tells you until you've already shipped the wrong report. The definitions sound straightforward, but the implementation has enough edge cases to burn you if you're not careful.
Gdp Real Vs Nominal: How they actually differ in practice
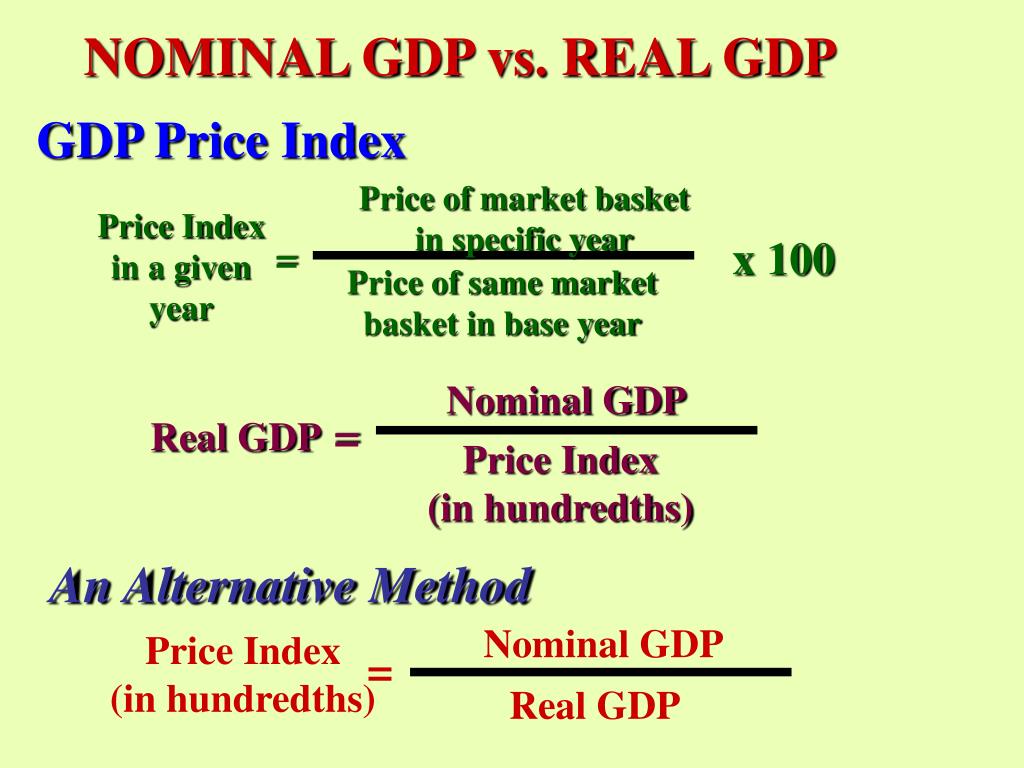
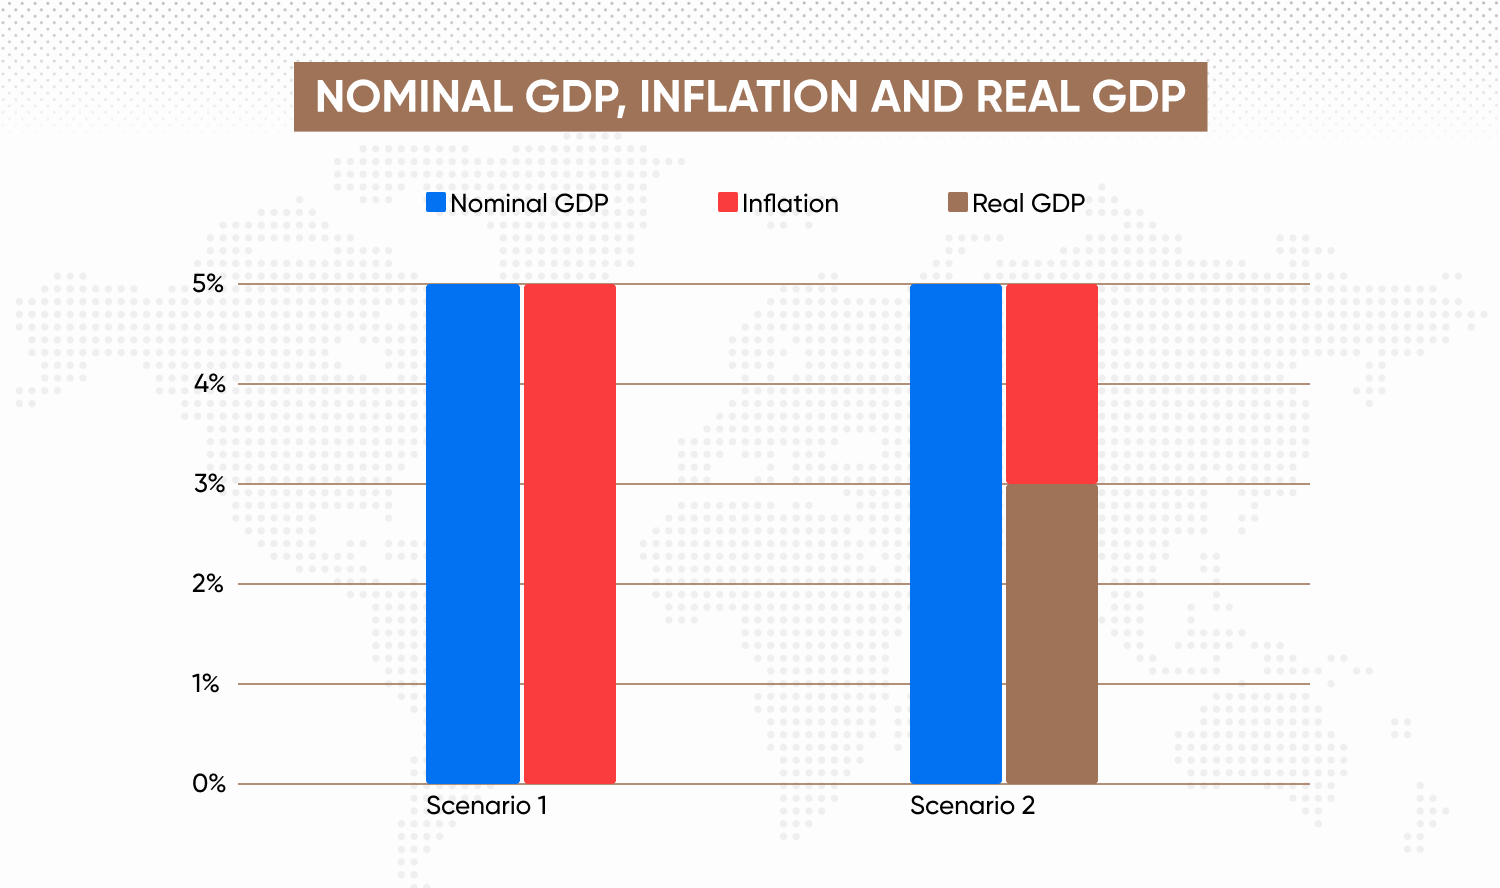
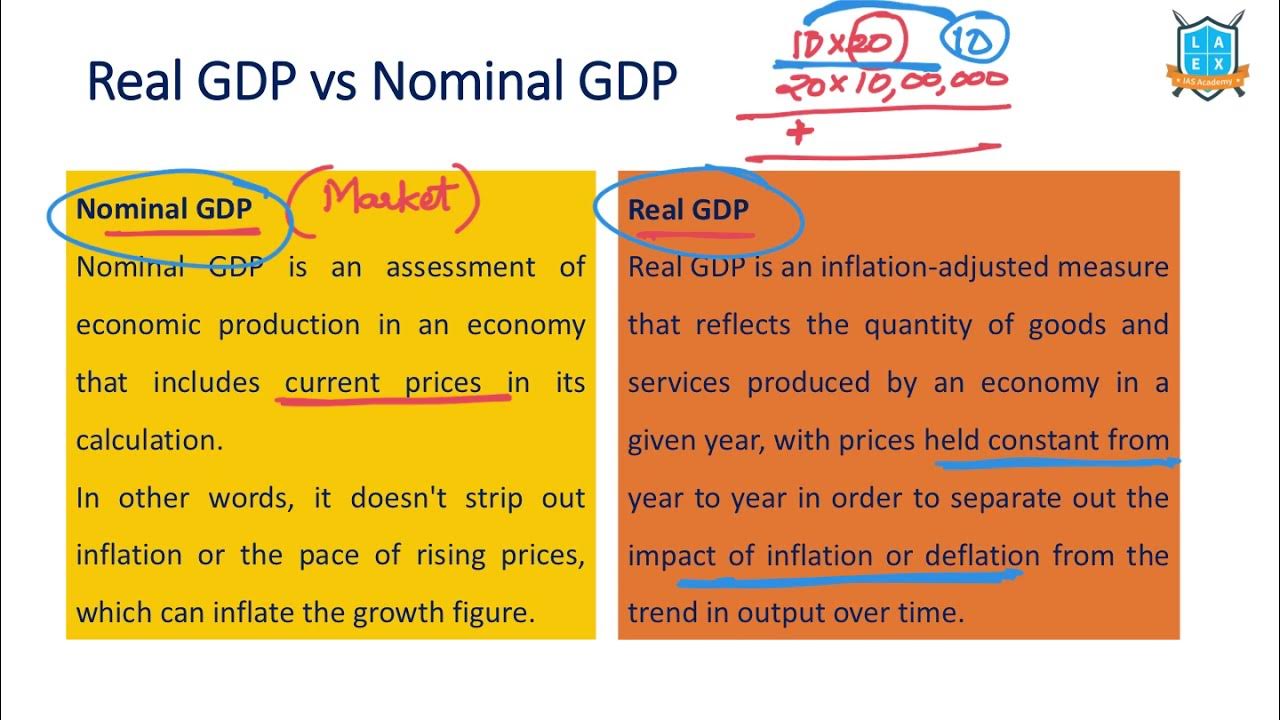
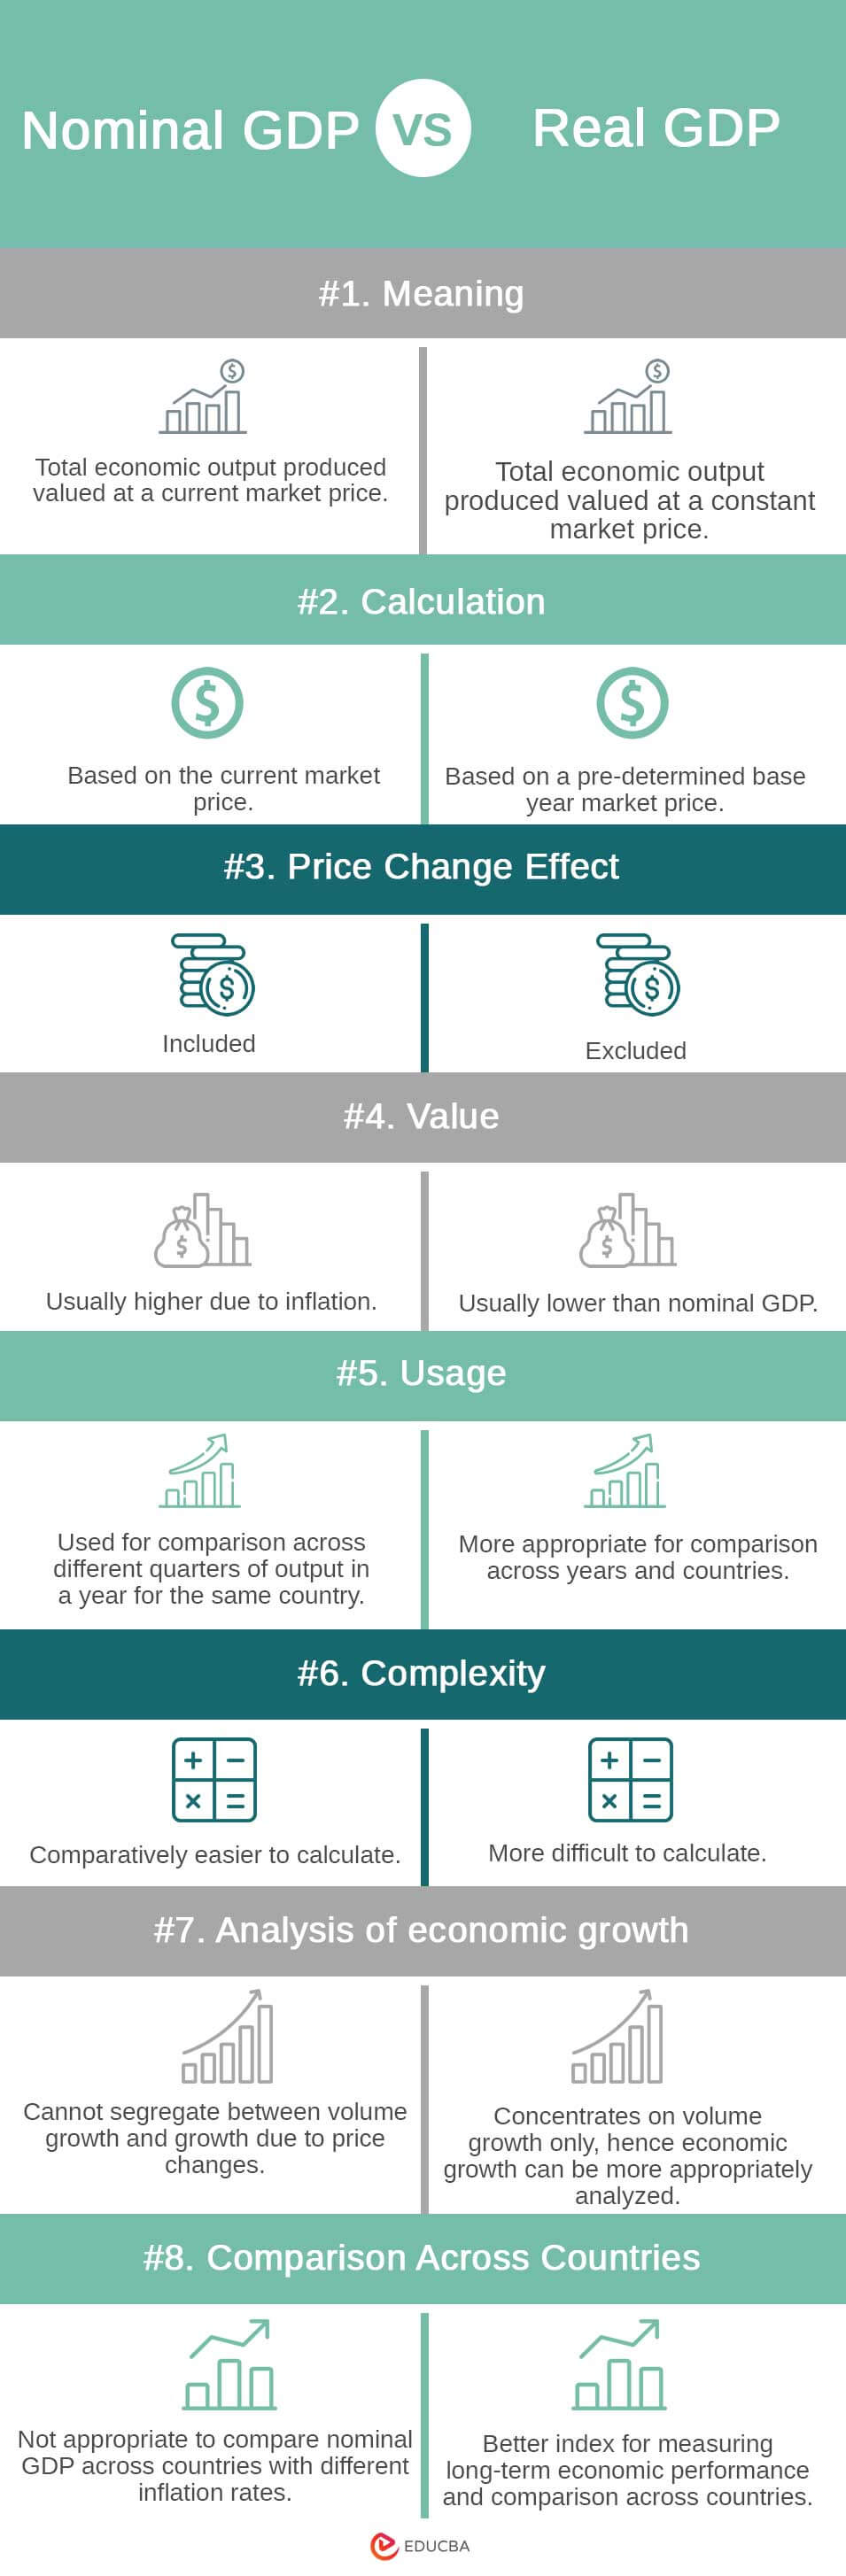
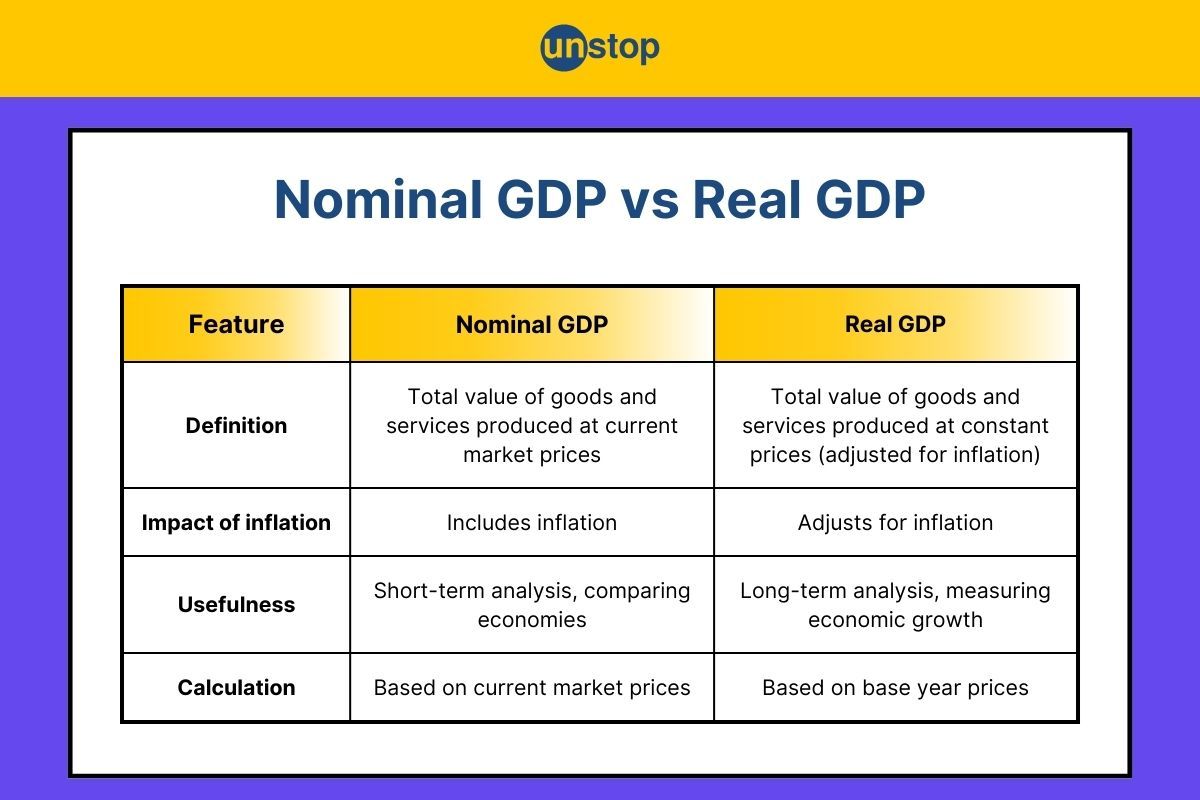
Nominal GDP measures the total value of all goods and services produced in an economy using current market prices. It does not adjust for inflation. If a country produces the same physical output as last year but every price doubles, nominal GDP doubles. Real GDP strips out the price changes by valuing output at a constant set of prices from a base year. The difference between the two numbers is the GDP deflator, which is essentially a broad price index for the entire economy. The deflator is calculated as nominal GDP divided by real GDP, multiplied by 100. So if nominal is 1,200 and real is 1,000, the deflator sits at 120. That tells you prices have risen 20% since the base year. Simple enough on paper. Here's where it gets complicated. Most people think you just pick a base year and go. That was the old method. Modern statistical agencies use chain-weighting now, which updates the base year regularly so the index stays more accurate over time. The United States switched to chained dollars in the mid-1990s. The UK followed. The methodology shift matters because the gap between Laspeyres and chain-weighted figures can diverge over longer periods, especially when relative prices change quickly.
How to compute the conversion yourself
If you need to convert between real and nominal, you need three things: the nominal GDP series, the GDP deflator series, and a consistent base year reference. The formula for deriving real GDP from nominal is straightforward: divide nominal GDP by the deflator and multiply by the deflator's base-year value, which is typically 100. So real GDP equals nominal GDP multiplied by 100, then divided by the deflator. Conversely, to get nominal from real, multiply real GDP by the deflator and divide by 100. The arithmetic is trivial. The difficulty is in sourcing reliable deflators and making sure they match the coverage of your GDP data. I ran into a specific problem with EMDE datasets where the deflator series was published at a different frequency than the GDP series. The GDP was quarterly, available with a two-month lag, but the deflator was only published annually by the central bank. I needed quarterly real GDP for a risk model. My workaround was to interpolate the annual deflator using a quarterly consumer price index series as a proxy, then scale it back to match the annual deflator values at year-end. This preserved the long-run price trend while giving me the quarterly granularity I needed. It introduced some noise in the intermediate quarters, but the error margin stayed within 0.3 percentage points compared to waiting for official quarterly deflators, which often took six to eight months to finalize.
Get the Full Details
Common pitfalls that waste weekends
The most frequent mistake I see is mixing base-year conventions. One dataset uses 2015 as the base year with a deflator normalized to 100. Another uses 2020. If you subtract real GDP from one series against another without rebase adjustment, you'll generate nonsense growth rates. I've seen this in institutional memos where analysts pulled World Bank data and IMF WEO data together without checking the base year alignment. The nominal figures are usually consistent across sources because they're in current prices, but real GDP is entirely dependent on the chaining methodology and base year chosen by each institution. Another trap is using the wrong deflator. The GDP deflator covers the entire economy, but some people substitute the CPI or PCE deflator instead. These measure different baskets. CPI tracks consumer goods and services, which is narrower. PCE is closer but still excludes business investment and government spending components. If you're deflating GDP, use the GDP deflator. Period. There's also the revisitation problem. Real GDP figures get revised. Significantly. The US BEA routinely revises real GDP estimates two to three times in the first year after publication, and sometimes more. A growth rate that looked like 2.1% in the third estimate might come back as 1.4% after the annual benchmark revision. If you're building models that depend on precise historical real GDP levels, lock in the vintage of the data you're using and note the release date. Otherwise your backtests will be looking at figures that didn't exist when the decisions were made.
When real GDP fails you
Real GDP is useful, but it is not a perfect measure of economic wellbeing. It doesn't capture the informal economy, which can be substantial in developing countries. It doesn't account for environmental degradation or resource depletion. It treats all spending as positive output, including reconstruction after disasters. When a hurricane destroys housing and the rebuild adds to GDP, real GDP rises even though welfare clearly fell. For cross-country comparisons, PPP adjustments are often more useful than nominal conversions. The World Bank's International Comparison Program provides PPP-based real GDP figures that account for differences in price levels between countries. A dollar of real GDP in India buys significantly more than a dollar of real GDP in Norway, and nominal conversions through market exchange rates massively understate actual living standards in lower-income economies. But PPP estimates come out every few years and get revised heavily, so they're not great for high-frequency work. If you need a quick way to access standardized datasets, the World Bank's World Development Indicators database at data.worldbank.org has both nominal and real GDP in constant local currency and constant 2015 US dollars. The IMF's WEO database at imf.org/en/Data is another solid source with quarterly frequency and consistent methodology across countries. Both allow you to download the data in CSV or Excel format directly.
The key takeaway is that nominal and real GDP serve different purposes. Nominal is what matters for debt-to-GDP ratios, fiscal multipliers measured in current prices, and anything involving nominal contracts. Real is what matters for growth analysis, productivity measurement, and comparing output across time. Using the wrong one for the wrong job is almost always visible in the numbers if you know what to look for.