Understanding GAAP Through Real Examples
GAAP isn't a single rulebook. It's a messy collection of standards issued by the FASB, SEC requirements, and older AICPA pronouncements that nobody bothered to retire. The examples you find online are often textbook-perfect, which means they're mostly useless for actual work. Here's what it looks like when you're actually applying these principles, not filling in a multiple-choice quiz.
Generally Accepted Accounting Principles Examples in Practice
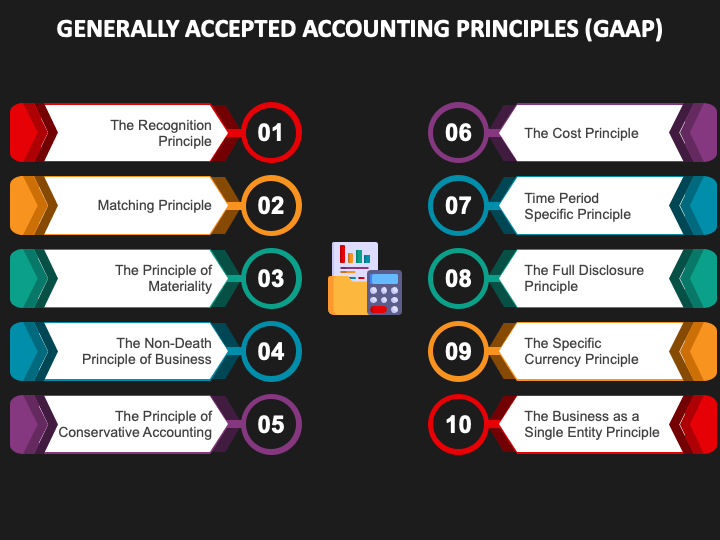
The revenue recognition principle (ASC 606) is probably the most cited GAAP concept, and the one most people get wrong. The five-step model sounds straightforward until you try to apply it to a software company selling annual subscriptions with implementation services bundled in. I worked with a mid-market SaaS firm that had been recognizing revenue ratably over twelve months for everything. Their contract performance obligations included onboarding, the core platform, and premium support. Under ASC 606, those are three separate performance obligations. The fix involved allocating transaction price based on standalone selling prices, which required gathering pricing data from sales records, not just assuming equal splits. This adjustment alone changed their revenue profile significantly in the quarter we caught it. The matching principle is another area where textbooks fall short. It's not a formula. It's the requirement that expenses be recognized in the same period as the revenues they helped generate. In practice, this shows up in inventory accounting, warranty reserves, and prepaid expenses. A common mistake I see is companies expensing large one-time setup costs immediately when they should be capitalized and amortized if those costs benefit future periods. It's a judgment call, and auditors will push back. I've seen one client capitalize $40,000 in implementation costs that were originally expensed, which spread the hit across the contract life instead of taking it all in month one.
Here's a practical walkthrough of a few core GAAP examples you'll actually run into:
Get the Full Details
Common GAAP Principles with Concrete Scenarios
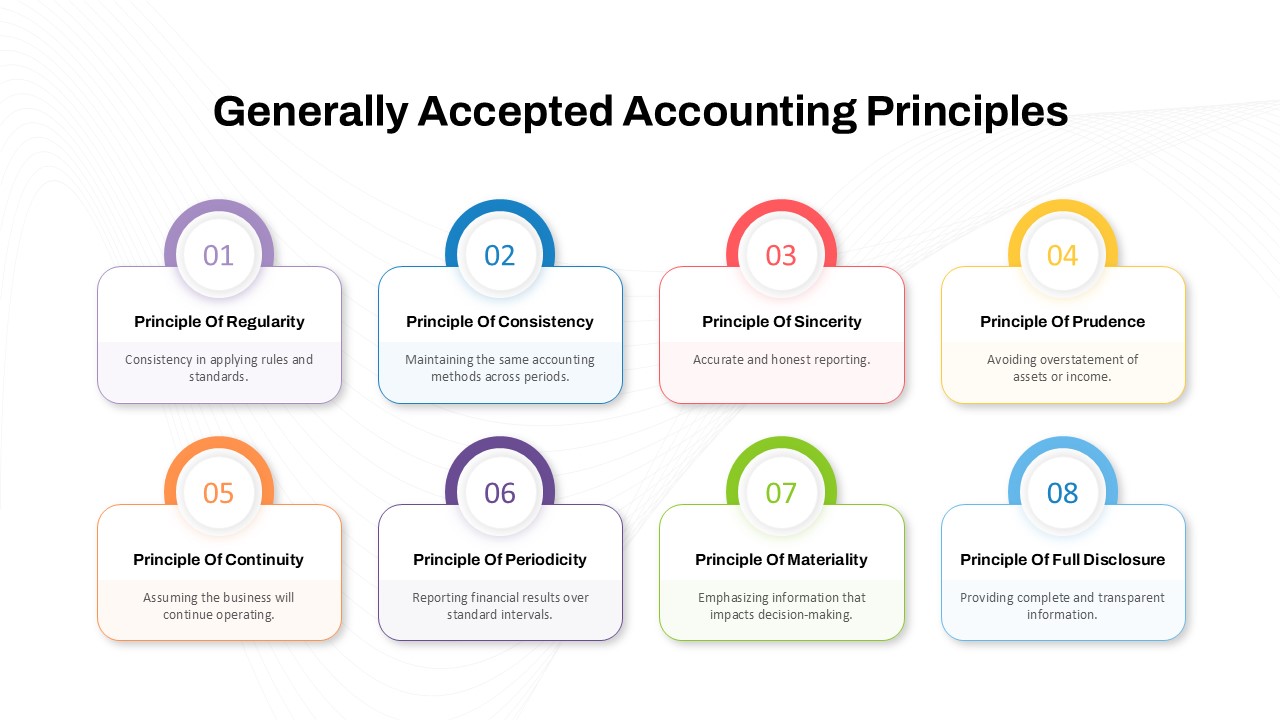
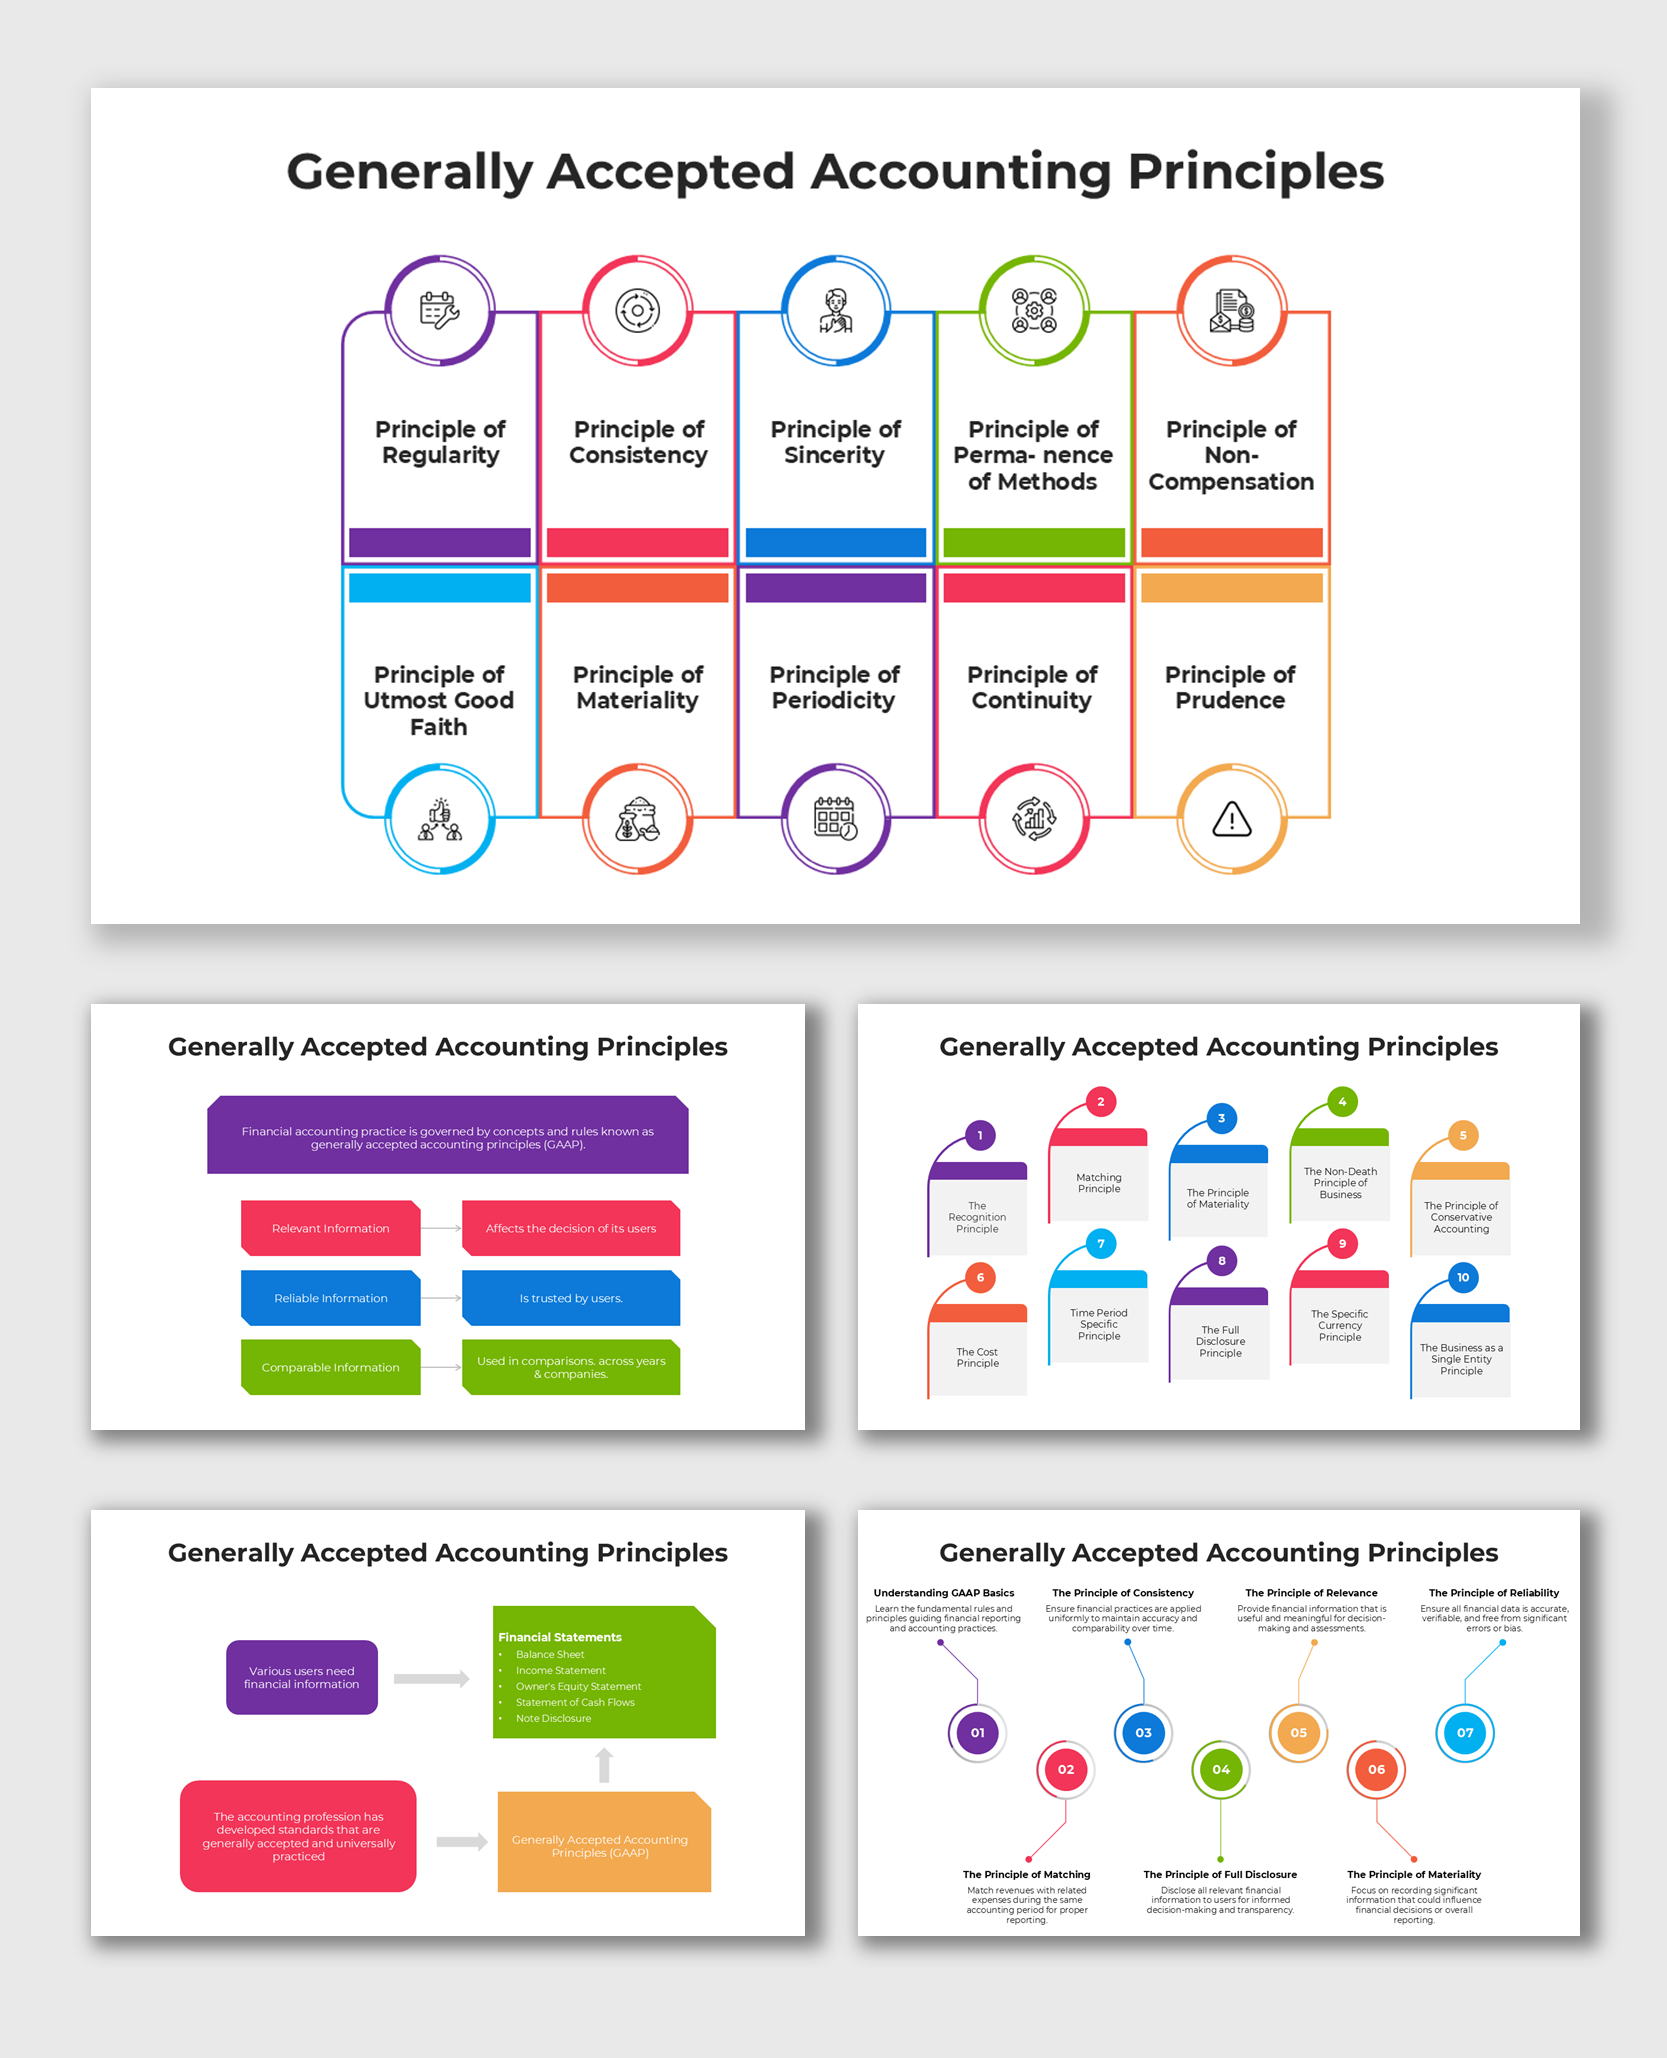
Full Disclosure Principle: Every financial statement needs footnotes. Real example — a company carries $2 million in pending litigation. The outcome is uncertain, but there's at least a reasonable possibility of an adverse ruling. GAAP requires disclosing the nature of the litigation, an estimate of potential loss, or a statement that such an estimate can't be made. I had a situation where management wanted to omit this because they felt confident they'd win. The auditor wouldn't sign off without it. The footnote went in, and the client learned that confidence doesn't override disclosure requirements. Consistency Principle: If you use LIFO for inventory this year, you can't switch to FIFO next year without justification and disclosure. The problem is that companies sometimes change methods subtly — altering depreciation lives or switching cost allocation bases without formally changing the method. This creates comparability issues across periods. I found this in a manufacturing audit where the prior year used direct labor hours for overhead allocation and the current year switched to machine hours without restating comparatives. The fix was to restate the prior year using the new allocation base or add a detailed footnote explaining both methods side by side. Prudence (Conservatism): This one gets misunderstood. GAAP doesn't want you to intentionally understate assets or overstate liabilities for no reason. It means that when faced with uncertainty, choose the option less likely to overstate net assets. Common application: recording inventory write-downs when market value falls below cost, but not writing up inventory when market value rises. I once reviewed a company that was writing down inventory aggressively during a downturn and then not recognizing the reversal when prices recovered in the next period. Under US GAAP, you can't reverse LIFO or cost-method inventory write-downs. That limitation trips up a lot of people who are familiar with IFRS, where reversals are allowed.
The Going Concern Assumption — Where It Gets Messy
The going concern assumption means you're preparing financials as if the business will continue operating. The moment it doesn't, everything changes. Asset valuations, depreciation schedules, classification of long-term debt — it all shifts. I reviewed a small manufacturing company that hadn't updated its financial statements in fourteen months. They were technically insolvent, with current liabilities exceeding current assets by 3x. Their CPA was still issuing going concern opinions without a qualifier. When I dug in, the reality was that their primary customer had gone bust three months prior, they had no access to credit, and their only viable path was Chapter 11. The financial statements should have been prepared on a liquidation basis. The auditor needed to modify the opinion. This is the kind of situation where GAAP examples from a textbook don't prepare you — you just need to know when the assumption has broken down and what to do about it.
Objectivity and Verifiability in Daily Work
These two principles are the reason your work paper matters more than your conclusion. An estimate for bad debt allowance might be the same number whether you derived it from historical percentages or your gut feeling. But only one of those approaches is verifiable. The second one falls apart under audit. I've spent more time reconstructing estimates than I have making original ones. A former employee at a client company had been adjusting the reserve for sales returns based on "recent trends" without documenting what those trends were or how they differed from historical averages. When the auditor asked for the supporting analysis, it didn't exist. We spent three days pulling transaction data to recreate a defensible calculation. The final number was within 5% of what they had originally reported, but the process exposed a systemic issue with how they were tracking returns.
Common GAAP Examples Every Accountant Should Know Cold
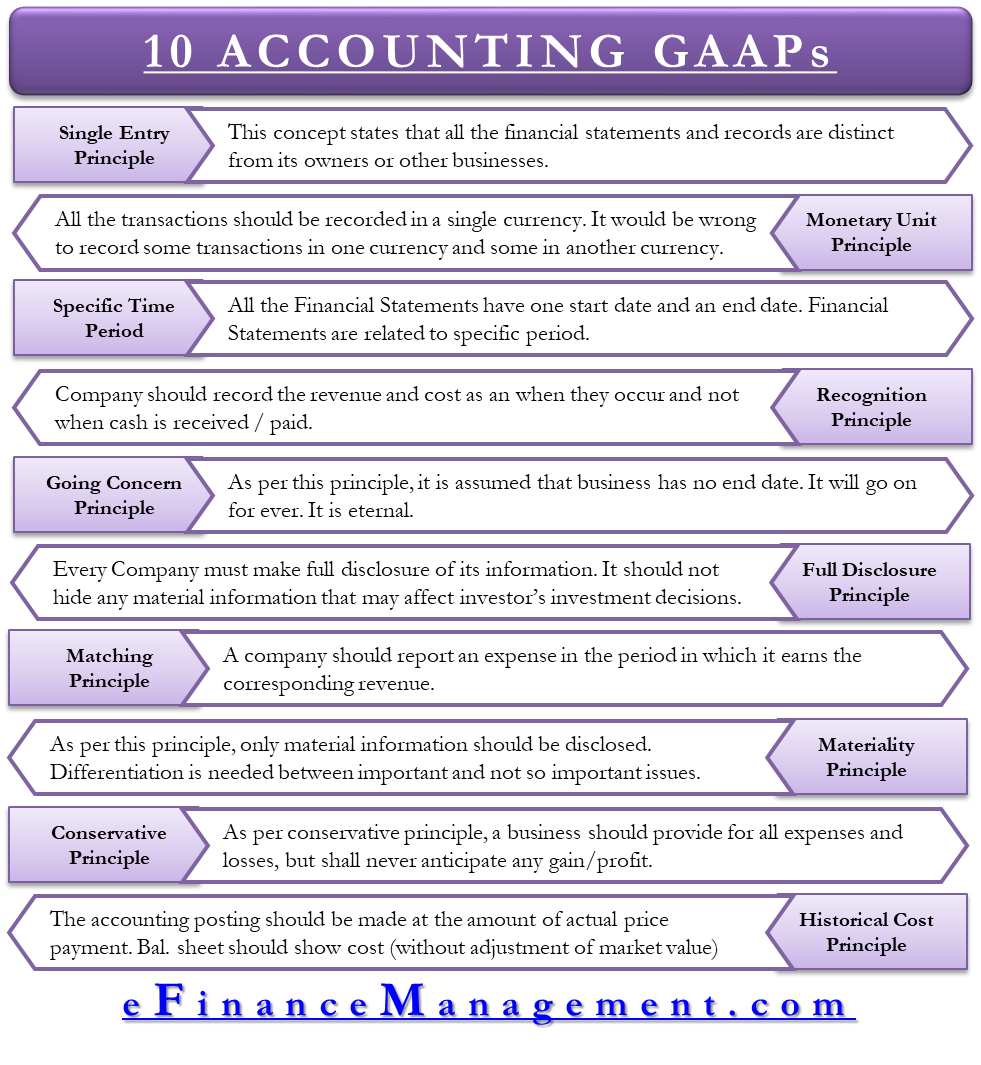
Time Period Assumption: You divide the ongoing business into reporting periods. The practical implication is that you accrue revenues and expenses regardless of cash flow timing. Revenue earned in December but collected in January belongs in December's income statement. This is basic, but I still see companies miss accrued revenue on completed projects at quarter-end because the invoice hasn't been sent yet. Budget Constraint: Financial resources are finite. This principle shows up in impairment testing. If a company has a machine with a carrying value of $500,000 but the recoverable amount — the higher of fair value less costs to sell or value in use — is only $320,000, you must recognize an impairment loss of $180,000. The budget constraint is what drives the write-down. There's no point carrying an asset above what it can generate or realize. Materiality: This is both a principle and a filter. Information is material if its omission or misstatement could influence economic decisions. The problem is that materiality is contextual. $10,000 might be material for a small nonprofit with $200,000 in annual revenue and irrelevant for a Fortune 500 company. I use a rough benchmark of 5% of pretax income as a starting point, then adjust based on qualitative factors. A misstatement that turns a loss into income is material regardless of dollar size.
Pitfalls That Trip People Up
GAAP compliance isn't hard because the rules are obscure. It's hard because the exceptions are numerous and the guidance is fragmented across multiple ASC topics. Here are the mistakes I see repeatedly: Revenue is recognized too early. The collectibility threshold under ASC 606 is often glossed over. If it's not probable that you'll collect the consideration, you don't recognize revenue — even if the performance obligation is satisfied. I worked with a construction company that booked $1.2 million in revenue on a project where the customer had a documented payment dispute. The revenue had to be reversed, and the adjustment hit their debt covenants. Lease accounting is handled incorrectly. ASC 842 required almost every lease to appear on the balance sheet, but the implementation was rough. Companies struggled with discount rate selection, lease term determination, and separating lease components from non-lease components. One client had nearly 200 vehicle leases scattered across subsidiaries. Consolidating the data and determining the embedded rates took six weeks. The initial disclosure was incomplete, and the restatement was required.
Related-party transactions aren't properly disclosed. This is a compliance trap. Transactions with affiliates, management, or entities owned by insiders must be disclosed with specifics about the nature of the relationship and the dollar amount. I found a client who had a significant equipment purchase from a company owned by the CEO's spouse. It wasn't disclosed in any footnote. The correction required restating prior periods and adding extensive disclosures.
When GAAP Isn't the Right Framework
Not every entity needs GAAP financials. Small private companies sometimes use tax basis or an other comprehensive basis of accounting (OCBOA), which can be simpler and more appropriate. I've recommended OCBOA for family-owned businesses where the financial statements are primarily for internal use and a few lenders. GAAP compliance can add significant cost for little incremental benefit in those situations. IFRS is another option for multinationals, but switching isn't trivial. The two frameworks differ on inventory valuation (LIFO is banned under IFRS), development costs (capitalized under IFRS, expensed under GAAP), and lease classification. If you're comparing against international peers, IFRS may be necessary, but don't adopt it just for the sake of it. The principles themselves don't change much between versions. What changes is the complexity of the transactions they're applied to. New business models — subscription services, digital assets, carbon credits — keep creating scenarios where the existing guidance needs interpretation. That's where experience matters more than memorizing examples.