Working With Laplace Transforms on Differential Equations
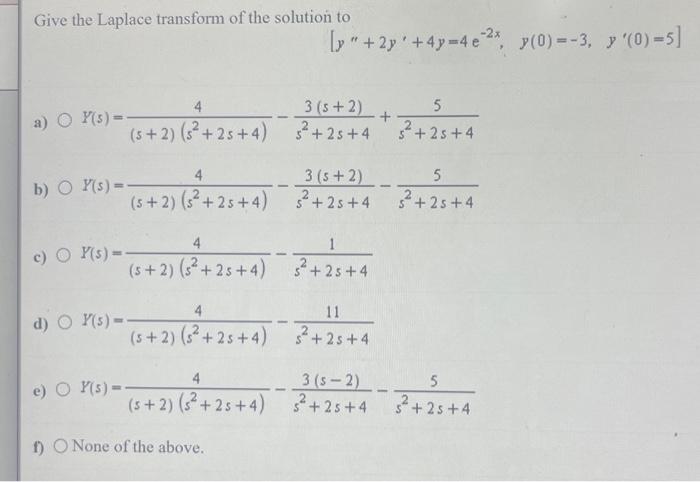
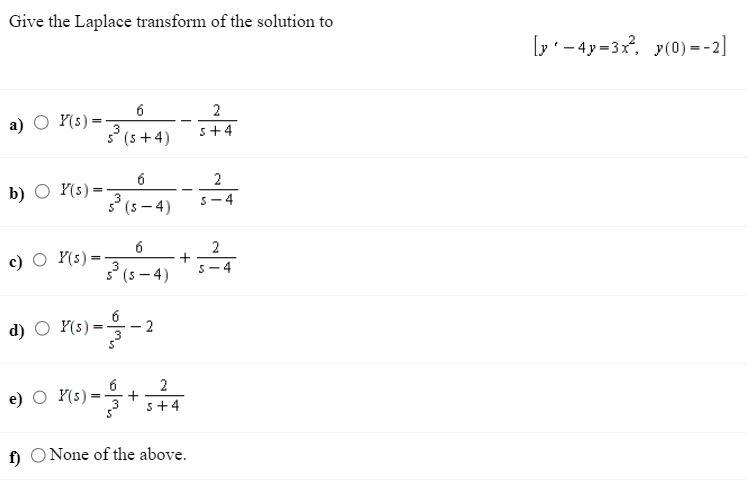
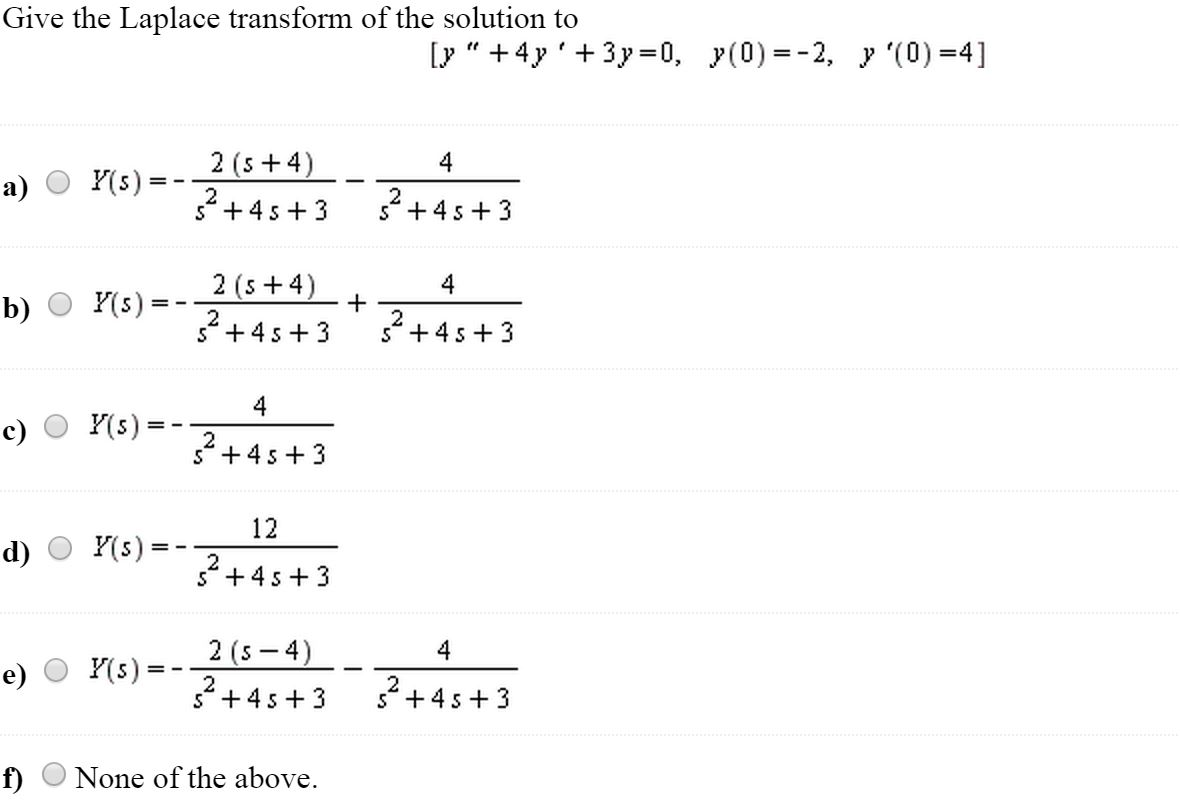
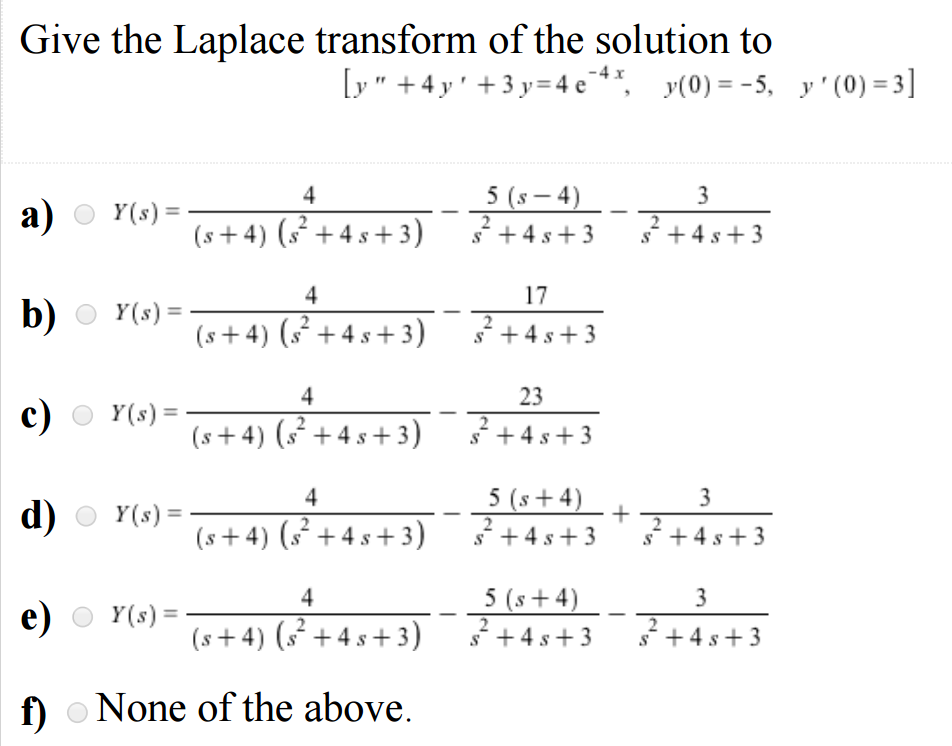
The Laplace transform method for solving differential equations is one of those tools that sounds elegant on paper and mostly works in practice, until it doesn't. The basic idea is straightforward enough: take your differential equation, apply the Laplace transform to every term, solve for Y(s), and then invert. But the devil is always in the details, especially when you're dealing with initial conditions or non-standard forcing functions. When someone asks you to give the Laplace transform of the solution to a differential equation, they typically mean: transform the equation into the s-domain and isolate Y(s). You don't actually need to perform the inverse transform unless explicitly asked. I see students waste a lot of time chasing y(t) when the problem only requires Y(s). Here is the procedure, roughly as it plays out in practice. Start by writing down the differential equation in its standard form. Apply the Laplace transform to each term individually. For derivatives, use the differentiation property: L{y'} = sY(s) - y(0), L{y''} = s²Y(s) - sy(0) - y'(0), and so on. Plug in your initial conditions immediately—don't carry symbolic y(0) around for three pages. It makes the algebra messier than it needs to be. Once every term is transformed, collect all the Y(s) terms on one side and everything else on the other. Factor Y(s) out and solve for it algebraically.
The result is your Y(s), the Laplace transform of the solution. That is often the final answer the question is looking for. Here is where things get interesting, or at least where I learned to pay attention through repeated mistakes. Partial fraction decomposition is where most people stall out. If Y(s) has repeated factors or irreducible quadratic terms in the denominator, the decomposition gets tricky fast. I spent an entire week early in my coursework second-guessing every partial fraction because I kept making sign errors when setting up the system of equations for the unknown coefficients. The workaround I eventually settled on was the residue method for simple poles—cover up the factor you're solving for, plug in the root, and read off the coefficient. It is significantly faster and less error-prone than equating coefficients for everything, though it only works cleanly when all poles are simple. Another thing that trips people up: the region of convergence. Most textbook problems skip it entirely, but if you are working with Laplace transforms beyond introductory differential equations, you need to know where Y(s) is actually valid. For causal systems, the ROC is to the right of the rightmost pole. If you ignore this and just mechanically invert, you might accidentally pick the wrong time-domain function. A rational function can have multiple inverse transforms depending on the ROC. I learned this the hard way when working on a control theory project where two different ROCs gave qualitatively different system behaviors—one stable, one unstable. The algebra looked identical; only the ROC told them apart.
There are also cases where the Laplace transform approach hits a wall. Nonlinear differential equations don't play nicely here. The transform of y² is not [Y(s)]², so any equation with nonlinear terms forces you back to numerical methods or perturbation techniques. Similarly, variable-coefficient equations like ty' + y = f(t) resist the standard approach because the Laplace transform of ty(t) involves the derivative of Y(s), which turns your problem into a different differential equation in the s-domain. Sometimes that works out, sometimes it makes things worse. I've seen this come up in heat transfer problems where coefficients depend on position, and the Laplace domain equation ended up being an ODE in s that was harder to solve than the original PDE in t and x. If you are working with discontinuous or impulsive forcing functions—step functions, Dirac deltas, periodic impulses—this is actually where the Laplace method shines. Those are genuinely painful to handle with classical methods. The transform turns a piecewise function or a delta spike into simple algebraic terms. A unit step at t = a becomes e^(-as)/s. A delta function at t = a becomes e^(-as). That single conversion is probably the main practical advantage of this technique over other methods. One more practical note: when you do need the inverse transform and partial fractions alone aren't enough, the convolution theorem is your backup. L^(-1){F(s)G(s)} = (f * g)(t). I rarely use this in homework problems because the integrals can be messy, but in signal processing and system analysis it comes up constantly. Understanding convolution in the time domain through Laplace transforms gives you a much clearer picture of how LTI systems actually behave.
Get the Full Details
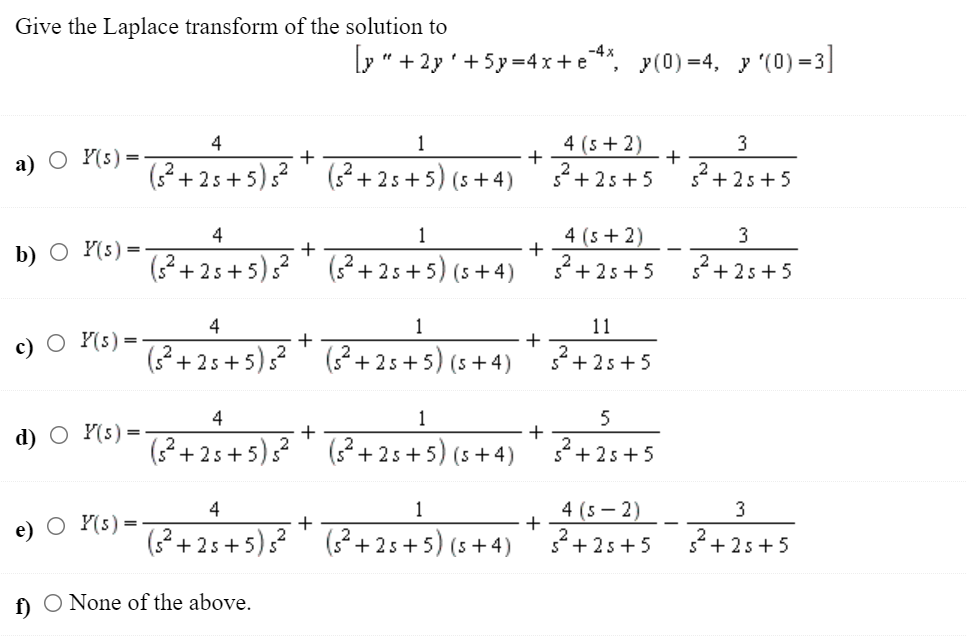
The bottom line is that this method is a solid tool for linear constant-coefficient ODEs with reasonable forcing functions. It handles initial conditions cleanly and converts calculus into algebra. But it has clear limits, and recognizing when to switch tactics saves more time than pushing through with a method that isn't suited to the problem.