Setting Up Goal Programming for Bank ALM
Most banks still run their asset liability management using basic linear programming or rule-of-thumb spread targets. It works until rates move unexpectedly and suddenly your gap positions are way too large. That is when you actually need a structured goal programming approach. The method itself is straightforward, but getting it right in practice takes more than copying a template from a textbook.
Goal Programming Techniques For Bank Asset Liability Management Applied Optimization
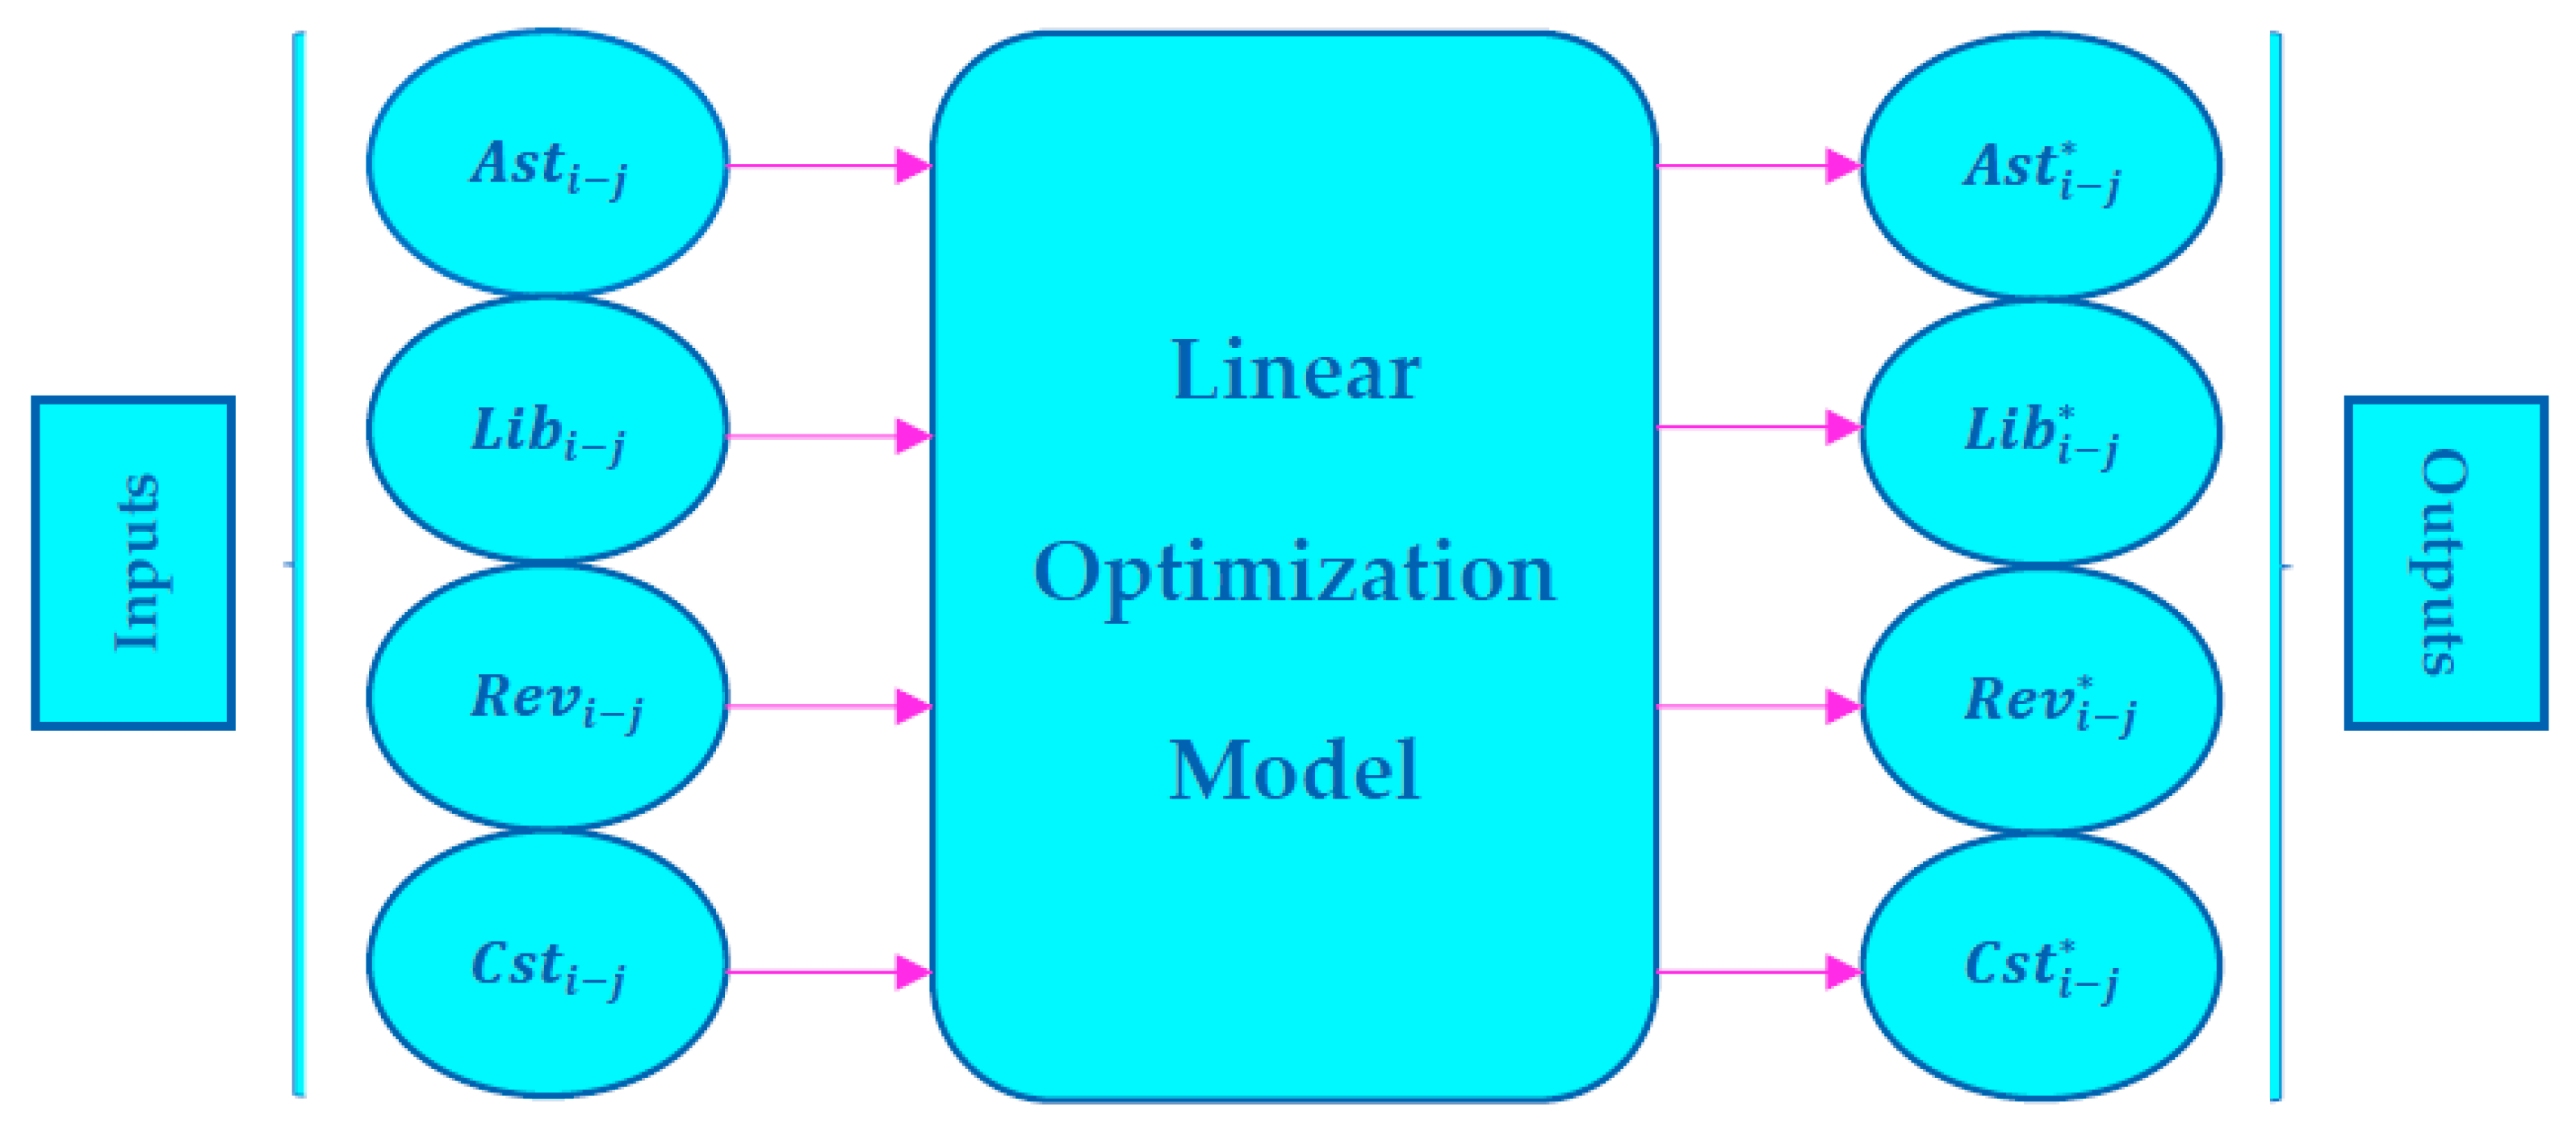
Goal programming in ALM is essentially a multi-objective optimization framework where you assign targets to different constraints and allow controlled deviations. Instead of treating every boundary as a hard constraint, you prioritize them. A bank might say net interest income should not fall below a certain level, funding costs should stay under 4%, and the liquidity coverage ratio should remain above 110%. These targets can conflict with each other, and that is exactly why goal programming exists for this problem. You set weights or priorities on each goal and let the solver find a compromise solution that minimizes weighted deviations rather than finding a single rigid optimum.The structure usually looks like this. You define decision variables, which in an ALM context are typically deposit growth rates, loan origination volumes, investment portfolio allocations, and borrowing decisions. Then you build constraints based on regulatory requirements, internal limits, and forecasted cash flows. Each constraint gets turned into a goal with a target value and a deviation variable. Positive deviations represent overshooting a target and negative deviations represent falling short. The objective function minimizes the weighted sum of undesirable deviations. I spent about three weeks building out a prototype model for a mid-sized regional bank last year. The standard LP formulation we had been using since 2019 kept producing solutions that were technically optimal but operationally useless because the solver would push everything into one asset class to maximize a single objective. Switching to a goal programming structure with prioritized deviations cut our iteration time dramatically and produced portfolios that actually matched what the treasury team was willing to trade. The trade-off was initial setup time. Getting the priority rankings correct between the bank's internal stakeholders took longer than writing the model itself.
Implementation Steps
Start by pulling your balance sheet structure. You need a detailed liability side breakdown with maturity buckets, deposit beta assumptions, and renewal probabilities. The asset side requires loan vintage data, prepayment assumptions, and investment security durations. Without this granularity, your goals will be built on garbage inputs and the output will be garbage regardless of how elegant the optimization is. Define your goal hierarchy next. Regulatory capital ratios come first if your bank is subject to them. Then liquidity metrics, then margin targets, then earnings stability objectives. Within each category, assign either preemptive priorities or cardinal weights. Preemptive priority means higher-level goals are satisfied completely before lower-level ones are considered. Cardinal weighting means you sum all deviations with assigned penalty coefficients. Most banks I see use a hybrid approach, which works fine as long as you document the rationale. For the actual solver setup, I recommend using Gurobi or CPLEX through Python if you have a development team capable of maintaining code. PuLP or Pyomo as modeling layers work adequately for smaller institutions. The solver itself handles the goal programming formulation without requiring special plugins. What matters more is your data pipeline. Automated ingestion of daily deposit and loan balance sheets into the model reduces manual intervention and keeps the optimization current enough to be useful for quarterly reviews rather than just annual stress testing.
Get the Full Details

One thing that catches people off guard is how sensitive the results are to your beta assumptions. Deposit betas determine how quickly your funding costs move when rates change, and small errors there can flip which goals the solver decides to satisfy. In my implementation, I found that calibrating betas using a rolling 12-month regression against the federal funds rate instead of relying on published industry estimates shifted the optimal asset allocation by roughly eight percent in the commercial real estate bucket. That is a material difference for a bank with a two billion dollar loan book.
Common Pitfalls
The biggest mistake I see is treating goal programming as a replacement for stress testing. It is not. The model produces optimal allocations under your specified assumptions and constraints, but it does not tell you what happens if assumptions break. Run a separate adverse scenario after you get the solution and check whether the recommended portfolio actually holds up under rate shocks or deposit outflows.Another issue is over-specifying goals. When you include too many competing objectives with conflicting weights, the solver returns solutions that are mathematically correct but strategically directionless. The portfolio looks optimized but nobody on the risk committee can explain why it was built that way. Keep the goal list focused on the five to eight things that actually matter to the institution. The rest can be handled as soft constraints if needed. There is also the problem of non-linearities that most implementations ignore. Loan loss provisions, early withdrawal penalties, and step-up CD rates introduce non-linear behavior into what is otherwise a linear programming framework. Some solvers can handle quadratic or piecewise linear functions, but once you go past that, you enter territory where the solution time balloons and convergence becomes unreliable. For a community bank with a straightforward deposit base and limited derivative usage, keeping the model linear is usually the right call. If you are running a larger institution with complex product lines, consider using a mixed-integer formulation instead. I encountered a specific edge case where the goal programming model kept recommending near-zero positions in municipal bonds even though the bank's strategy explicitly called for maintaining some tax-exempt exposure. The solver saw the after-tax yield disadvantage and pushed the allocation down to the lower bound on every iteration. The workaround was to add a minimum exposure goal as a hard priority rather than a soft objective. Once that constraint was elevated, the model redistributed the remaining objectives more reasonably and still came within two basis points of the original margin target. This took about twenty minutes to fix once I realized what was happening.
When This Approach Fails
Goal programming does not work well when your bank operates with very thin margins and minimal flexibility in asset composition. If nearly every line item is already constrained by regulatory or internal policy, adding more goal layers just creates infeasibility or forces the solver to violate goals at unpredictable rates. In those situations, a pure scenario-based optimization or a Monte Carlo simulation with rolling re-optimization tends to produce more actionable results. It also struggles during periods of extreme rate volatility where the correlation structure between assets and liabilities shifts rapidly. The model assumes historical relationships hold reasonably steady over the planning horizon. When the Fed moves 75 basis points in a two-week window, your covariance matrices become stale within days and the optimization recommendations lose relevance quickly. You can mitigate this by shortening the rebalancing cycle and updating inputs weekly instead of monthly.
For smaller banks below one billion in assets, the development and maintenance cost may simply outweigh the benefit. The model requires someone with both quantitative skills and deep ALM knowledge to keep it operational. If you do not have that on staff and cannot justify hiring it, sticking with established ALM software packages that include simplified goal-based features is more practical than building a custom solution from scratch.
Practical Workflow
A functional workflow involves running the goal program on a monthly cadence using updated balance sheet data. Feed the optimal allocation recommendation to the treasury desk, review it in the next ALCO meeting, and implement changes only where they do not conflict with existing commitment pipelines or liquidity buffers. Keep a log of each iteration's goal satisfaction levels so you can track whether the model is improving over time or drifting due to input quality degradation. That log also becomes useful documentation for auditors who will inevitably ask how your asset allocation decisions were derived.The initial build typically takes between forty and sixty hours depending on data availability and model complexity. Ongoing maintenance runs about three to five hours per month if your data pipeline is automated. Without automation, expect double that time investment due to manual data cleaning and reconciliation before each run. If you need a working reference implementation, the of this approach is available through standard academic repositories and some banking consulting firms publish white papers with sample code. The mathematical formulation itself is standard enough that adapting existing code is generally straightforward. The harder part is always getting the institutional priorities correct. That part cannot be downloaded.