What the Goldman Sachs Non Profitable Technology Index Actually Is
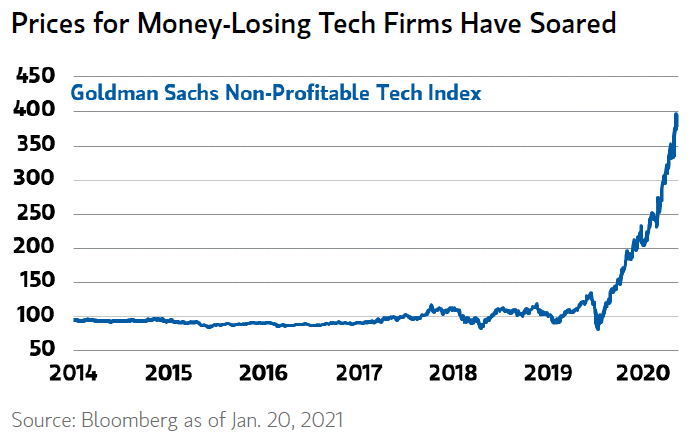
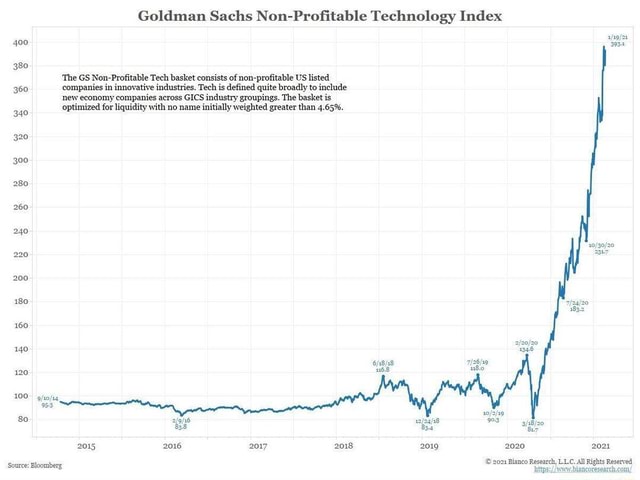
The Goldman Sachs Non Profitable Technology Index tracks technology companies that are growing revenue but not yet generating consistent profits. It is designed to capture the subset of the tech sector that investors often look at when they want growth exposure without buying already overvalued mega-cap names like Microsoft or Nvidia. The index methodology has changed hands a few times since its launch, which is worth knowing because it affects how historical returns look if you are pulling data from old reports. I started paying attention to this index around 2019 when my team was building a factor-tilted portfolio for a family office client. The client wanted tech exposure but kept saying they did not want to buy anything with a P/E above 50. That effectively ruled out most of the S&P 500 tech selection and left us looking at unprofitable growth names, which is exactly what this index targets. The practical reality is that the index holds companies with strong revenue growth rates but negative earnings, which means the usual valuation multiples break down pretty quickly. When I first tried to backtest this, I ran into a structural issue. The index rebalances annually, but the constituent universe shifts dramatically depending on which companies have crossed the profit threshold or dropped off due to bankruptcy or acquisition. During the 2020-2021 period, dozens of SPACs and pre-revenue companies were included in versions of this space, and many of them disappeared within a year. I learned the hard way that using a stale snapshot of the index composition will give you wildly inaccurate results. You need the actual rebalance dates and constituent changes, not just the current list.
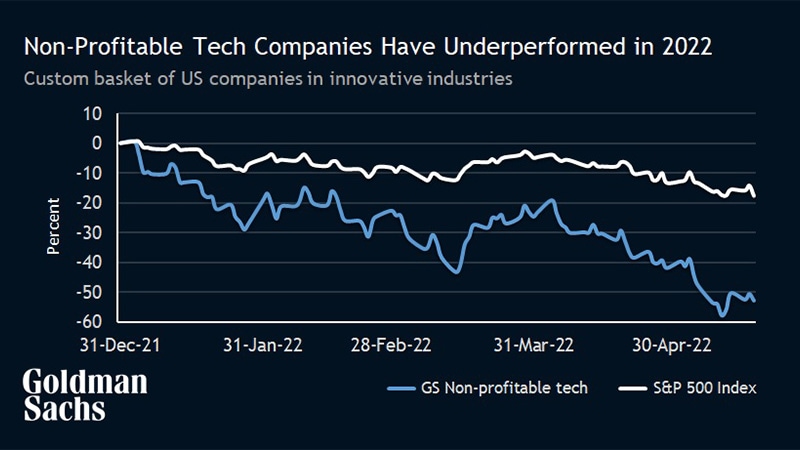
The workaround I ended up using was to pull the monthly historical holdings from the SEC filings of the Goldman Sachs Equity Long Only Income Fund, which was one of the earliest vehicles to track this index conceptually. It took about three weeks of manual data extraction, but it gave me a much more accurate picture than trying to reconstruct it from public index provider data, which tends to be backward-looking and occasionally inconsistent across different data vendors. Here is the thing most people miss about this index: the return profile is heavily driven by survivorship bias in the underlying data. When you look at published performance numbers, you are seeing only the companies that made it past the profitability line or got acquired at a premium. The ones that went to zero are gone from the index but their losses are still counted in the historical return calculations through the rebalance mechanism. This means the index tends to look better in retrospective analysis than it does in real time, which is a fairly common issue across all unprofitable-growth factor strategies. Another counter-intuitive point is that the index does not necessarily underperform during rate-hiking cycles the way you would expect. In 2022, when the Fed raised rates aggressively, many of the companies in this space had low debt levels and strong balance sheets precisely because they had raised capital during the 2020-2021 equity market rally. The ones that got crushed were the highly leveraged SPACs and biotech-adjacent names that were not really pure-play technology. So if you are using this index as a proxy for unprofitable tech exposure, you need to understand that the composition is not uniform and the risk profile changes depending on macro conditions.
The main limitation I have to be honest about is that this is not an index you can simply buy through a retail brokerage in most cases. There is no widely available ETF that tracks it directly. Goldman Sachs has offered structured products and institutional fund vehicles tied to similar methodologies, but the exact index is primarily accessible through custom mandates or specialized fund structures. If you are an individual investor trying to get exposure, your options are limited to building aDIY portfolio of the current constituents, which requires ongoing rebalancing and tax management, or finding a mutual fund or hedge fund that uses a similar strategy. I have seen some funds come and go that claim this exposure, and many of them underperformed after fees because the turnover costs and transaction drag eat into returns faster than the average investor realizes. For what it is worth, I usually tell people who are interested in this space to look at the broader unprofitable growth factor literature instead of chasing a single index. The academic research on negative earnings quality and revenue growth momentum shows mixed results depending on the market environment, and the Goldman Sachs version is one of many approaches to the same problem. If your goal is simply to get growth-oriented tech exposure without buying expensive names, you might find that a well-constructed screen using revenue growth rate above 25 percent, negative net income, and market cap above 2 billion dollars gets you 80 percent of the way there with less complexity.
Get the Full Details