How I Actually Screen Stocks Before I Buy
I don't use complex models. I use a handful of filters that take about twenty minutes to run on a watchlist of fifty names, and they strip out most of the garbage before I even look at a valuation. The reason this works is that the market prices in narrative way faster than it prices in fundamentals. By the time a company sounds exciting on earnings calls, the cheap money is gone. So the real work is in eliminating the stuff that looks fine on the surface but is structurally weak underneath.
Good Characteristics For A Good Investment
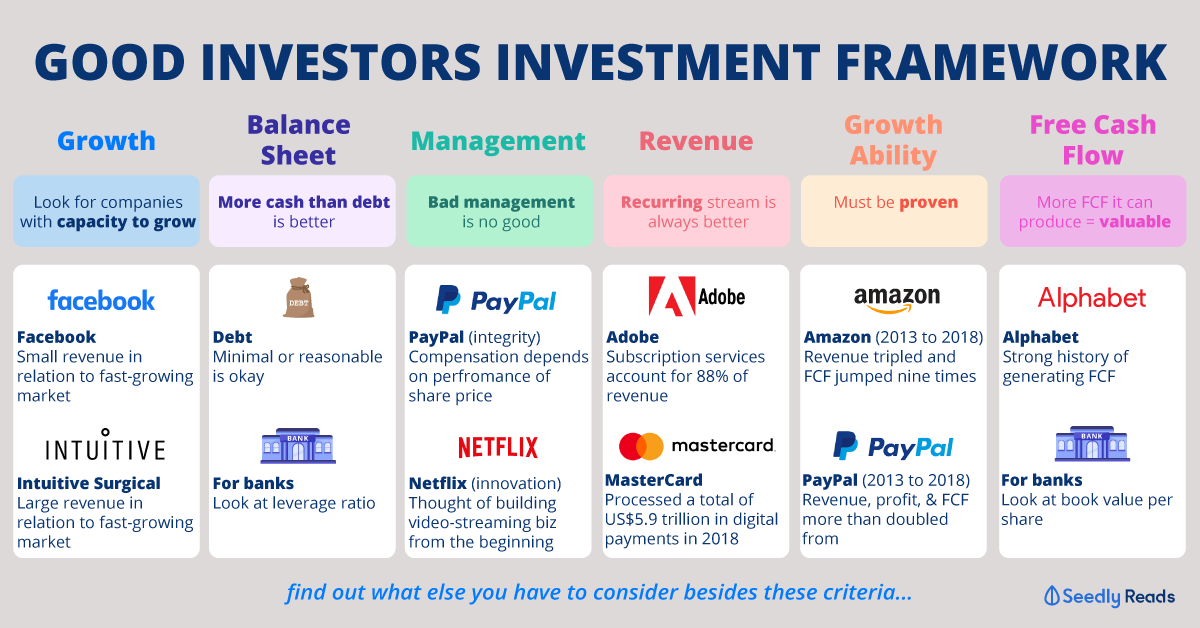
This phrase comes up constantly in forums and blogs, but nobody bothers to define what actually survives contact with real P&L statements. Here is the checklist I use. It is boring because boring is what keeps you alive in this game. Sustainable free cash flow, not accounting profit. This is the single most important filter and the one most beginners skip. Net income is a recommendation, not a fact. Free cash flow is what actually hits the bank account. I look for at least five years where FCF is positive in every single year, and where the ratio of FCF to net income sits above 0.80. When that ratio drops below 0.50 consistently, earnings quality is breaking down. I saw this with a mid-cap industrial that reported growing net income at 18% annually while its cash conversion collapsed from 90% to 40% over three years. The revenue was real, the customers existed, but receivables were inflating because the company was booking bookings it hadn't collected. I stayed away. Two years later, the business entered restructuring and the stock lost sixty percent. Low to moderate capital intensity. Companies that require constant CapEx just to maintain their competitive position are cash machines in reverse. I screen for a five-year average of CapEx to operating cash flow below 0.30. If a company needs to spend more than thirty cents on new equipment and facilities for every dollar it generates from operations, growth eats all the surplus. I prefer businesses that compound through margins and pricing power rather than through reinvestment. A retail distributor I tracked for eighteen months generated 22% operating margins with negligible CapEx. That is the pattern I want to own.
Clean balance sheet with room to breathe. Net debt to EBITDA below 2.0 is my starting line, but the real test is interest coverage. If a company can cover its interest payments fewer than eight times over a normal cycle, any downturn becomes existential. I also check the debt maturity wall. A company with $400 million in debt coming due in twelve months while running a $60 million annual interest payment is playing with fire regardless of how good the current quarter looks. Durable competitive advantage that shows up in gross margins. High and stable or expanding gross margins indicate pricing power. Low and compressing margins signal a commodity business competing on price alone. I don't require magic moats. I just want to see whether management can raise prices without losing volume, and whether the market tolerates it. Management alignment through skin in the game. Insider ownership matters, but insider buying matters more. I scan for transactions in the past twelve months where executives used their own cash to buy shares. That is a stronger signal than any compensation package. When the CEO is selling into strength while claiming confidence, I treat the press release as noise.
Get the Full Details

Reasonable valuation relative to durable earnings power. This is where people get stuck. A great business at a terrible price is a terrible investment. I use a simple framework: estimate normalized free cash flow over the next three years, discount it at 10%, and compare to current enterprise value. If the implied yield is below 5%, I pass. I do not try to predict five-year growth trajectories. Three years is about as far as anyone can see clearly without guessing. I want to flag a counter-intuitive point that most guides miss. The best investment characteristics often appear in businesses that look mediocre to the casual observer. A regional pest control company with a thousand crews, local monopolies in fifty counties, recurring revenue, and zero growth hype will look boring. The same company might have 30%+ returns on capital, 8% free cash flow yield, and a owner-operator culture that makes turnover almost nonexistent. Meanwhile, the viral AI platform everyone is discussing might have beautiful revenue growth and a charismatic CEO, but it is burning 120% of its operating cash flow and paying investors in stock options that expire underwater. Boring wins. Ugly gets ignored. That is the pattern. Here is another nuance that trips people up regularly. High return on equity can be a warning sign, not a virtue, when it is driven by leverage rather than operational efficiency. An ROE above 25% looks impressive until you separate the equity multiple effect from the underlying margin and asset turnover. If a company has an ROE of 28% but its equity multiplier is 3.2 while a peer with similar margins runs an ROE of 18% with an equity multiplier of 1.4, the leveraged company is carrying extra risk that the headline number hides. I always break ROE into the DuPont components before I let it influence my decision.
I also need to be honest about what this approach does not do. It misses transformation stories. It misses companies that intentionally suppress cash flow today for optionality tomorrow. It misses situations where management is temporarily misallocating capital with genuine intent to course-correct. My screening process has a structural bias toward businesses that already proved themselves over multiple cycles, which means it will never own the next ten-bagger in its early phase. That is a trade-off I accept consciously. I would rather miss the rocket ship than blow up on a landmine. There is one specific edge case I still think about from 2022. I ran this exact screen on a specialty chemicals name that passed every filter: strong FCF conversion, low leverage, expanding gross margins, and insider buying. The story was solid. I bought after a 22% pullback. Three months later, a single customer that represented 18% of revenue switched suppliers. The FCF collapsed in a single quarter. What I had missed was customer concentration that the financials did not surface until it was too late. The workaround I adopted after that loss was to add a customer concentration check to the initial screen. Any company where a single customer accounts for more than 15% of revenue now gets flagged automatically, and I either skip it or demand a larger margin of safety. That one miss cost me roughly fourteen percent of capital and six months of opportunity cost. It was worth the lesson. So here is the practical takeaway. Good Characteristics For A Good Investment is not a philosophy. It is a set of hard filters that remove the fragile businesses before they reach your portfolio. Cash flow quality, low capital intensity, manageable debt, durable margins, aligned management, and disciplined valuation. Run through them systematically. Do not let a compelling narrative override a failing filter. The market rewards discipline more often than it rewards brilliance.