Investing in Google's Stock: What Actually Matters
GOOG stock, or Class A shares of Alphabet Inc., is one of those mega-cap positions everyone talks about but few actually understand beyond the headline price. The first thing I tell anyone asking me about it is that the stock doesn't move on earnings alone anymore. It moves on cloud margins, ad revenue stability, and whatever AI narrative is current quarter. Google/Alphabet trades at a different premium than it did five years ago, and if you're treating it like a simple index bet, you're going to get burned. I've held positions through the 2022 tech sell-off, the AI hype cycle, and several earnings beats that still dropped the stock. Here's the breakdown of what I've learned, what trips people up, and how to actually approach this.
The Two-Class Mess You Need to Understand First
Alphabet has two share classes: GOOG (Class C, no voting rights) and GOOGL (Class A, one vote per share). The price difference between them is usually pennies, sometimes a dollar. Most retail investors buy GOOG because it's the ticker they recognize from search results. The structural advantage of GOOGL is real — voting power matters when you're dealing with management decisions, but for pure price exposure, they track nearly identically. I picked GOOG early on because the liquidity was slightly better for my position sizing, and honestly, I never bothered switching. Dollar-cost averaging into GOOG is the most sensible approach for most people, but the timing within quarters matters more than the frequency. I used to DCA weekly without thinking about it until I noticed a pattern: Google tends to consolidate sideways for about two weeks after earnings, then makes its directional move. Buying during that post-earnings drift usually gets you a better average price than throwing money in on schedule. Here's a specific problem I ran into that probably won't hit most people but is worth noting. During the 2023 regulatory headwinds, GOOG started trading at a noticeable discount to GOOGL — around $2 to $3 per share wider than normal. I had a pre-existing position in GOOGL from before the split restructuring became a bigger deal, and I decided to buy GOOG instead to capture that spread. The spread didn't close for about eleven months. Had I not noticed it, I would've just been buying at face value without the margin of safety. The workaround was simple: check the GOOG-to-GOOGL spread on any given entry day, and if it's wider than $1.50, switch to GOOG. If it's tighter, it doesn't matter much which you buy.
What Actually Moves This Stock
Google's revenue breakdown roughly splits into: advertising (about 78%), cloud and other bets (about 22%). When people look at quarterly results, they focus on revenue growth. Revenue growth is the least interesting number. The numbers that move the market are operating margin in Google Cloud and the Search ad yield per thousand impressions. Google Cloud crossed $10 billion in quarterly revenue a while back and is now growing at a meaningful clip, but the stock reacts more to margin expansion than top-line growth. If cloud revenue grows 30% but margins compress, the stock drops. If cloud revenue grows 15% and margins expand, the stock pops. This is counterintuitive for most retail investors who are trained to chase revenue growth in any sector. Another thing nobody warns you about: Google's share buyback program is enormous. Alphabet has been buying back billions in stock every quarter. This reduces share count and artificially supports EPS growth even when the underlying business is flat. During periods when the stock dips on macro fears, the buyback program often becomes more aggressive, which creates a natural floor. I've used this to my advantage by setting limit orders just below obvious support levels, knowing that institutional buying pressure from the buyback program tends to catch shares in that zone.
Get the Full Details
The Downsides Nobody Discusses
GOOG stock has real structural risks that get glossed over in beginner guides. Antitrust fragmentation is the big one. If the DOJ case succeeds in breaking up Google Search or YouTube as a condition, the stock could re-rate significantly lower — we're talking 20 to 30% downside in a worst-case scenario. This isn't hypothetical. The EU has already fined Google multiple times under antitrust regulations, and the US case is ongoing. Second, Google's reliance on search advertising means any shift in how people access information — voice search, AI-generated answers, generative AI replacing click-based navigation — directly threatens the core business model. Third, Google Cloud is catching up to AWS and Azure but still trails both significantly. If Google can't maintain margin expansion there, it becomes a drag on overall profitability. Also worth noting: GOOG is a low-volatility mega-cap. If you're looking for asymmetric upside, this isn't it. It's a compounder. Realistic annual returns, adjusting for buybacks and moderate growth, are probably in the 10 to 15% range over a full cycle. That's not a bad return, but it's not going to double your money in a year unless a black swan event hits on the upside.
Practical Steps to Get Started
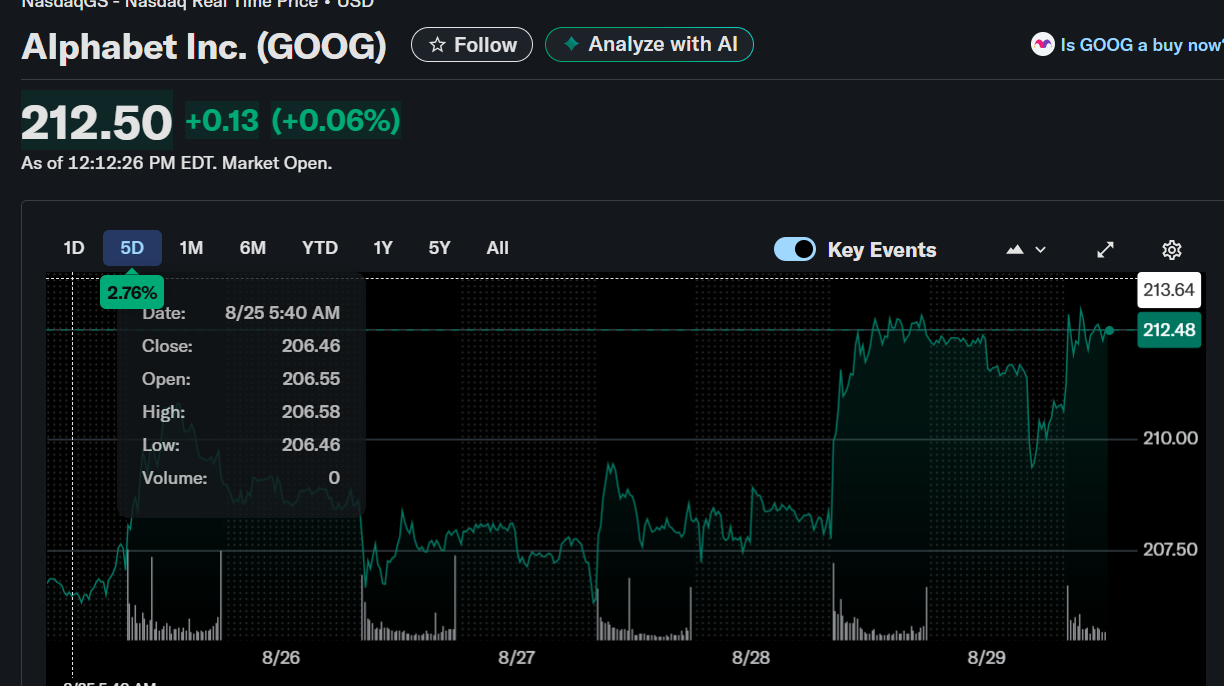
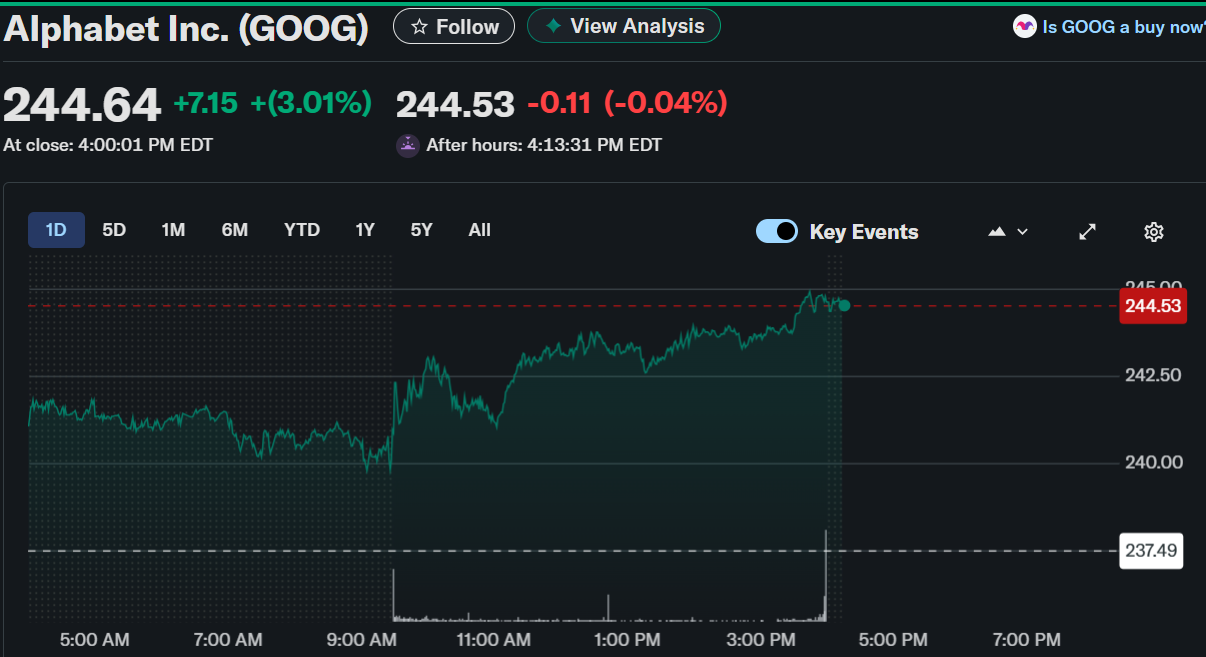
Open a brokerage account with low fees. Fidelity, Schwab, or any major platform works fine. Link your bank account. Search for GOOG. Place either a market order for immediate execution or a limit order if you want to wait for a specific price. I recommend limit orders for a stock this liquid — the spread is usually a cent or two, but with volatile days, market orders can slip more than you'd expect. For actual purchase, there's no direct download or special portal. You buy through your brokerage. Some platforms offer fractional shares now, which is useful if you don't have enough capital to buy a full share at current prices. Google's share price has been trading in the $140 to $190 range over the past year, so fractional shares make entry possible at almost any level.
Monitoring What Matters
Set up earnings calendars. Alphabet reports quarterly, usually in late January, April, July, and October. Read the earnings call transcript, not just the press release. The press release will highlight the good numbers. The Q&A section on the call tells you where management is worried. I keep a simple spreadsheet tracking quarterly cloud revenue, cloud operating margin, and search advertising CPM trends. That's it. Three data points per quarter. Anything else is noise. If you're actively managing this position, watch the broader Nasdaq and the Magnificent Seven basket. GOOG rarely moves independently for long. When NVIDIA, Meta, and Microsoft are dumping, GOOG usually follows within a day or two. When the AI trade rotates back into big tech, GOOG participates, though often with a delay compared to the faster-moving names like NVDA. Bottom line: GOOG stock is a solid long-term holding for someone who wants exposure to a dominant ad-tech and cloud business with AI upside. It's not exciting. It's not risky in the way meme stocks are. It's also not a place to park money and forget about it if you care about maximizing returns. The market rewards people who actually read the earnings calls and understand the segment-level dynamics. The rest of the time, it just sits there and compounds, slowly, while everyone else chases the next hot ticker.