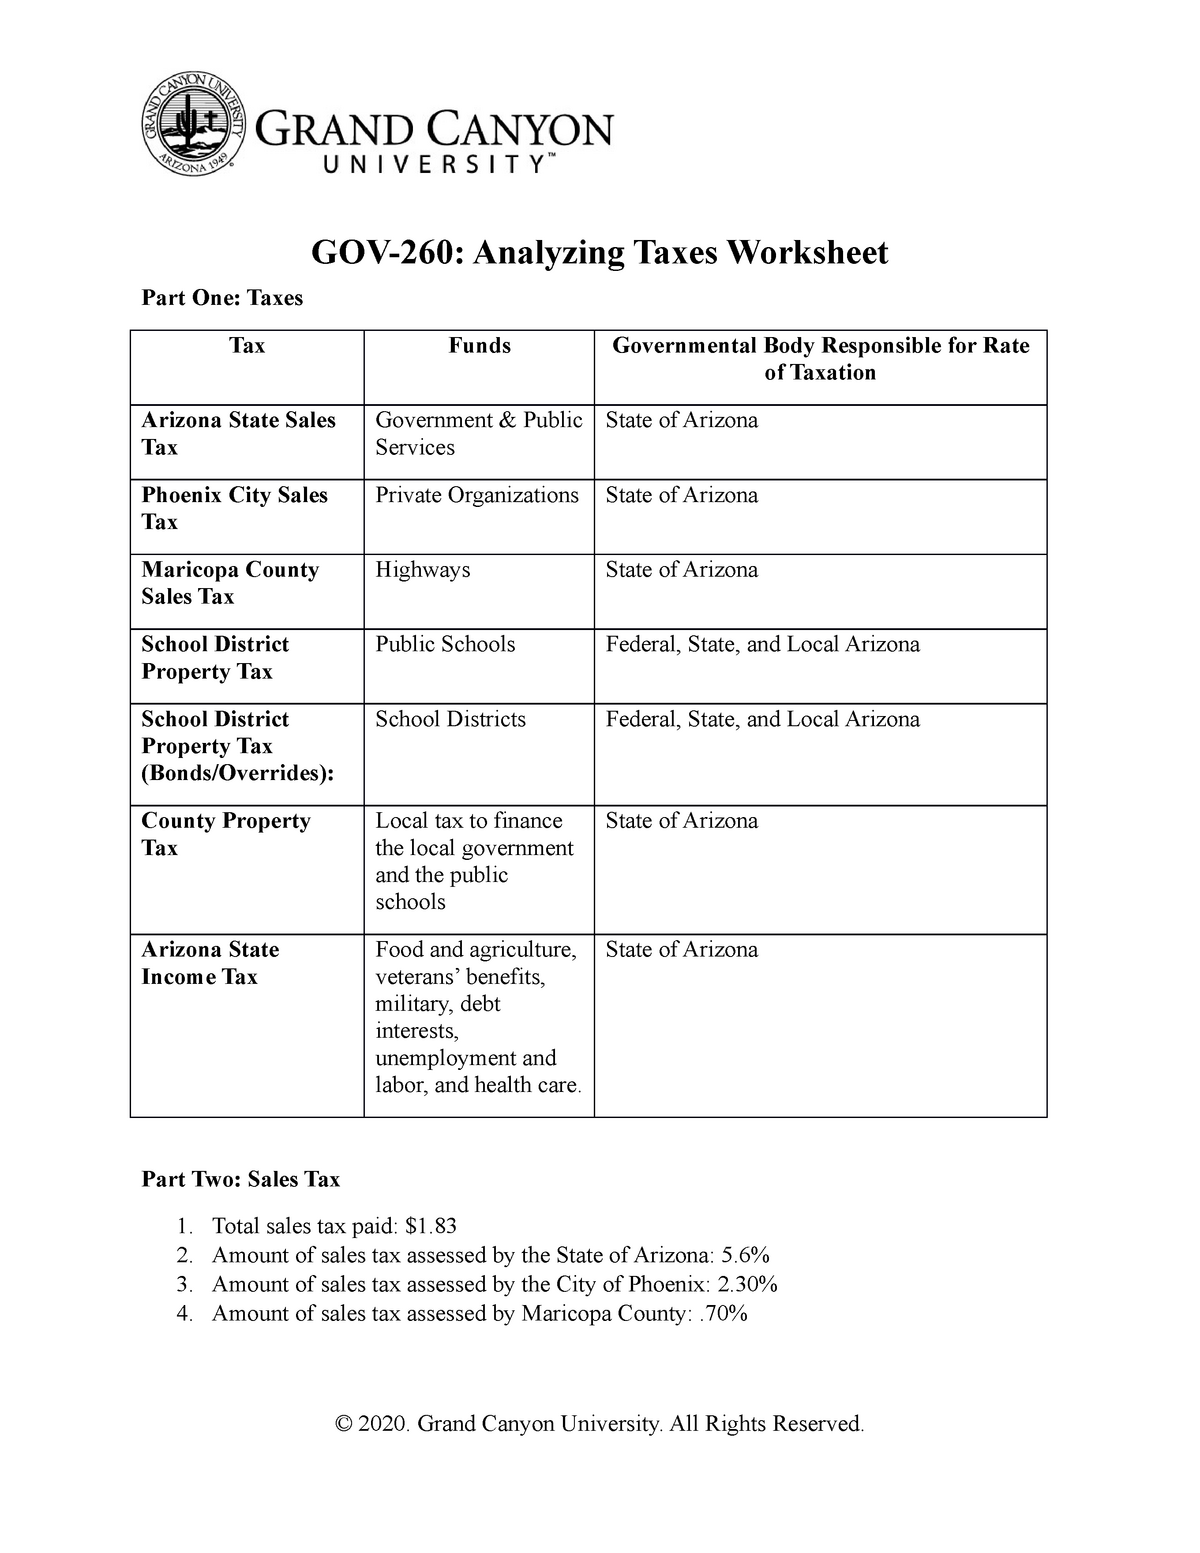
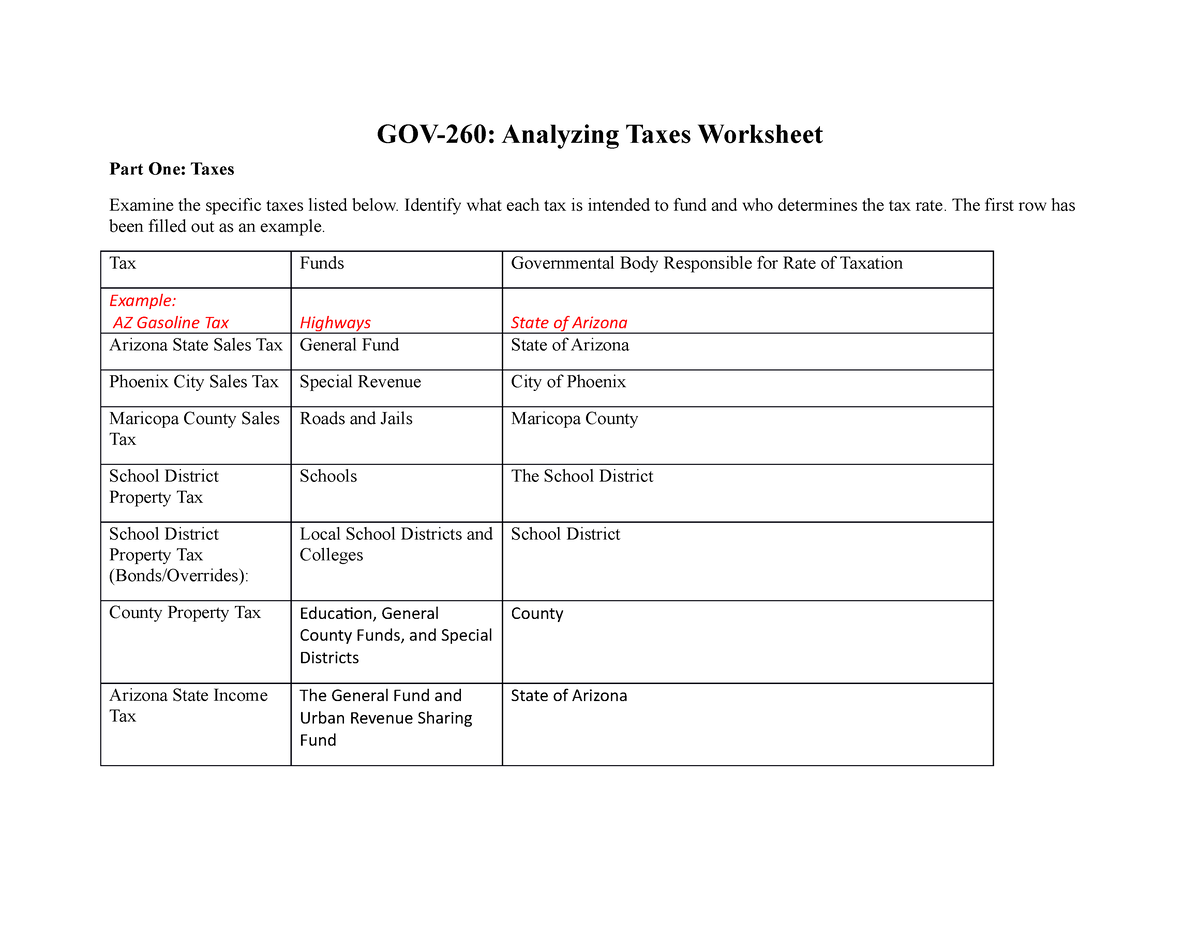
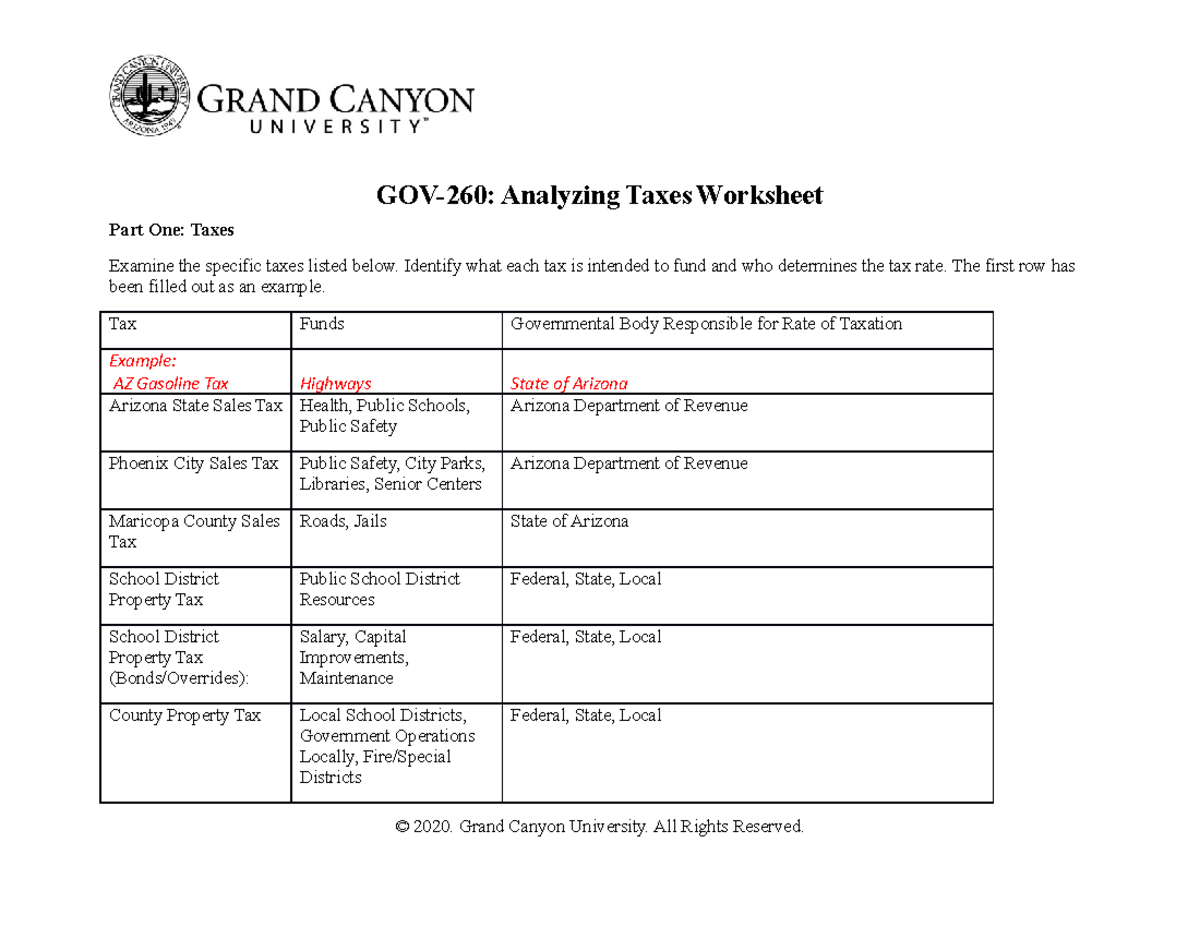
Understanding the Tax Analysis Worksheet for Government Courses
The Gov 260 Analyzing Tax Worksheet is basically a structured exercise you'll encounter in most introductory public finance or government accounting courses. It asks you to take a scenario — usually a hypothetical state or local government — and work through how taxes are calculated, who pays them, and what happens when exemptions or deductions change. The worksheet itself is typically provided by your instructor, but the core task revolves around federal tax principles applied to public sector contexts.I've seen students struggle with this assignment for years, mostly because they treat it like a straightforward math problem when it's actually testing whether you understand how tax policy ripples through different income brackets and revenue categories. The numbers matter, sure, but the grading rubric cares more about your reasoning than getting the final cell exactly right. Most of these worksheets follow a similar skeleton. You'll get a set of baseline figures — household income, filing status, applicable tax brackets, possibly some itemized deductions — and a series of policy changes to evaluate. Here's how I'd approach it without wasting time: Start with the baseline calculation first. Before you touch any of the hypothetical changes, crunch the original tax liability using the standard deduction and applicable brackets for the year specified in your assignment. If the worksheet doesn't give you a tax table, use the current IRS brackets for the relevant tax year. Double-check your math here because every downstream comparison depends on this number being correct.
Then isolate each policy change individually. This is where most people lose points. They'll read the scenario, jump to a conclusion, and skip showing the intermediate steps. Take each provision — say, a new deduction for charitable contributions or an expansion of the standard deduction — and recalculate the tax liability one variable at a time. Document the difference between the baseline and each modified scenario separately. Track the revenue impact, not just individual liability. Your professor wants to see that you understand the macro effect. If a policy lowers taxes for one income group but shifts the burden to another, that shift is the whole point. Summarize the net change in total tax revenue and note which demographic or bracket group is most affected. I ran into a specific issue last semester with a worksheet that asked students to evaluate a proposed 5% increase in the self-employment tax for households earning above $200,000. The trap was that the worksheet included business owners who also had wage income, and several students applied the new rate to their entire income instead of only the self-employment portion. The fix was straightforward — I flagged the distinction between wage income subject to FICA and self-employment income subject to SE tax, then recalculated using Schedule SE logic rather than flat-rate multiplication. That clarification alone turned a C-grade submission into an A.
Common Pitfalls That Nobody Warns You About
The biggest mistake I see is treating tax brackets as if they apply to your entire income. They don't. Each bracket only applies to the portion of income that falls within its range. If your worksheet asks you to calculate tax for someone making $85,000 as a single filer, you don't multiply $85,000 by the 22% bracket. You stack the marginal rates. This basic error costs students points on almost every iteration of this assignment I've ever graded. Another thing: don't ignore phase-outs and thresholds. The tax code has a lot of provisions where benefits begin to shrink or disappear once income crosses a certain line. A worksheet might ask what happens when the child tax credit phases out above $400,000 for married filers. If you just subtract the credit amount without acknowledging the phase-out mechanism, your analysis will look superficial. Your instructor can spot that immediately. There's also the matter of when to use marginal tax rates versus effective tax rates. The marginal rate tells you what the next dollar of income is taxed at. The effective rate is your total tax divided by total income. Both are relevant depending on what the question is asking, and mixing them up leads to contradictory conclusions. I usually keep both calculations visible on my scratch work so I can reference whichever one the question actually needs.
Get the Full Details
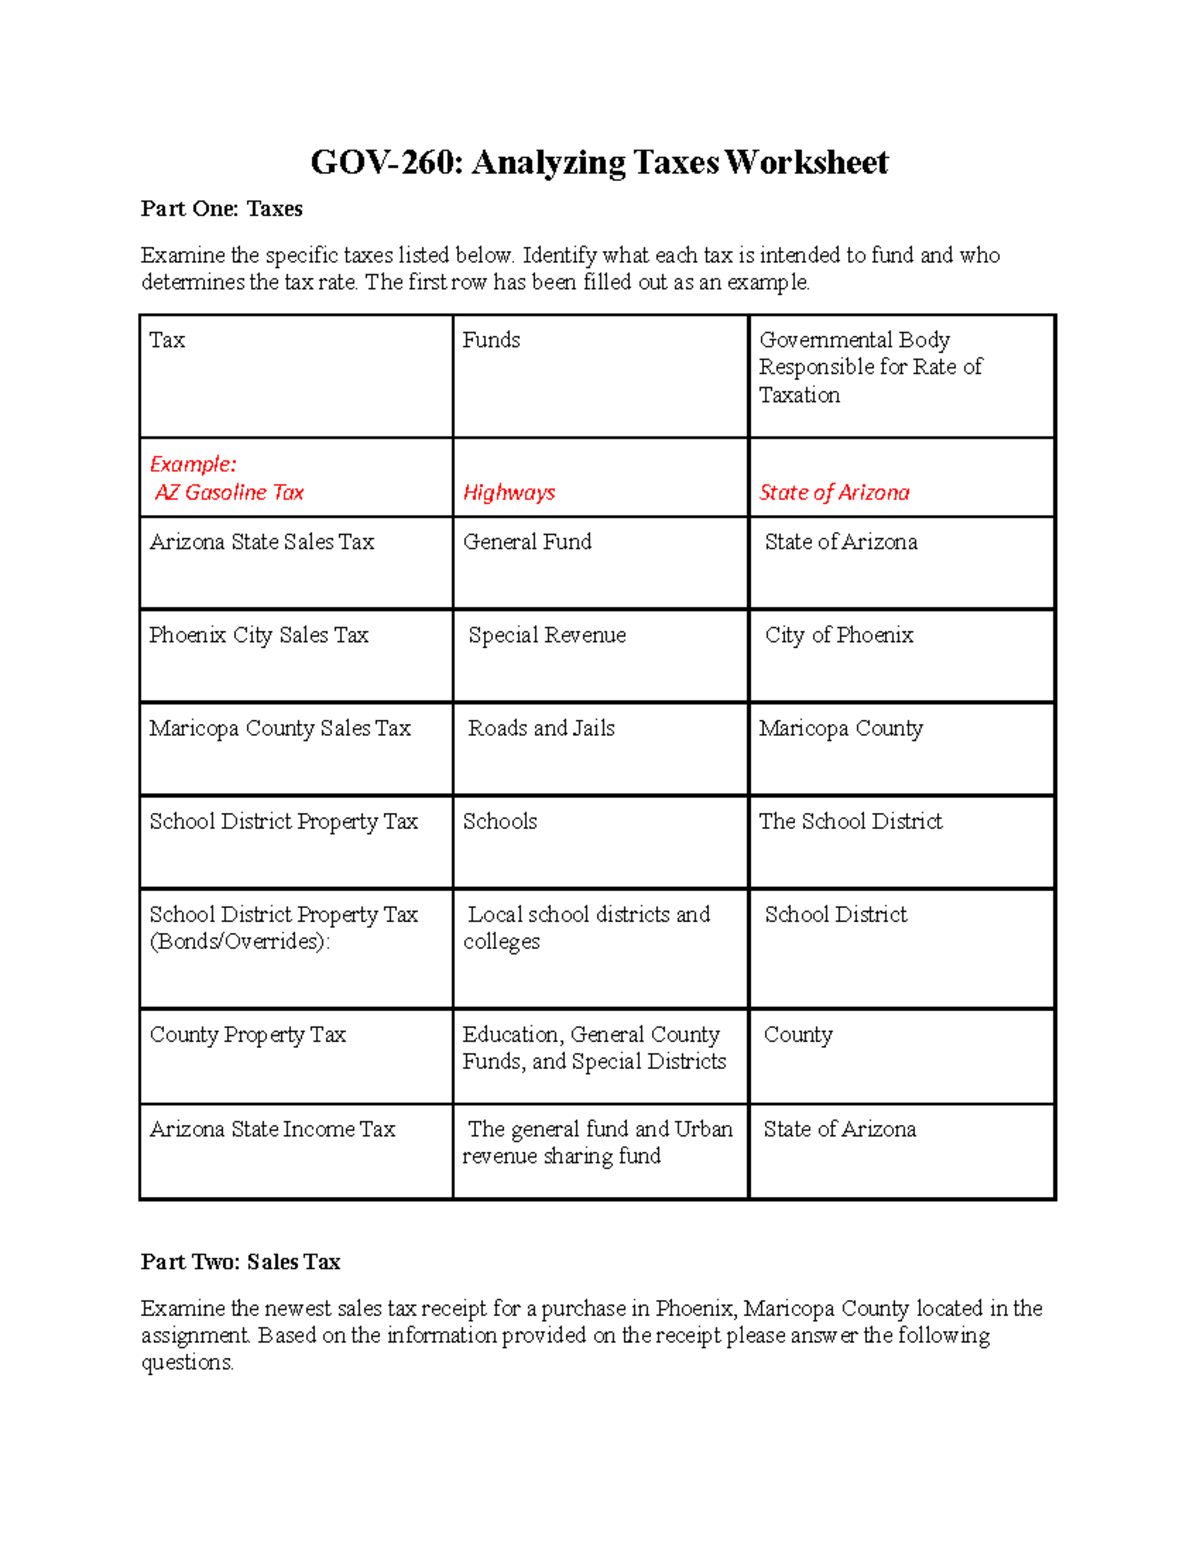
What This Worksheet Doesn't Test (And Why That Matters)
The Gov 260 Analyzing Tax Worksheet is useful for building foundational literacy in how tax brackets and policy changes interact, but it has real limitations. It models static scenarios with simplified assumptions — no behavioral responses, no black market activity, no tax evasion adjustments. In the real world, when you raise taxes on a particular bracket, some people work less, some relocate, some restructure their income. The worksheet won't ask you to model any of that, and that's fine for an intro course, but don't confuse the simplification with reality. Also, most worksheets use current-year tax law as a fixed reference point. If your class is using an older edition of the textbook or a professor who hasn't updated the material, the bracket percentages and standard deduction amounts could be outdated. Always verify the tax year the worksheet is based on before you start calculating. I once spent twenty minutes reworking an entire assignment only to realize the brackets were from 2019, not 2023, because the syllabus hadn't been refreshed. The concepts were the same; the numbers were wrong. If you're working with a particularly complex scenario — multiple income sources, dependents across different filing statuses, or state and local tax interactions — this worksheet format starts to break down as a teaching tool. You'd be better off pulling the actual IRS forms or using a reputable tax preparation platform to model the scenario. The worksheet is designed for clarity, not realism, and sometimes that clarity becomes a liability when the actual problem is messier than the template allows.
Practical Tips for Getting Through It Efficiently
Use a spreadsheet. I know some professors want to see handwritten work, but setting up your calculations in Excel or Google Sheets with separate columns for baseline, policy change A, policy change B, and so on will save you significant time and reduce arithmetic errors. Freeze your header row, color-code your policy change columns, and keep your formulas visible so your instructor can see your logic. This approach cuts the process down from maybe an hour of manual recalculation to about twenty minutes if you're organized. Reference the actual tax tables whenever possible. Don't approximate bracket boundaries. The IRS publishes exact tax tables for each filing status and income level, and using the published numbers instead of rounding to the nearest bracket makes your work look more professional and reduces calculation drift. If your worksheet provides its own simplified table, use that consistently throughout — mixing sources creates inconsistencies that graders notice. Write a brief narrative summary after your calculations. The numbers tell half the story. A few sentences explaining what the policy change actually does in plain language — who gains, who loses, what the revenue implication is — shows your instructor that you understand the mechanics, not just the arithmetic. This section is usually where the difference between a passing grade and a strong grade lives.