Measuring Government Size And Economic Growth Actually Works When You Stop Looking At Percentages
The first thing you need to understand is that nobody agrees on what "government size" actually means in a dataset. The OECD, IMF, World Bank, and most national statistical agencies all calculate it differently. Some include social security contributions as revenue. Some don't. Some count state-level spending. Some count only federal. This matters because a country reported at 42% of GDP could be 36% or 48% depending on which methodology you use, and that difference completely flips your regression result. I spent about six months trying to build a cross-country panel dataset on this topic for a research project. The problem I hit most often was that many developing nations simply do not report spending and revenue consistently enough for time-series analysis. Country-level data from the World Bank's Government Finance Statistics starts around 1972 for most countries, but the coverage is patchy. My workaround was to use the IMF's extended GFS database, which backfills some missing entries using nowcasting models. It's not perfect, but it's significantly better than just dropping countries with incomplete records. I also cross-referenced with the OECD Revenue Statistics where available for the 1965-1975 period for European countries, which filled about 80% of the gaps for that subset.
The Core Relationship Between Government Size And Economic Growth
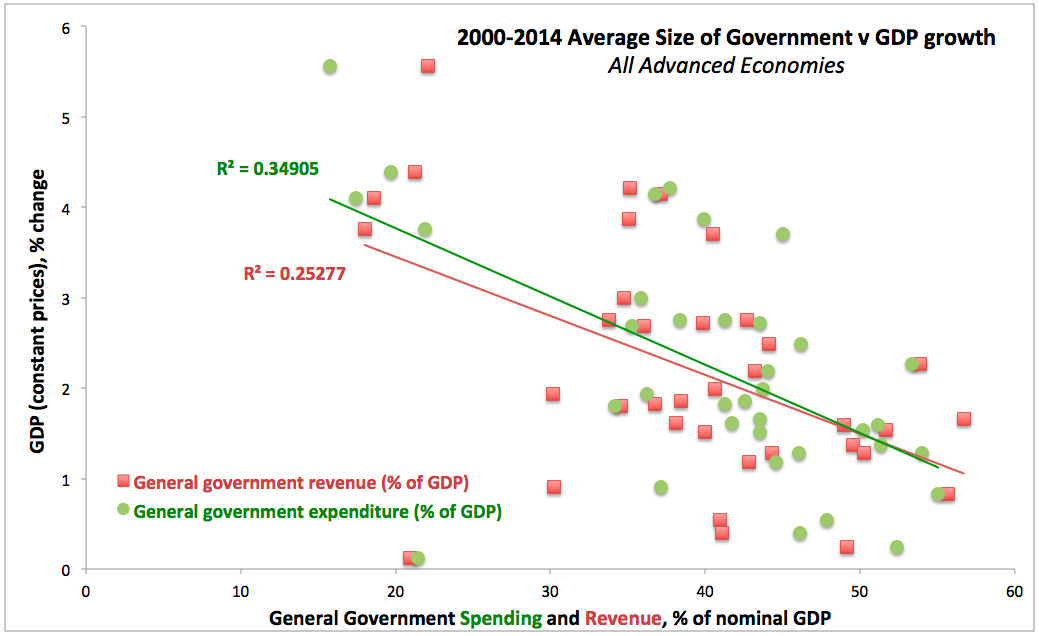
The basic empirical finding, if you strip away the noise from different methodologies, is that the relationship is negative but very flat across most of the observed range. Going from 20% of GDP in government spending to 40% typically reduces the annual growth rate by somewhere between 0.1 and 0.3 percentage points in standard panel regressions. Going from 40% to 60% doesn't produce much additional drag. The marginal effect is non-linear. This is counter-intuitive for people who expect a simple linear story. The reason is that government spending itself produces output. A dollar spent on roads adds to GDP directly and can also raise productivity for everyone else on that road. The question is whether the tax revenue needed to fund that dollar reduces private sector output by more or less than one dollar. Most of the literature suggests that when the tax system is moderately progressive and the spending is productive, the net effect is close to neutral. When you get into high rates on capital income and heavy regulation, the drag becomes measurable. The most commonly cited threshold from the academic literature is somewhere around 40 to 45 percent of GDP for total government expenditure. Past that point, the negative correlation with growth tends to steepen. But "tends to" is doing a lot of work here. The relationship is far from deterministic.
What most beginners miss is that they are usually controlling for the wrong things. When you run a regression of growth on government size, you need to control for the quality of institutions, the structure of the tax system, and whether the spending is consumption versus investment. If you don't, you're just picking up the effect of good institutions doing both of these things simultaneously—keeping government appropriately sized and growing the economy. That's not a causal claim about government size. It's a claim about institutional quality. I found this out the hard way. My first draft regression showed a coefficient of negative 0.45 on government size, which looked huge. Then a colleague pointed out that I hadn't included a measure of bureaucratic quality or rule of law. Once I added that, the coefficient on government size dropped to about negative 0.12 and lost most of its statistical significance. The real driver wasn't government size itself. It was the fact that countries with large governments in my sample also happened to have weaker institutions.
Get the Full Details

How To Build Your Own Analysis
The practical approach is to use panel data with country fixed effects. This controls for all time-invariant country characteristics, which eats up a lot of the omitted variable bias. The basic specification looks like this: Growth_it = _i + (GovSize_it) + (X_it) + _it Where _i is the country fixed effect, GovSize is the ratio of government expenditure to GDP, and X is a vector of time-varying controls like inflation, trade openness, investment rate, and terms of trade shocks. The coefficient is what you're after.
For data sources, the World Bank's WDI database is the easiest starting point. It has government expenditure as a percentage of GDP and real GDP growth for most countries back to the 1960s. The IMF's WEO database gives you slightly more detail on the revenue and expenditure breakdowns. If you want the most complete coverage, the OECD's National Accounts data is excellent for developed economies but useless for most of the developing world. One thing I learned the hard way: be very careful about reverse causality. Slow economic growth leads to higher government spending as a share of GDP because the denominator shrinks. Automatic stabilizers kick in during recessions. This mechanically creates a negative correlation between growth and government size even if there is no causal effect in either direction. The standard fix is to use lagged government size as the explanatory variable or to use an instrumental variable approach. The lagged approach is simpler and usually sufficient. Using government size from t-1 or t-2 as the predictor while regressing growth at time t mostly solves the simultaneity problem without requiring the kind of creative instrument hunting that usually leads to weak instrument problems anyway. Another practical issue is the measurement of economic growth itself. Nominal GDP growth and real GDP growth tell very different stories when inflation is high. Always use real GDP growth. And be aware that real GDP per capita growth is a better measure of living standards than aggregate real GDP growth, since population growth can mask stagnation. A country growing at 3% per year with 2.5% population growth is doing much worse than one growing at 3% with zero population growth.
What The Data Actually Shows In Practice
Looking at the cross-sectional evidence, the Nordic countries spend between 50 and 60 percent of GDP and maintain solid growth rates. East Asian tigers kept government spending below 30 percent for decades and grew very fast. Southern European countries sit in the middle with mixed results. This is exactly why the relationship can't be reduced to a single number. The institutional context matters enormously. High-quality public administration can make 50 percent of GDP feel like 30 percent in a country with weak institutions. The same tax revenue funds different things. In one country it funds functional infrastructure and education. In another it funds patronage networks and unsustainable pension promises. The growth outcomes diverge dramatically even at the same government size. The tax composition is almost more important than the spending level. Revenue from broad-based consumption taxes like VAT tends to be less growth distortive than revenue from corporate income taxes or heavy reliance on capital gains taxes. This is a well-established finding in the public finance literature, though the magnitude of the difference is debated. Still, a country raising 40 percent of GDP through VAT and property taxes will almost certainly grow faster than one raising the same amount through corporate taxation and complex subsidies.

If you want to dig deeper, the Barro (1990) framework is still the standard reference point, though it is over four decades old. More recent work by Arnott and Burke (1997), and the subsequent literature they spawned, refined the threshold estimates. The International Monetary Fund has also published several working papers on this topic that are more empirically grounded than the early theoretical work. For policy-oriented analysis, the IMF's Fiscal Monitor reports every April and October contain useful cross-country comparisons of government size and macroeconomic outcomes.
When This Framework Breaks Down
The relationship between government size and economic growth simply doesn't hold in war economies, failed states, or countries undergoing major structural transitions. In those contexts, the size and direction of government spending is determined by completely different forces than the ones the standard model assumes. You will find some conflict-affected countries with very small governments and very low growth, and others with large wartime governments and collapsing output. Neither case fits the standard framework. Small island economies and microstates are also problematic. Their government sectors tend to be large relative to GDP by necessity because they can't achieve the economies of scale that larger countries enjoy. A country with 500,000 people needs roughly the same core institutions as one with 50 million. The per-GDP cost is inherently higher. Treating these cases the same as large economies in a regression introduces systematic upward bias in the estimated coefficient. There is also the matter of time lags. Government investment in infrastructure, education, and institutional capacity may not show up in GDP growth for five to ten years. Short panel datasets of ten or fifteen years can easily miss the positive effect of productive government spending while capturing only the short-term drag of taxation. If your time window is too short, you are probably estimating the wrong thing.
The practical limit of this whole approach is that it tells you very little about what any specific country should do. It gives you a probabilistic relationship across hundreds of observations. It does not tell you whether raising the VAT rate by two percentage points in France will help or hurt. For that you need country-specific analysis, ideally with microdata on how different taxpayer segments respond to marginal rate changes. Aggregate cross-country regressions simply lack the resolution for policy prescription at the national level.

Where To Get The Data
The World Bank's Worldwide Governance Indicators provide an institutional quality index you can use as a control variable. The Penn World Table has a very clean dataset on government consumption and capital formation that is freely downloadable. For anyone doing serious work in this area, it is worth the time to set up an account and pull the raw data rather than relying on secondary summaries, which are often calculated using methods you won't know about. The IMF's Government Finance Statistics database is the most comprehensive source for revenue and expenditure breakdowns by functional category. It is free to access with registration and includes data going back to 1970 for many countries. The breakdown by function lets you separate education spending from defense spending from general public services, which is crucial because the growth implications of each are very different. For visualization and quick comparison, the Our World in Data project has an excellent interactive chart on government size across countries and time. It is built on OECD and World Bank data with clear methodology notes. It is a good starting point before you commit to building your own dataset.
The whole exercise of measuring Government Size And Economic Growth is straightforward in principle and frustrating in practice. The frustration comes from the data quality issues, the methodological choices, and the fact that the answer you get depends heavily on which controls you include. But once you work through those problems, which took me about three months of iteration, you end up with a reasonably reliable estimate of a relationship that matters for actual policy decisions. Not a definitive answer, but a better one than most people who debate this topic ever bother to calculate.