Starting a business is mostly paperwork until it isn't
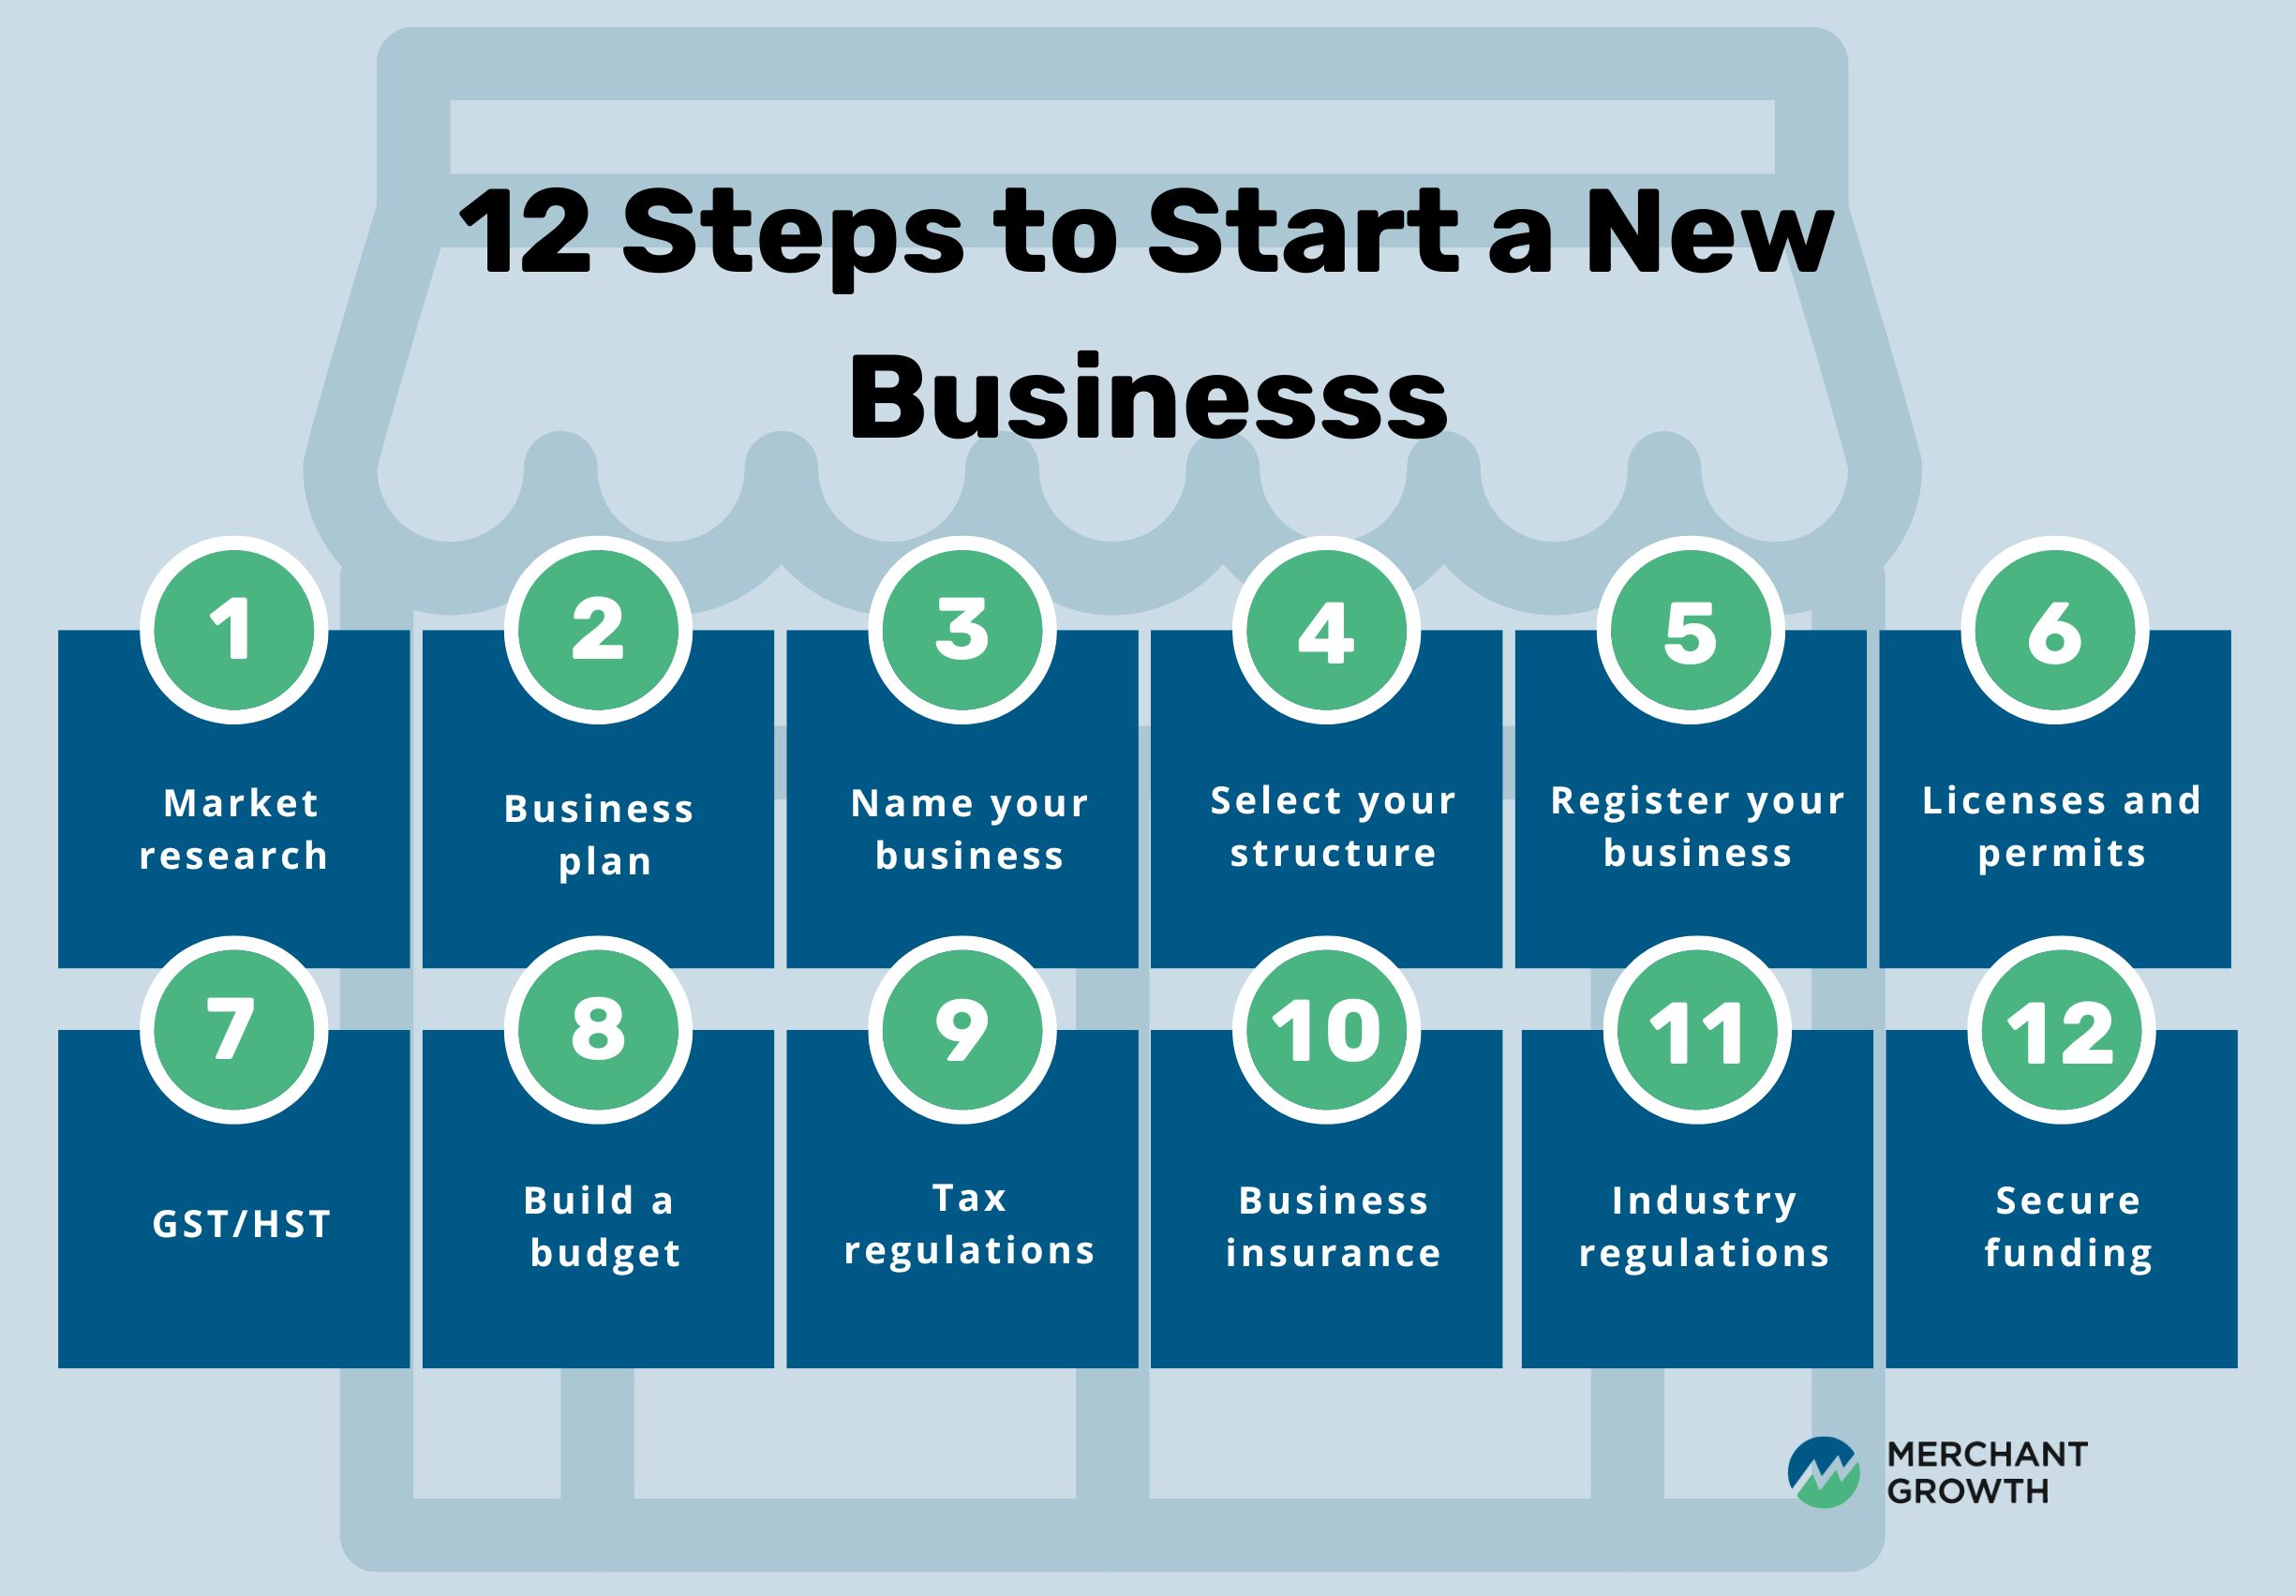
The first thing nobody tells you is that the legal structure you pick will dictate your tax life for years. Most people choose an LLC because they saw it on a podcast. It's not always the right call. If you're planning to bring in outside investors or go public someday, C-corp is the standard, even though the double taxation angle makes some founders nervous. I had a client who formed an LLC in Delaware while living in Texas, thinking it would look impressive to VCs. It just created a foreign qualification requirement and an extra year of annual reports. He ended up paying two sets of franchise taxes for three years before fixing it. The workaround was straightforward — dissolve the Delaware entity and form a Texas LLC instead, but the cleanup took about six weeks and roughly $2,400 in filing fees and professional time. Pick your entity type first. Everything else flows from that decision. Sole proprietorship is free and fast but leaves your personal assets completely exposed. An LLC gives you liability protection but adds compliance overhead. S-corp election can save you money on self-employment taxes once you're pulling at least $60,000 to $80,000 in annual profit, but the paperwork and quarterly payroll requirements eat into that savings if you're under that threshold. Get your EIN from the IRS website. It's free and instant if you apply online. Don't use a third-party service for this — they charge $50 to $150 to do what takes three minutes on irs.gov. I've seen people waste hundreds of dollars on formation packages that include the EIN service as a upsell.
Open a business bank account before you make your first sale. Commingling funds pierces the corporate veil in ways most founders don't understand. One small business owner I worked with lost his LLC protection because he paid a vendor personally and then reimbursed himself from the business account. A judge ruled that was enough evidence of alter ego behavior to go after his personal assets when the vendor sued. It was a $12,000 dispute that cost him $180,000. Set up basic accounting from day one. QuickBooks Self-Employed works for solo operators doing under $200,000 in revenue. Above that, QuickBooks Online Plus or Xero gives you the inventory and multi-account tracking you actually need. The transition point matters more than people realize. Moving from self-employed to a full plan mid-year creates reconciliation headaches that cost about 10 to 15 hours to sort out. Register for state and local permits. This is where people get tripped up. A general business license isn't the same as a professional permit, zoning clearance, or sales tax permit. If you sell physical goods, you need a seller's permit in every state where you have nexus. Economic nexus kicked in after the Wayfair decision and now requires registration in most states once you hit $100,000 in sales or 200 transactions, whichever comes first. The threshold varies by state, so check your specific jurisdiction before assuming you're clear.
Create an operating agreement even if your state doesn't require it. I know that sounds backwards. It's not. Without one, your LLC defaults to your state's default rules, which are designed for average cases and rarely fit real business situations. A properly drafted operating agreement controls how disputes get resolved, how profits get distributed, and what happens when a member wants out. I've seen a two-founder company implode over a 40/60 ownership split that wasn't documented anywhere. The courts had to determine intent based on email threads and bank deposits. That process cost them $47,000 in legal fees and destroyed the relationship entirely. Get basic insurance. General liability starts around $500 to $1,200 per year for most small service businesses. Product liability runs higher if you're manufacturing anything. Professional liability, also called E&O, is non-negotiable if you give advice or services. A single mistake claim without coverage can wipe out a new business in months.
Get the Full Details
What actually goes wrong after launch
Most new businesses fail in the first 18 months because founders underestimate the time between when work happens and when money arrives. If you're billing net-30 terms and your expenses hit monthly, you need at least 90 days of operating capital buffered in the bank. I recommend 120 days because something always goes wrong. A client of mine launched a consulting practice with six months of runway and ran out in month four when two clients delayed payment by 45 days each. He had to take a personal loan at 18% APR to cover payroll. The cash flow gap killed the business within eight months. The other common failure point is founder equity disagreement. Split equity 50/50 and you guarantee a deadlock situation. Even 60/40 creates problems if the minority partner brings critical relationships or IP that the majority partner undervalues early on. Vesting schedules solve this partially. Four-year vesting with a one-year cliff is standard for a reason. It protects everyone if a founder leaves in the first 12 months. Without vesting, someone can walk away with 25% to 50% of the company after three months and you're stuck trying to raise capital with a cap table that looks like a liability. Contracts matter more than people think. A simple service agreement with scope, payment terms, and IP assignment clauses costs about $300 to $800 to draft properly. Using a free template from the internet is a different calculation. One founder I knew used a template from a business forum for his first three client contracts. The template had no limitation of liability clause. A client sued for $200,000 in alleged damages from a project that cost $15,000. The founder settled for $45,000 because litigation would have cost more than the settlement. A proper contract with a cap at the contract value would have made that claim worthless.
Track your metrics from month one. Revenue alone tells you nothing useful. Gross margin, customer acquisition cost, lifetime value, and burn rate are the numbers that actually predict whether your business survives. Most founders I talk to can't tell you their CAC because they never tracked which marketing channel brought each customer. They know they spent $3,000 on Google Ads but have no idea how many paying customers that generated. Without that data, you're making decisions blind and burning money on channels that don't convert. There's no perfect guide. Any resource claiming otherwise is selling something. The reality is that starting a business involves making dozens of small decisions with incomplete information, dealing with bureaucracy that seems designed to confuse, and constantly adjusting your approach based on what actually happens rather than what you planned. The people who succeed are usually the ones who treat the paperwork as seriously as the product, keep their financial records clean from day one, and don't skip the legal basics because they think it'll slow them down. It won't. The time you save by cutting corners gets collected by lawyers and the tax authority later, usually with interest.