What You're Actually Paying When You Borrow From Hard Money Lenders
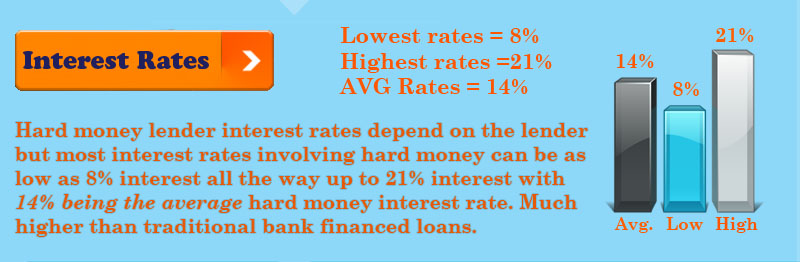
Hard money loans are short-term, asset-backed loans where the lender cares more about the collateral value than your credit score or income documentation. The interest rates are typically between 8% and 15%, sometimes higher for riskier deals. But the rate is only part of the story. Points, origination fees, and prepayment penalties add up fast. I work with fix-and-flip borrowers constantly, and the thing I see most people mess up is comparing hard money rates to conventional loan rates. They're completely different products with different purposes. A conventional mortgage at 6.5% over 30 years has nothing to do with a 12% hard money loan over 12 months. The monthly payment math looks wildly different even when the nominal rate seems comparable.
Breaking Down Hard Money Interest Rates Properly
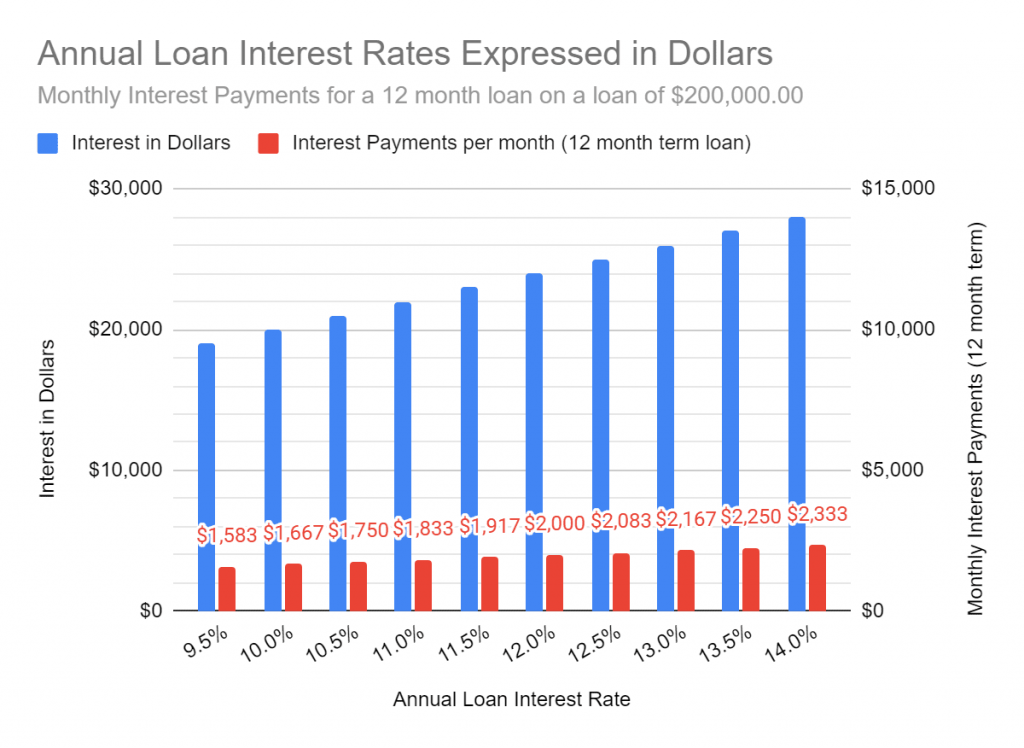
The annual percentage rate on a hard money loan is usually expressed as a percentage of the total loan amount, but the real cost comes from how it's structured. Most lenders charge points upfront, where one point equals 1% of the loan amount. A typical deal might be 12% interest plus 3 points, which means you're paying 3% of the loan before you receive a single dollar. On a $200,000 loan, that's $6,000 taken out immediately. Here's the practical calculation most people skip. If you borrow $200,000 at 12% interest with 3 points, and you pay it off in 6 months, you're not just paying half the annual interest. The points get amortized across the life of the loan, so your effective annual rate is closer to 15% when you factor everything in. Lenders often quote the base rate to make the deal look better. Always ask for the yield—the actual effective rate after all fees are included. I ran into this exact situation last year with a borrower who thought he was getting a clean 10% loan. The lender quoted 10% interest with zero points, which sounded almost too good. When I pulled the loan estimate and started reading the fine print, there was a 2% administrative fee tucked into section J, a 1% document preparation charge, and a 5% prepayment penalty if the loan closed before 12 months. The effective yield on that deal was 14.2%. I had the borrower renegotiate, and the lender came down to 10% with no hidden fees by removing the prepayment penalty in exchange for a slightly longer lock period. Saved him roughly $8,000 on a $250,000 loan.
The biggest trap is the lock-in period. Hard money lenders love 6-month to 12-month minimum terms with steep prepayment penalties because their model depends on you carrying the debt long enough for them to hit their target return. If your rehab timeline slips by two months, you're still paying full interest. I've seen borrowers absorb an extra $4,000 to $7,000 in interest because they didn't negotiate the prepayment terms upfront. Always negotiate the prepayment penalty structure. Some lenders will waive it entirely or reduce it to 2% if you commit to the deal properly. Another thing nobody warns you about is how the interest is calculated. Most hard money lenders use simple interest, not compound interest. That's actually better for you compared to some other short-term lending products, but it still means you're paying interest on the full principal amount from day one. You don't get the benefit of amortization like a traditional mortgage. Each payment is interest-only, and the entire principal comes due at the end of the term. If you need to make principal reductions during the loan, make sure the lender allows it without penalties. Some of them charge a processing fee for every partial principal payment.
Get the Full Details
When Hard Money Makes Sense and When It Doesn't
Hard money loans exist for a reason. They close fast—sometimes in 5 to 10 business days—and they underwrite the property, not the borrower. If you have a deal that needs to move quickly, or if your credit profile wouldn't qualify for conventional financing, hard money is the right tool. The cost is high, but speed and flexibility have a price. Where people get destroyed is by using hard money as a long-term solution. I've seen borrowers roll over hard money loans three or four times because they couldn't sell the property fast enough or couldn't qualify for a bridge loan or conventional refinance. Each rollover means new closing costs, new points, and more interest. After three rollovers, you're looking at 6% to 9% in fees alone, not counting the interest. That's the real danger of hard money debt—it compounds your costs every time you extend it. If you're doing a fix-and-flip, the math usually works if you can buy the property, rehab it, and sell within 6 to 9 months. At 12% interest plus 2 to 3 points, you're looking at roughly $18,000 to $27,000 in carrying costs on a $300,000 loan over that period. Factor in rehab costs, holding costs, and closing costs on the sale, and your profit margin needs to be substantial. If your deal only gives you a 10% to 12% return, a hard money loan will eat most of it.
There are alternatives worth exploring first. Private money lenders—individuals lending their own capital—often offer lower rates, sometimes 7% to 10%, because they're not running a business with overhead. The tradeoff is less consistency and slower closings. Credit union bridge loans are another option for borrowers with decent credit and steady income. They offer shorter-term loans at rates closer to 7% to 9%, though the qualification bar is higher. If you can access a home equity line of credit on your primary residence, that's usually the cheapest short-term capital available at 6% to 8%. But not everyone qualifies for those options. Investors with multiple properties already, poor credit, or self-employed income that doesn't document well are exactly the people who need hard money. The key is knowing your numbers before you sign anything. Write out the full cost scenario on paper: the interest rate, the points, the fees, the prepayment penalty, the minimum term, and what happens if you're late on a payment. Some lenders charge a 5% late fee after just 10 days past due, which is aggressive compared to conventional loans that typically give you a 15-day grace period. The market for hard money lending has changed significantly over the last few years. Post-2022 interest rate increases pushed hard money rates up across the board. Where you could get 9% plus 2 points in 2021, you're looking at 11% to 14% plus 2 to 3 points now. Some regional lenders have tightened their criteria too, requiring higher equity cushions and lower loan-to-value ratios. Expect 65% to 70% LTV instead of the 75% to 80% you might have gotten a couple years ago. This means you need more of your own money in the deal, which changes the entire investment calculation.
One final thing that matters more than most people realize: talk to the actual lender, not just the broker or loan officer. Brokers shop your deal to multiple hard money lenders and mark up the rate by 1% to 2%. If you call the lending company directly, you often get a better rate and you can ask the actual underwriter about flexibility on unusual situations. I once had a borrower who was approved through a broker at 13% plus 3 points, then called the same lender directly and got the exact same deal at 11% plus 2 points. The broker had simply added their markup on top. That's a $5,000 difference on a $250,000 loan for no added value.