What Hard Money Lenders Interest Rate Actually Looks Like in Practice
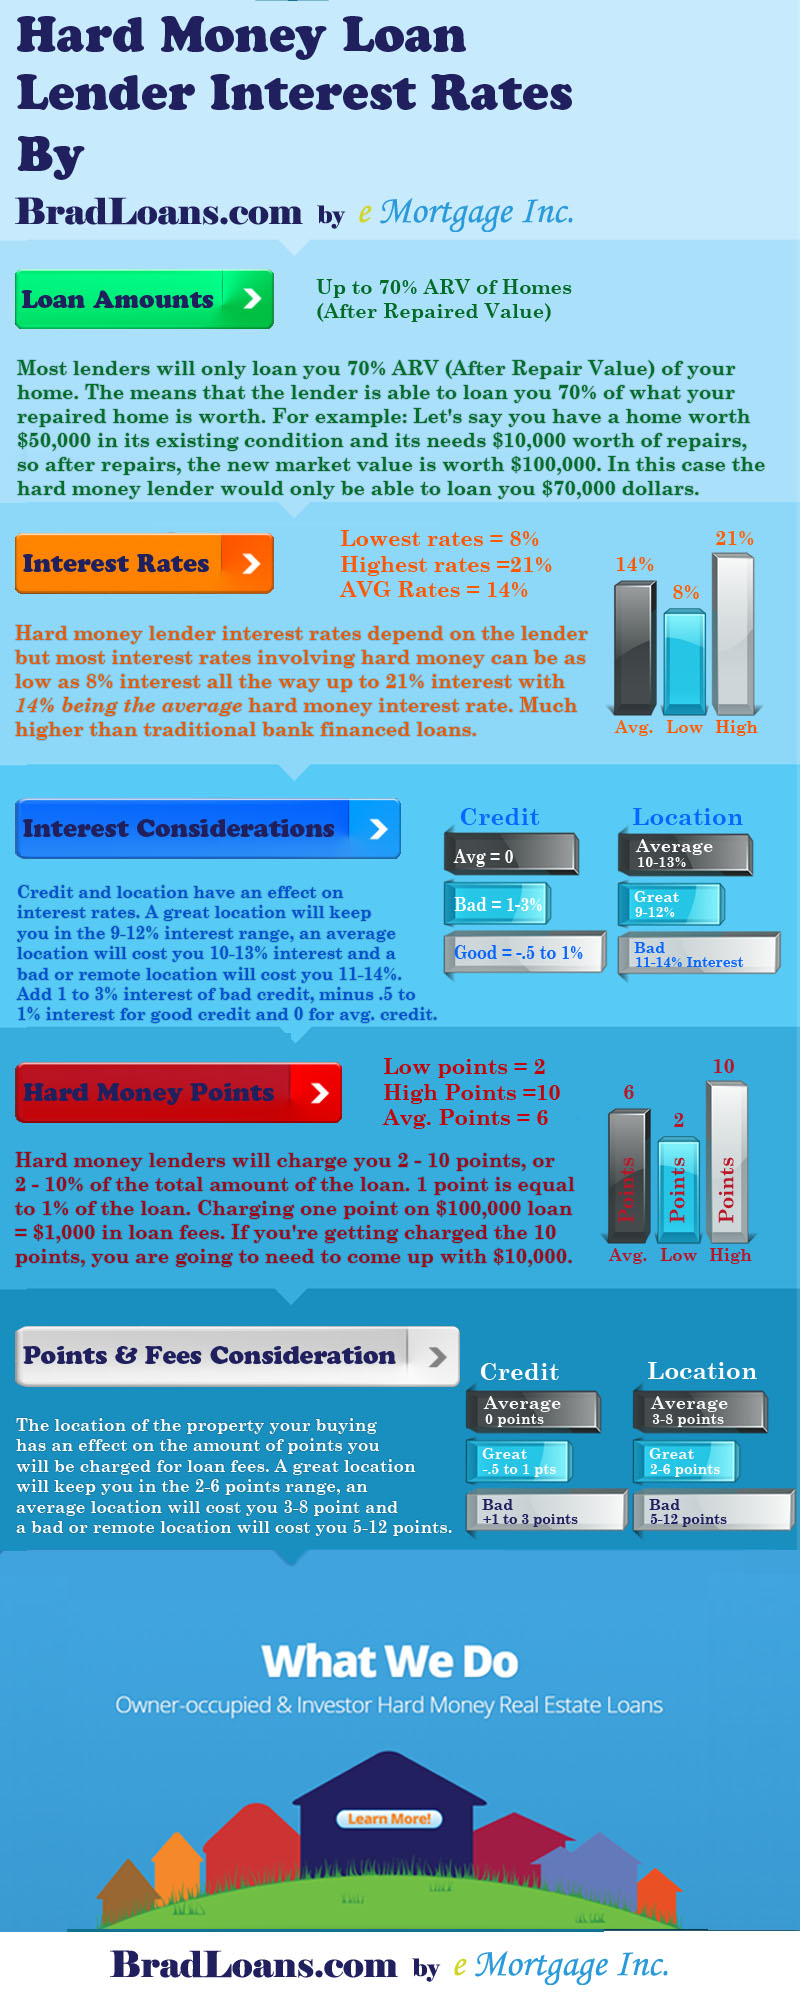
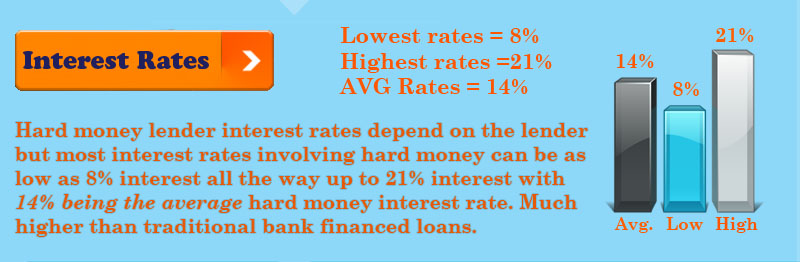
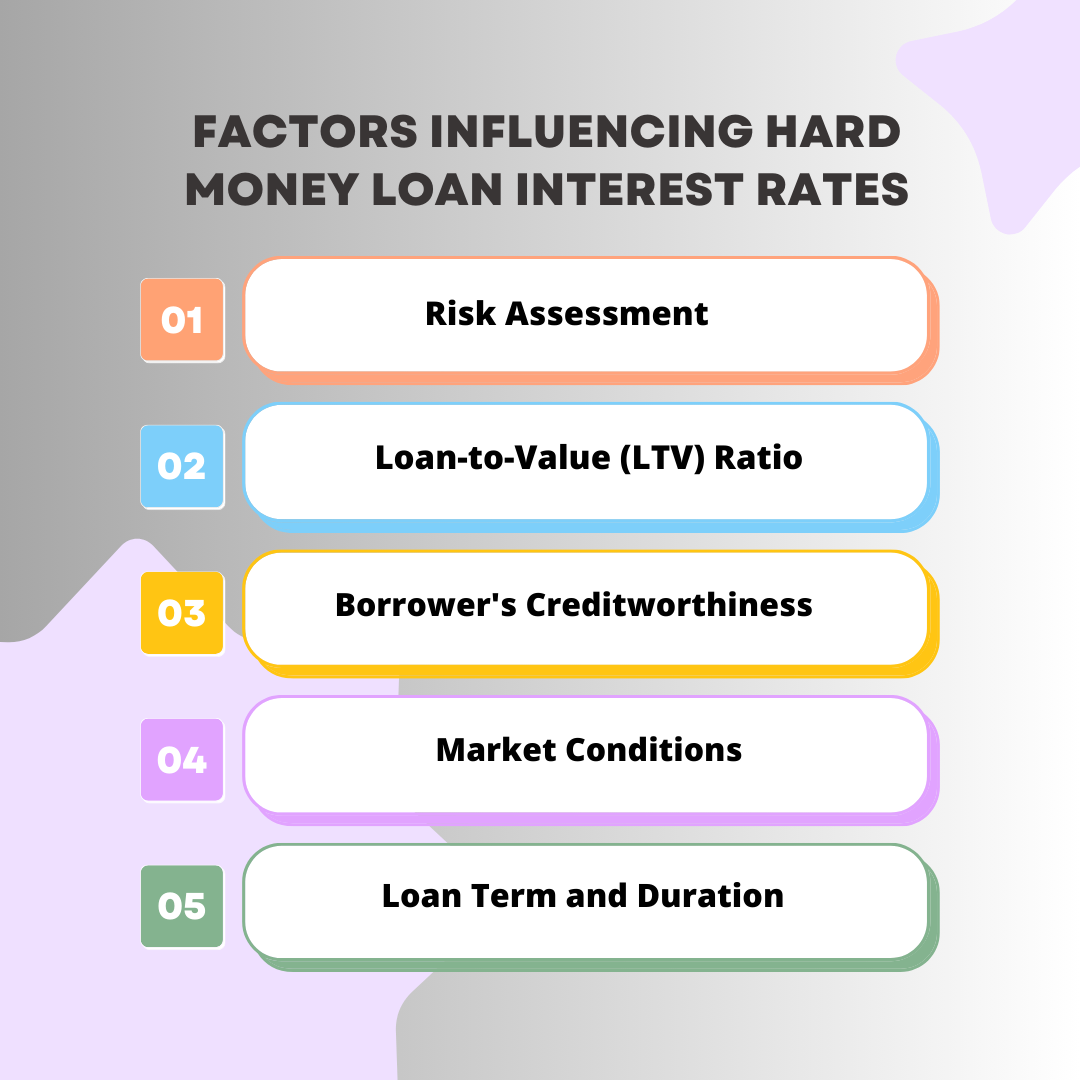
The rate you'll see quoted is rarely the full story. A lot of people walk into their first hard money deal thinking they're just shopping for an interest rate, but that's almost never where the real cost hides. The quoted rate is one component of a much messier equation. Most hard money loans sit between 8% and 15% annually on the note rate. That's the number you see on the first page of the quote. But here's what most first-time borrowers don't calculate correctly: points are almost always stacked on top of that. A standard deal will charge 2 to 5 points, which means 2% to 5% of the loan amount gets deducted upfront. If you're borrowing $200,000 at 10% rate with 3 points, you're actually getting $194,000 in proceeds but paying interest on $200,000. That bumps your effective cost up significantly. Then there's the origination fee, sometimes baked into the points, sometimes separate. Appraisal fees, inspection costs, courier charges, title work on the collateral — these all vary wildly between lenders and can add another 0.5% to 1.5% to your actual yield.
I've seen a borrower in Georgia once compare three quotes that all showed the same 12% rate, and when I recalculated the all-in cost it ranged from 13.8% to 17.2%. The difference was entirely in how each lender structured the fees. The one with the lowest rate actually cost nearly 3 points more in the end. That happens every time someone shops rate alone. Another thing nobody warns you about: some hard money lenders use a prepayment penalty structure that makes short-term flips cheaper than extended holds. A common structure is a 5% prepay penalty if you pay off in year one, dropping to 3% in year two, then nothing after that. If you're buying a fixer, renovating, and flipping within eight months, that 5% hit is real. I ran into a situation where a borrower took a slightly higher note rate on purpose because the lower rate came with a five-year lockout on refinancing. They needed out at month fourteen and couldn't move. The extra 75 basis points in rate ended up saving them from being underwater on a bad deal. That one still comes to mind whenever someone asks me which rate is better without asking about the exit strategy. The other nuance people miss is how the draw schedule affects effective cost on renovation loans. If a lender releases funds in stages tied to inspections, you're not using the full loan amount until the later draws come through. But some lenders still calculate interest on the full committed amount from day one. Others only charge on what's actually disbursed. That gap alone can swing your carrying cost by thousands over a typical rehab timeline. Always clarify whether interest accrues on the full commitment or on disbursements only before you sign anything.
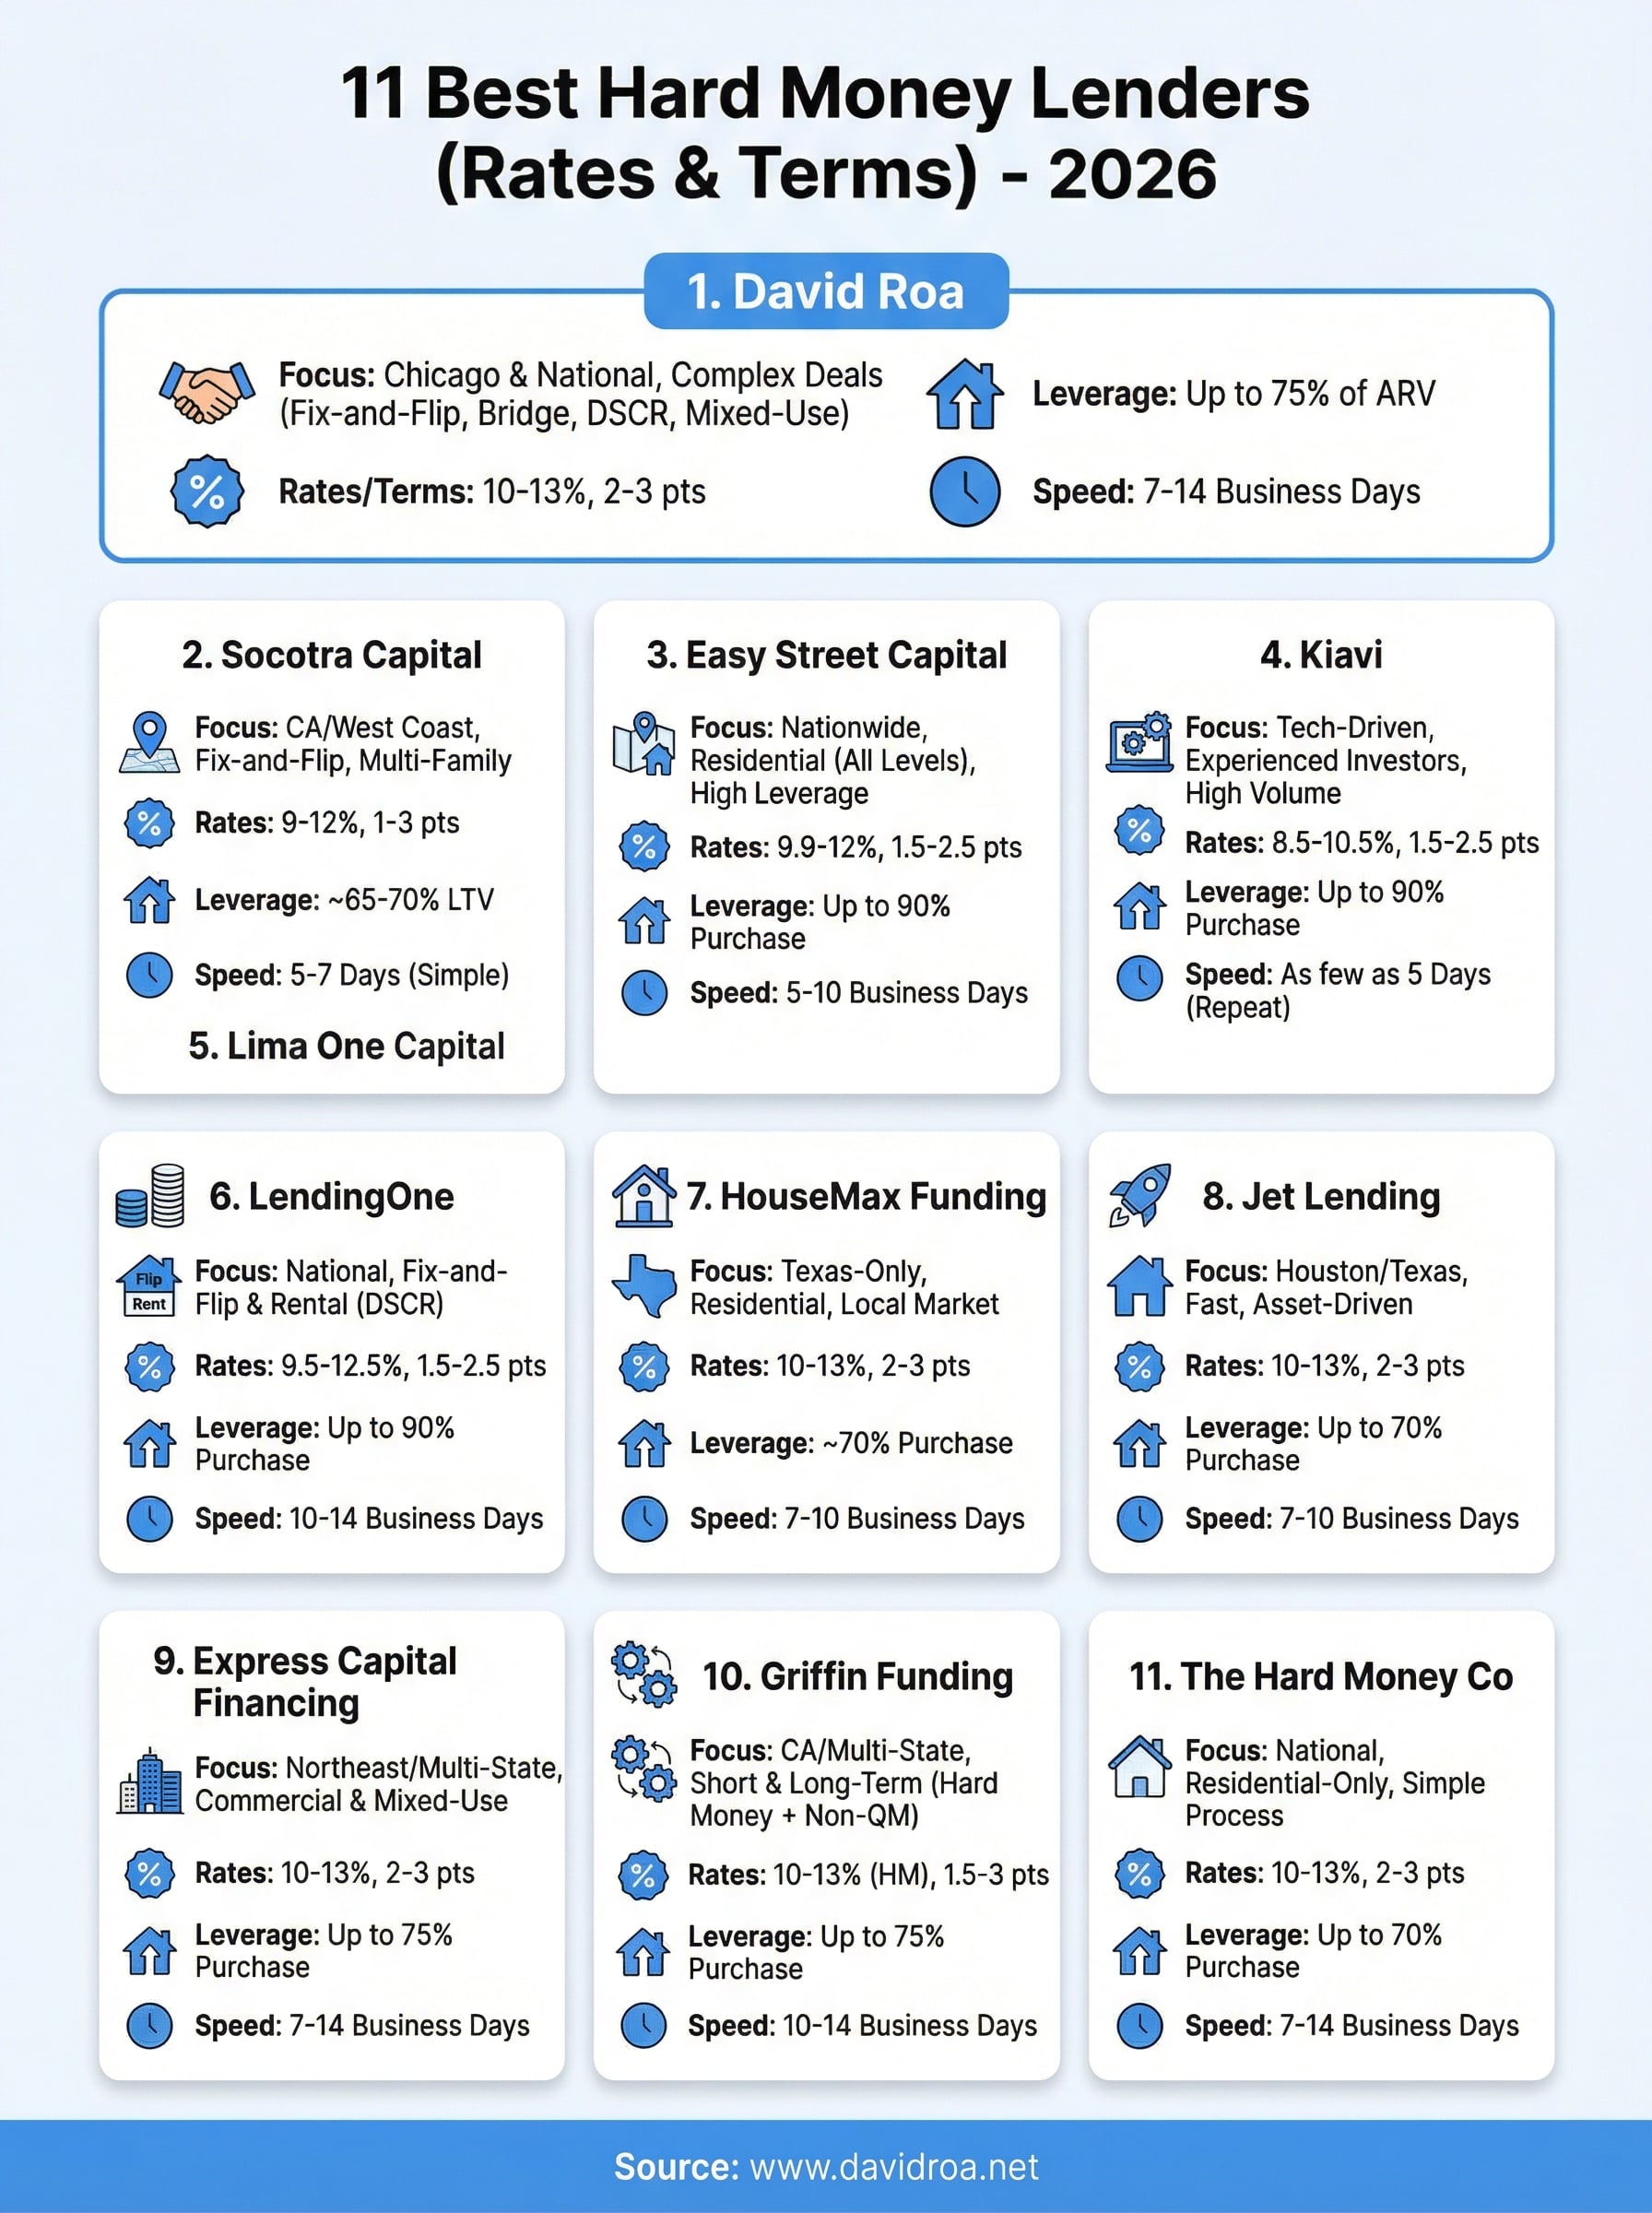
There are also lender tiers that matter more than the rate itself. The big regional hard money operations with institutional backing will often offer lower rates — sometimes into the single digits — but they have stricter underwriting, longer closes, and less flexibility on creative deals. The smaller operators charging 14% might close in seven days and work around issues the big guys won't touch. If you need speed and simplicity, the cheaper rate usually isn't available to you anyway. If you need a unique property type or a borrower with complications, the expensive lender might be the only one at the table. My rule of thumb now is to calculate the note rate and the points separately, confirm the draw schedule interest structure, check the prepayment terms, and then build a pro forma that includes every fee I can find before comparing any two offers. It takes maybe ten minutes and it's saved me from at least three bad deals over the years. Anything less than that and you're leaving money on the table without knowing it.
Get the Full Details