Why Hard Money Lenders Make You Do the Math Yourself
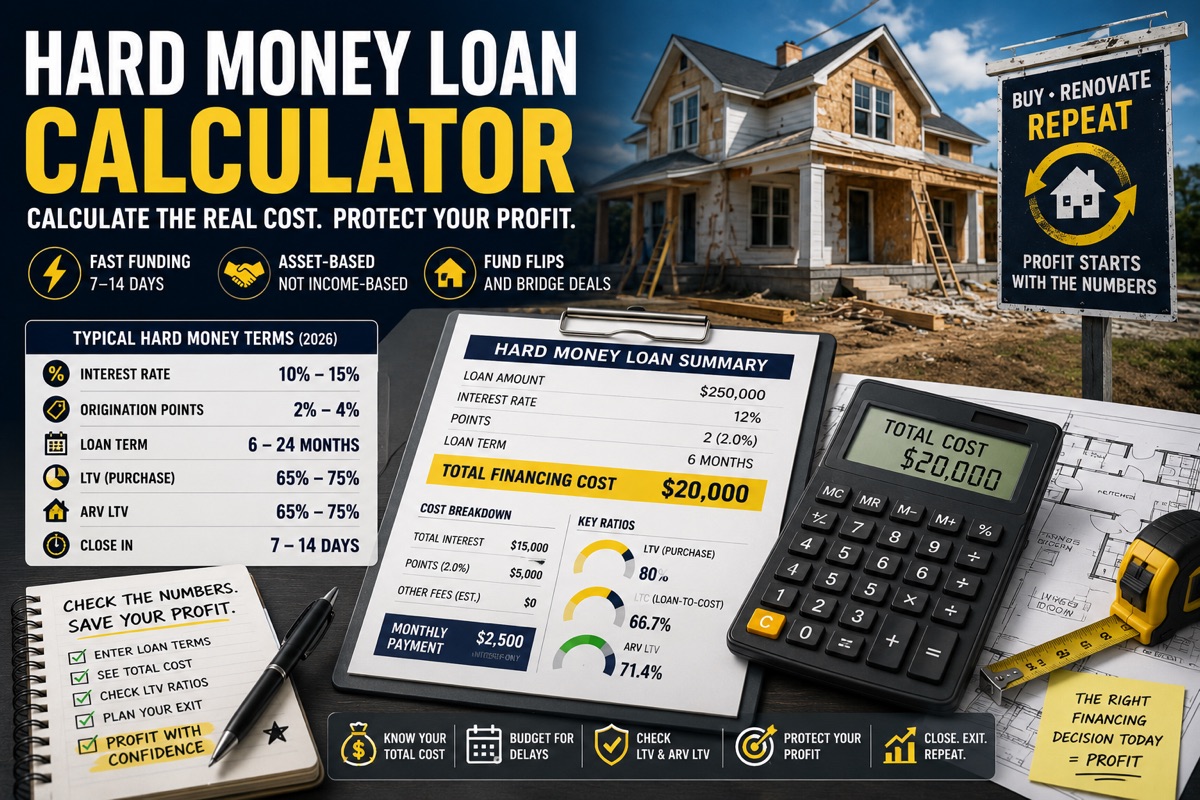
I spent six years underwriting flips across three states before I stopped relying on spreadsheet templates that looked professional but missed basic edge cases. The hard money lending calculator is less of a standalone tool and more of a framework you build around point deductions, prepayment penalties, and the ARV adjustment lenders quietly bake into their approval matrix. Most people treat it like a black box where they punch in numbers and get a green light. That mindset will get your deal killed before you even make an offer. The reality is more mechanical. You enter the purchase price, the after repair value, the rehab budget, and the term length, then the calculator spits out the loan amount, monthly payment, and total interest cost. But the useful version goes further. It factors in discount points, origination fees, and the lender's actual combined cost percentage so you can see what you are really paying over the life of the loan.
Hard Money Lending Calculator
The calculator I use is not a polished website with animations. It is a spreadsheet I built from scratch, and here is how it works in practice. You start with the ARV because that is what the lender cares about most. They will lend based on a percentage of that number, usually between 65 and 70 percent, sometimes higher if the market is hot and the borrower has a strong track record. Subtract your expected profit margin and the rehab costs, and what is left is roughly the maximum the lender will advance against the deal. Where things get tricky is the discount point calculation. A point is one percent of the loan amount, charged upfront. If a lender quotes you 2 points plus a 1 percent origination fee on a $200,000 loan, you are looking at $6,000 in closing costs before you receive a single dollar. The calculator needs to reflect that as a reduction in available funds, not just list it as an optional expense you can ignore. I learned this the hard way on a deal in Tampa in 2019. I had a borrower who was closing on a $185,000 fix-and-flip and needed the funds within ten days. The lender quoted 3 points and a 9 percent interest rate for a twelve-month term. I ran the numbers through a free online calculator and got what looked like a reasonable monthly payment. I presented the deal to the borrower as affordable. We were two days from closing when the title company flagged that the lender had also tacked on a $1,500 servicing fee and a $750 document preparation charge that the calculator never showed. The borrower fell out of escrow because the actual cash needed at close was $4,200 higher than projected. I lost that commission and spent the next month rebuilding the spreadsheet from scratch with every line item a lender could possibly hide.
The workaround was straightforward. I started requesting the lender's full good faith estimate before running any numbers. You need to see the actual fee schedule. Once I had that, I built the calculator to accept the complete fee breakdown as input rather than trying to estimate it. That took the guesswork out of the process and cut the underwriting time for each deal down to about twenty minutes, which is still slower than I would like but far better than missing a $4,200 gap at the last hour.
Get the Full Details

How to Build One That Actually Works
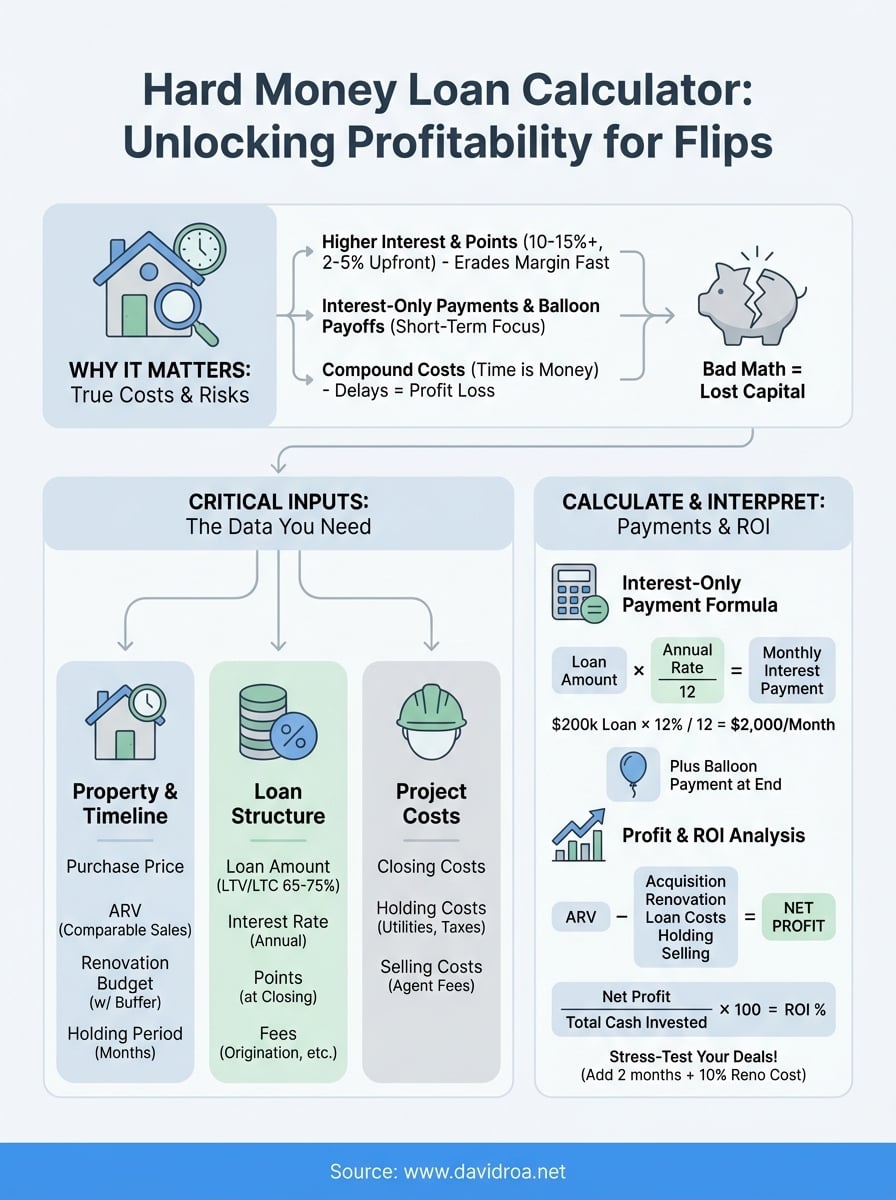
Start with the basics. Create columns for purchase price, ARV, rehab cost, loan term in months, interest rate, and discount points. The formula for the loan amount is simple: multiply the ARV by the lender's loan-to-value ratio. Most hard money lenders cap at 70 percent LTV, so use 0.70 as the default unless the lender specifically tells you otherwise. For the monthly payment calculation, use the standard amortization formula. Hard money loans are typically interest-only with a balloon payment at the end, so your monthly cost is just the principal multiplied by the monthly interest rate. The total interest paid over the term is that monthly amount times the number of months. Add the upfront points and origination fees, and you have the real cost of borrowing the money. Then layer in the fees that trip people up. Servicing fees are often 0.25 to 0.5 percent of the loan amount per year. Document preparation runs $500 to $1,500 depending on the lender. Prepayment penalties vary wildly. Some lenders charge nothing if you refinance within six months, while others levy a penalty equal to six months of interest no matter what. I have seen lenders charge both a yield gap and a prepayment penalty on the same loan. The calculator needs a field for prepayment penalty terms so you can model the worst-case scenario.
Common Mistakes That Cost You Money
The biggest error I see is using the purchase price instead of the ARV to calculate the loan amount. Lenders do not lend based on what you paid. They lend based on what the property will be worth after repairs. If your purchase price is $150,000 and the ARV is $250,000, the loan is calculated on the $250,000 figure, not the $150,000. Using the wrong number throws off every subsequent calculation. Another frequent mistake is ignoring the holdback reserve. Lenders frequently withhold 10 to 15 percent of the rehab budget to ensure funds are available for change orders and unexpected issues. That money comes out of the loan disbursement, not your pocket, but it reduces the cash you have to actually spend on the project. I once reviewed a deal where the rehab budget was $45,000 but the lender released only $38,250 because of the holdback. The borrower had to cover the remaining $6,750 out of pocket, which erased his projected profit entirely. The calculator should flag the holdback as a separate line item so it does not get hidden inside the total loan amount. Here is a nuance most beginners miss. The effective interest rate on a hard money loan is not the same as the nominal rate you see in the quote. Because points and fees are paid upfront, they reduce the actual amount of money you receive. If you borrow $200,000 at 10 percent interest but pay $8,000 in points and fees, you only receive $192,000. The true cost of that loan is closer to 10.8 percent. Your calculator needs to compute the effective rate by dividing the total interest and fees by the net proceeds. Without that step, you are comparing deals on inaccurate numbers and making bad choices.
When the Calculator Fails You
A hard money lending calculator will give you a clean number, but it cannot account for everything. It does not know your local lender's mood. It does not factor in whether the property is in a flood zone that triggers extra insurance costs. It cannot predict if a lender will renegotiate the terms mid-close because the appraisal came in low. None of these are errors in the calculator. They are limitations of a tool that works strictly within the numbers you feed it. If you are working on a large or complex deal, the calculator should be treated as a starting point, not a final answer. Run the numbers through it, then verify the results with a second source. I always cross-check by asking the lender for a written commitment letter before I present the deal to the borrower. The commitment letter locks in the terms and reveals any last-minute fees that the calculator missed. This usually adds two days to the underwriting timeline but prevents the kind of shock I experienced in Tampa. For investors who do not want to maintain their own spreadsheet, there are commercial platforms like LoanPro and DealMachine that offer hard money estimation tools. These cost between $50 and $200 per month depending on the feature set. If you are doing more than three deals a year, the subscription pays for itself quickly. If you are doing one or two deals a year, building a basic spreadsheet is probably more efficient. The time investment is about four hours upfront and then zero maintenance if you keep it simple.
The Bottom Line
A hard money lending calculator is useful when it includes every fee a lender charges, accounts for the holdback reserve, and shows the effective interest rate rather than the quoted rate. It is dangerous when it gives you a single output number without revealing the assumptions behind it. The tool itself is not the problem. The problem is treating it like it knows more than it does. Feed it accurate inputs, verify the outputs against a commitment letter, and you will save yourself a lot of headaches.


