How Hard Money Lending Actually Works in Practice
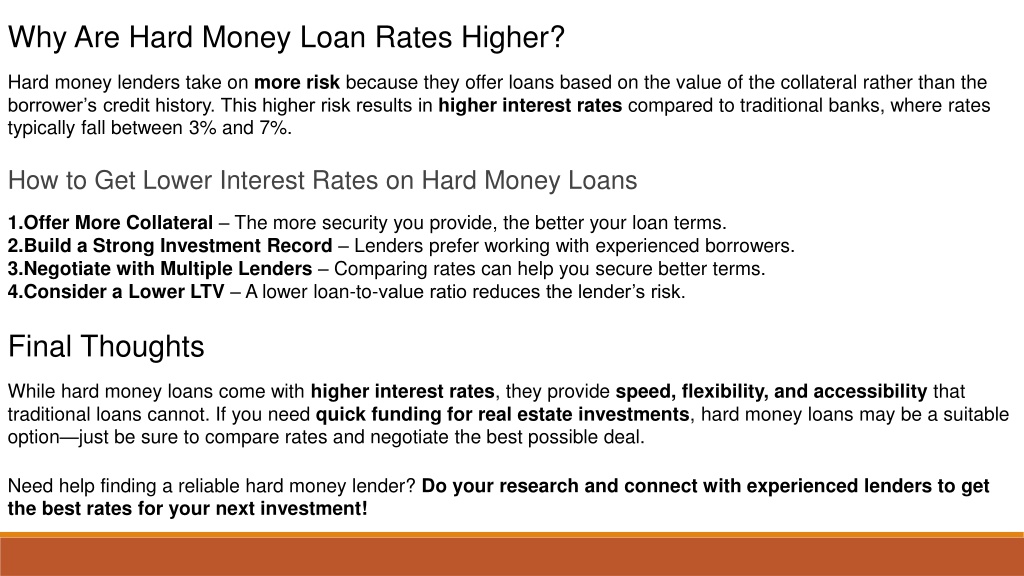
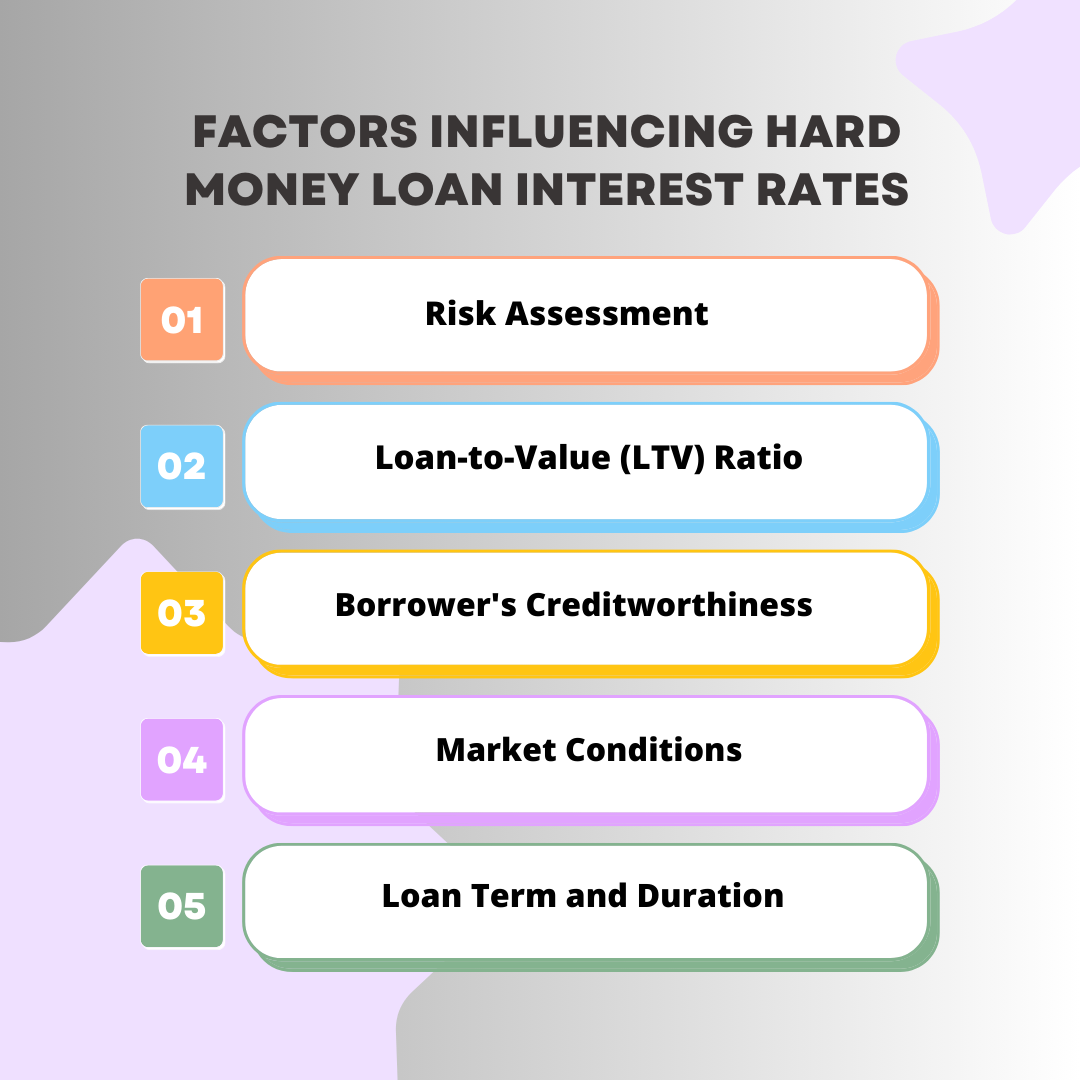
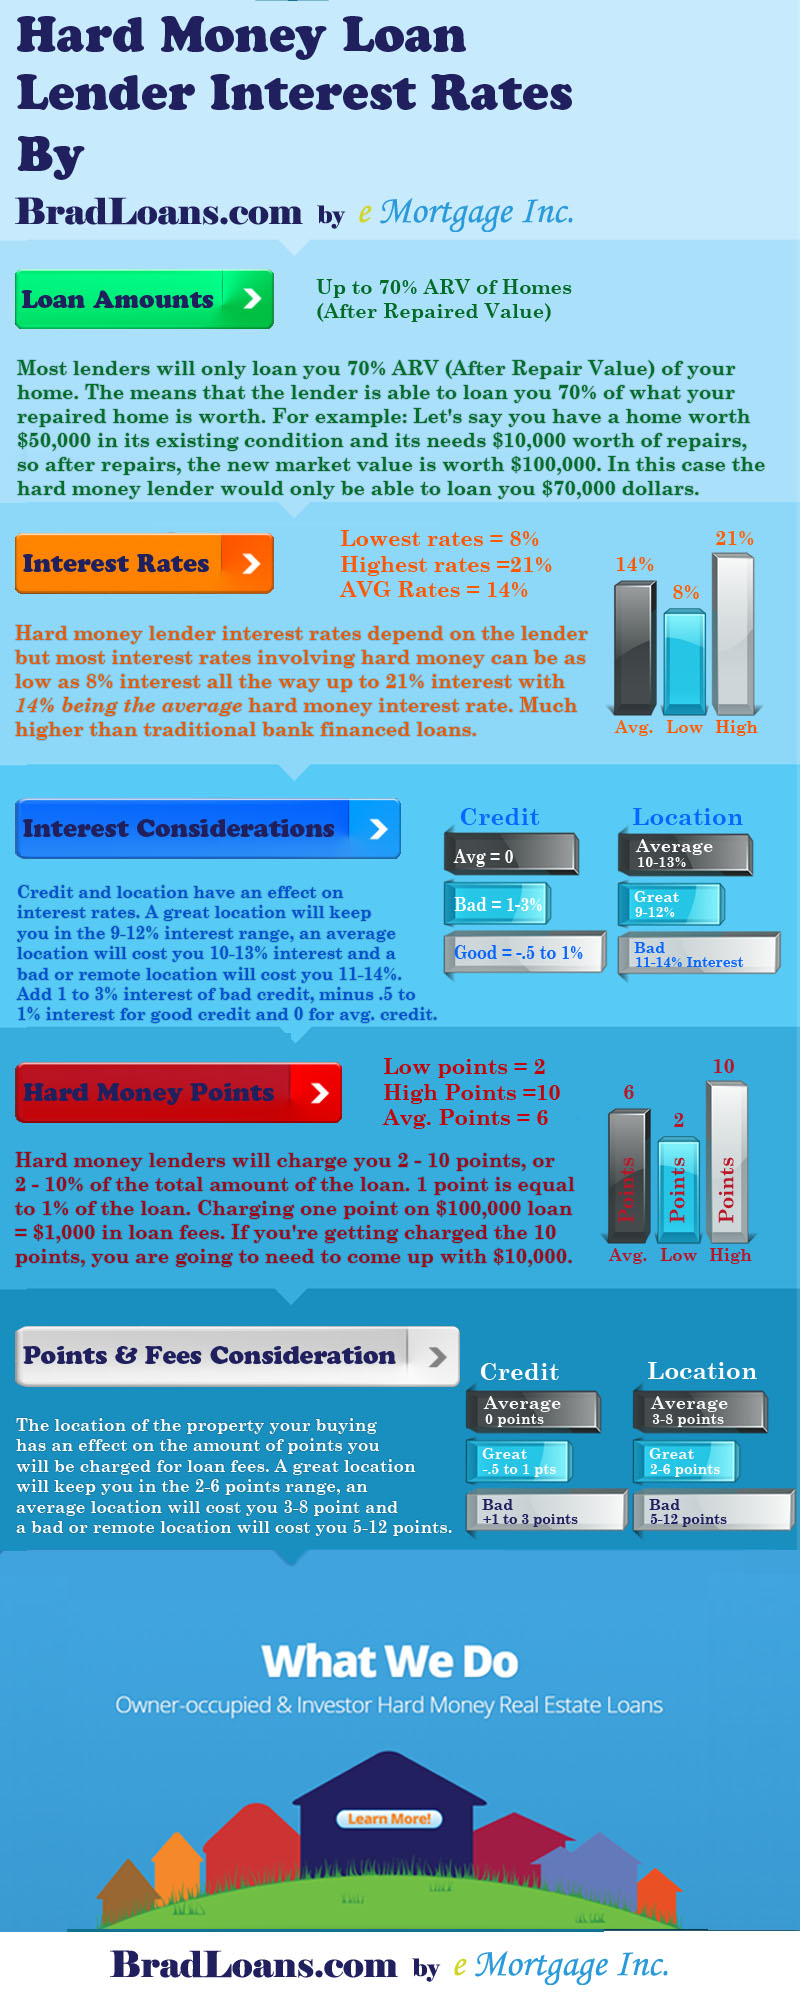
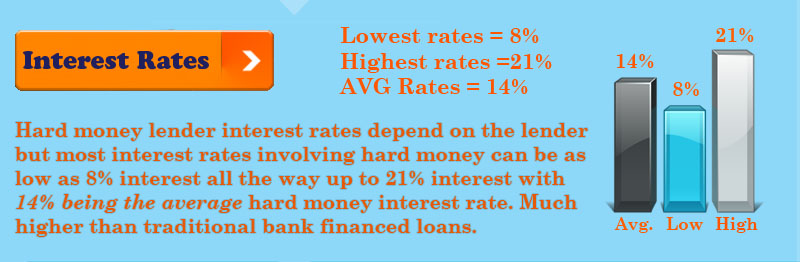
Most people looking at hard money lending rates see a number like 10-15% and immediately assume it's the total cost of borrowing. It isn't. The real cost is a combination of interest rate, origination points, underwriting fees, and any prepayment penalties stacked on top of each other. Understanding that difference matters when you're evaluating whether a fix-and-flip or bridge loan makes financial sense. In the current market, base rates for hard money loans typically sit between 9% and 14% depending on the lender, the property type, and your exit strategy. Origination points usually run 1 to 3 points upfront, where one point equals 1% of the loan amount. A $200,000 loan at 11% interest with 2 points means you're paying $4,000 in points at closing alone, plus monthly interest that accrues daily from day one. The trick isn't finding the lowest rate. The trick is finding a lender whose underwriting criteria aligns with your actual rehab timeline and exit plan. I've seen investors pick the cheapest-looking loan and then get bogged down for months because the lender required progress inspections they couldn't satisfy on schedule. One extra month of holding costs on a hard money loan can eat $1,500 to $3,000 in interest on a typical loan. That's not hypothetical. I watched a flip go from a $22,000 profit to a $4,000 loss because the lender held the note for 90 days longer than projected while waiting for a contractor's photos to pass inspection. The rate was the same either way. The lender's operational friction is what killed the deal.
Another thing people miss is how much the loan-to-value ratio plays into rate tiering. Some lenders offer their best rate at 65% LTV but bump the rate up a full point if you're borrowing at 75% LTV. If you're working with a $300,000 ARV and need $225,000 to fund the purchase and rehab, you're at 75% LTV. Ask whether the lender has a stepped rate structure and request a written fee schedule before you submit an application. Getting that on paper forces them to commit to numbers instead of negotiating in real time under pressure.
How to Structure a Hard Money Deal That Doesn't Get You Burned
Start by getting your numbers before you shop for lenders. Calculate your ARV using recent closed sales, not Zillow estimates. Zillow's algorithm is built for owner-occupant residential comps and it consistently misprices B-class renovation targets. Pull three to five closed comparables within a half-mile radius that sold in the last 90 days and are similar in square footage, bedroom count, and condition post-renovation. Average those numbers. That's your exit value. From there, build your repair budget with contractor quotes, not Home Depot material lists. I learned this the hard way on a 2023 bungalow rehab where I budgeted $45,000 based on my own estimate. The actual bids came in at $62,000. The lender had already approved $175,000 against a $210,000 ARV. When the repairs blew past the budget, I had to bring $17,000 out of pocket at closing because the draw schedule was locked. If I'd gotten actual quotes first, I would have either renegotiated the loan amount or walked away from the deal entirely. Shop at least three lenders but don't treat them as interchangeable. One lender might offer 10% at 2 points with fast closing but slow draw releases. Another might charge 12% at 1.5 points with weekly draws. For a quick flip where speed matters more than monthly cash flow, the first option saves you holding costs even with the higher rate. For a BRRRR strategy where you're carrying the loan for 12 to 18 months, the lower-point structure with faster draws will save you thousands over the life of the loan. The math favors the second lender despite the higher headline rate.
Get the Full Details
Common Pitfalls That Derail Hard Money Deals
The biggest mistake I see is borrowers who don't account for the lender's evaluation fee structure. Some lenders charge separate fees for the initial appraisal, the rec appraisal at closing, and periodic inspection fees during the draw process. These can add up to $2,500 to $4,000 in soft costs that never get discussed until the paperwork arrives. Always ask for a complete fee disclosure in writing before you sign anything. A good lender will provide it without pushback. A reluctant one is usually hiding something. Prepayment penalties are another area where people get caught off guard. Some hard money loans carry a yield maintenance clause or a minimum interest requirement for the first 12 to 24 months. If you sell or refinance early, you still owe the full interest for that period. On a $250,000 loan at 12%, that's $30,000 in interest you owe even if you close in 60 days. This is non-negotiable with many lenders and it's baked into their rate structure. If you plan to exit within a year, factor the prepayment penalty into your profit calculation upfront. Otherwise you'll be surprised at closing. There's also the issue of lender capacity. I ran into this with a lender who had a stated funding timeline of 14 days but was routinely three weeks out because they had too many deals in pipeline. I switched to a smaller community lender who charged 0.5 points more but consistently closed in 10 days. The extra cost was negligible compared to the risk of missing a contract deadline and losing the property. Rate matters less than reliability when you're working with tight timelines.
When Hard Money Isn't the Right Tool
Hard money loans are expensive capital and they're meant to be temporary. If your deal requires more than 18 months to complete, the costs compound to a level where conventional financing or a private money arrangement usually makes more sense. I've seen investors roll hard money notes into additional hard money notes because the first deal didn't sell, and by the third renewal the total cost of capital exceeded 20% all-in. That's a death spiral. If you're already projecting a 12-month hold, check local credit unions and community banks on portfolio rental loans. They can offer rates in the 7 to 9% range with longer amortization, which changes the entire profitability model on a rental or hold strategy. The bottom line is that hard money lending rates are just the starting point of a much larger calculation. The real work is in the fee structure, the draw schedule, the lender's operational speed, and your own ability to execute the exit plan on time. Get all the numbers in writing, verify the ARV independently, and don't let a competitive rate distract you from a lender who is slow, inconsistent, or vague about their fee schedule.