How Hard Money Payment Calculators Actually Work
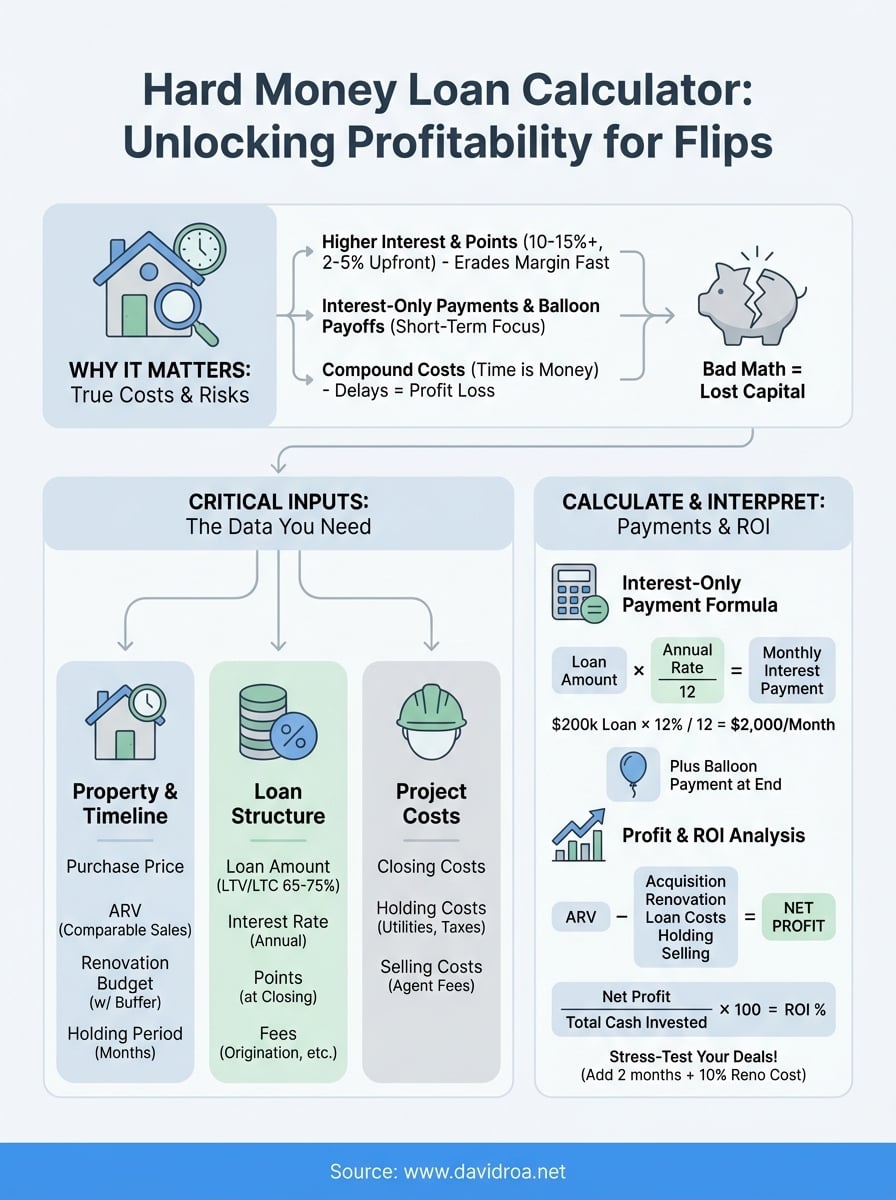
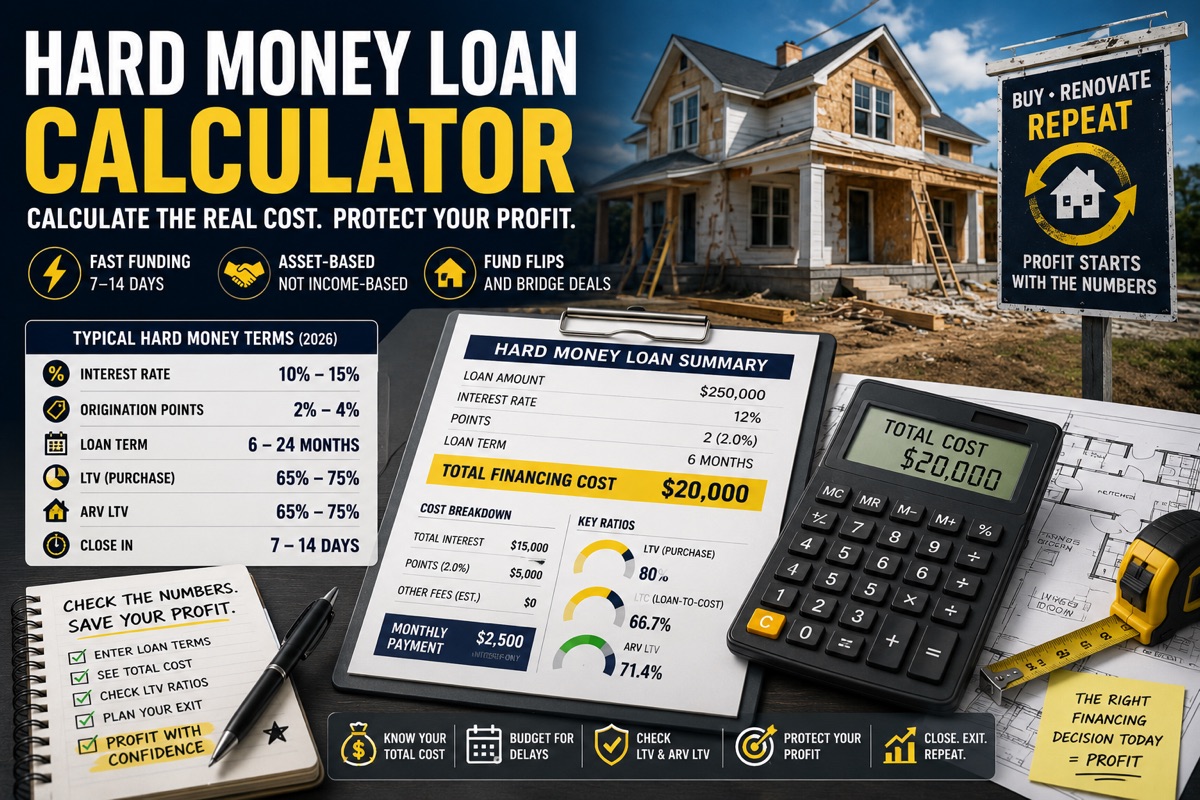
A hard money payment calculator is a tool that figures out your monthly costs on a short-term, asset-backed loan. These loans come from private lenders, not banks. The rates are higher, the terms are shorter, and the fee structure is messier than conventional financing. You plug in the loan amount, interest rate, term length, and points, and the calculator spits out a monthly payment number. That's the basic idea. The formula behind it is straightforward, but the devil is in the inputs. Most hard money loans are interest-only with a balloon payment at the end. So your monthly payment is just the principal multiplied by the annual rate divided by twelve. If you borrowed $200,000 at 10%, your monthly payment is $1,666.67. Simple math. The complication comes when points and fees enter the picture. Points are upfront fees charged as a percentage of the loan amount. One point equals one percent. A typical hard money loan might charge 2 to 3 points. On a $200,000 loan at 3 points, that's $6,000 taken out of your proceeds at closing. Some lenders roll the points into the loan balance, which changes your effective rate. A calculator should account for this, but many don't ask about it.
I built my own calculator because the free ones online kept giving me numbers that didn't match what the lenders were actually quoting me. Here's what I learned building it. Most online calculators assume a standard amortizing loan. That's wrong for hard money. You need an interest-only calculation with a separate balloon figure. I had to add a field for origination fees, underwriting fees, and processing fees. Lenders stack these differently, and they matter. A $200, loan at 10% with $500 in closing fees is not the same deal as one with $3,000 in fees. The monthly payment looks identical, but your total cost of capital is completely different. Another thing most calculators miss is the difference between a discount rate and a note rate. Some lenders quote you a discounted rate that looks lower but comes with more points baked in. You have to look at the annual percentage rate to compare actual cost. I spent weeks realizing why two calculators were giving me different payments on what looked like the same loan. One lender was advertising 8% but charging 3 points. Another was advertising 11% with zero points. The 11% loan ended up being cheaper over a six-month flip because the points on the 8% deal added about 0.75% to the effective rate. When I designed the calculator, I added a field for lock periods too. If you're rate-locking for 90 days instead of 30, some lenders add a premium. It's small but it adds up. I also included a breakdown section that shows total interest paid, total points and fees, and the total payoff amount at maturity. That payoff number is what matters when you're running your exit strategy. Knowing your monthly payment is useful, but knowing your total cost gives you the real picture for your deal analysis.
The calculator works best when you feed it real lender terms. Don't just plug in average numbers from a blog post. Get the term sheet, enter the exact figures, and verify the output against what the lender's own spreadsheet shows. I always do this. It caught a few errors early on where the calculator was rounding differently than the lender's system. Now I run both sides and flag any discrepancy over twenty dollars. There are limitations. The calculator assumes the loan stays at a fixed rate for the entire term. Some hard money loans have rate adjustments or teaser rates that kick in after six months. Those aren't represented in a basic calculator. If your loan has an adjustable component, you'll need a more complex model or just calculate each period manually. Also, the tool doesn't account for prepayment penalties, which are common in hard money. A lender might charge a penalty if you pay off early within the first year. That can be one to three months of interest depending on the contract. Factor that into your own analysis outside the calculator. If you want something functional, there are downloadable spreadsheets online that do this. Search for a hard money payment calculator spreadsheet and you'll find a few decent options. The free ones tend to be oversimplified. The paid versions from real estate investing platforms are usually better because they include fields for all the fee types I mentioned. I ended up sharing my own build with other flippers after realizing how much time it saved them. What used to take twenty minutes of manual calculation now takes about thirty seconds.
Get the Full Details