What Hard Money Actually Costs You
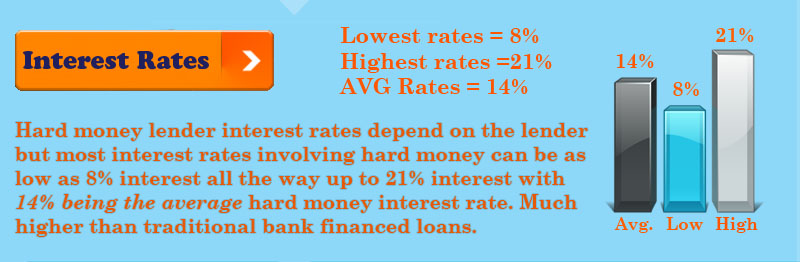
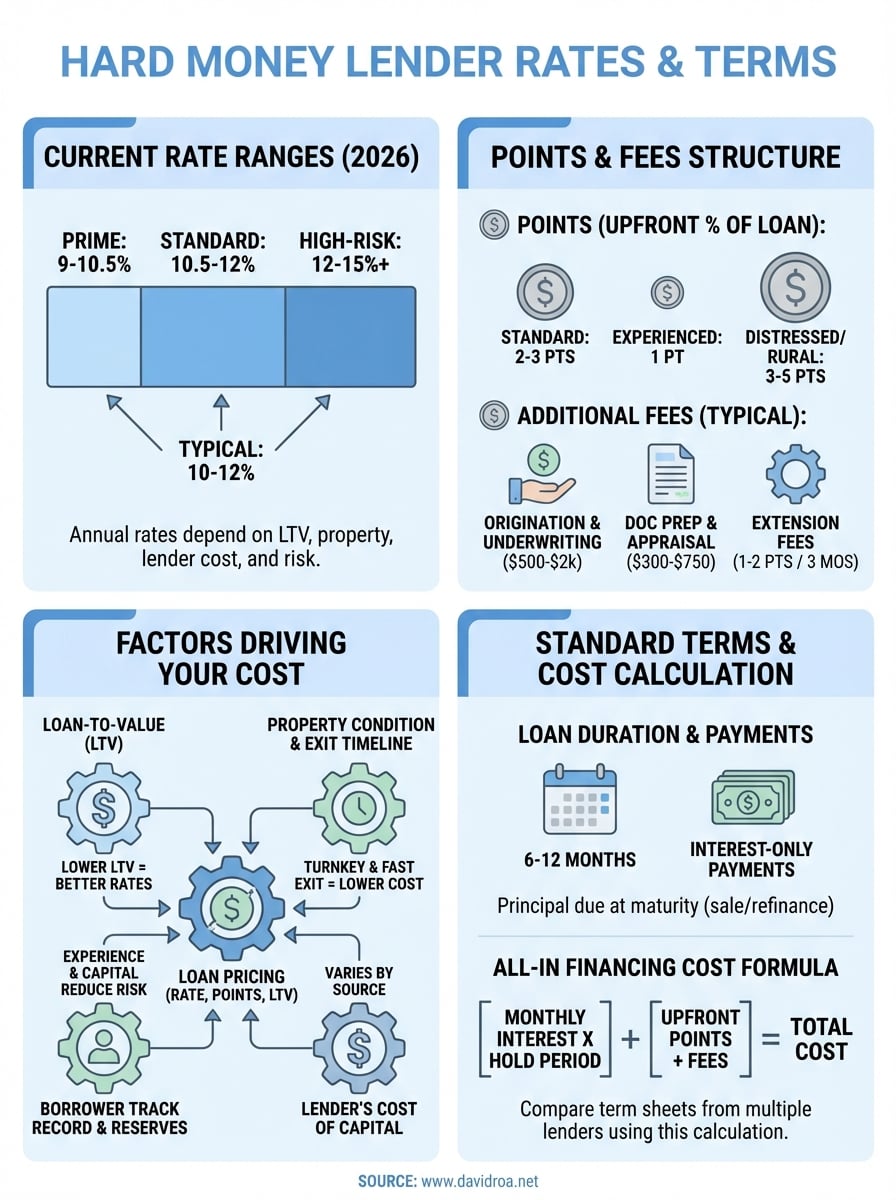
Hard money rates sit somewhere between 10% and 15% annually right now, depending on the lender, the deal, and your leverage. Points are a separate thing and they matter just as much. A single point gets added upfront, so a loan at 12% with two points is actually costing you closer to 14% for the life of the loan if you hold it past the first year. I used to calculate effective rate by hand, which took too long. Now I just use a spreadsheet formula that factors in points, the interest rate, and the hold period all at once. The basic structure is straightforward: you pay a higher rate than you would on a conventional loan, but you get funded fast. Two weeks instead of two months is normal. That speed is the entire value proposition. Lenders price for the risk they are taking, and they are taking real risk because these loans are asset-based, not credit-based.
Hard Money Rates
Here is how the numbers typically break down. The interest rate runs 10-15%. Points range from one to three, sometimes more on a risky deal. The loan-to-value ratio sits between 60% and 75% of the after-repair value, not the purchase price. Lenders care about ARV because they need a cushion if you walk away. The term is usually six to eighteen months with an option to renew. Prepayment penalties vary. Some lenders charge nothing after six months. Others still have a yield-maintenance clause that bites you if you sell early. I have seen investors miss the prepayment penalty because they assumed all hard money loans were flexible on exit. They were not. One deal had a three-year yield maintenance clause disguised in the fine print. I caught it during due diligence but the cost of walking away was higher than paying the penalty. I paid the penalty. It cost me about four thousand dollars. Walking away would have cost me nearly eighteen thousand over the remaining life of the loan. The thing nobody tells beginners is that hard money lenders are not evaluating your credit score the way a bank does. They are evaluating the deal. The after-repair value, the scope of work, the exit strategy. Your credit might be fine and you could still get a higher rate if the property is in a market they do not understand or if the rehab budget looks unrealistic. I had a borrower with a 740 credit score and a solid track record who got quoted 14% plus three points because the property was a triple-decker in a rural market the lender had no comp data for. A similar deal in a metro area with comparable numbers would have gotten him 11% plus two points. The risk was the same. The perception was different.
There is a common misconception that you should always pick the lowest rate available. That is wrong. The lowest rate often comes with the worst terms elsewhere. I watched someone take a 9% rate on a hard money loan and get crushed by three things: a six-point origination fee, a twelve-month prepayment penalty, and a lockout period that prevented any partial payoff. The effective cost was 16% or more. The second-lowest quote on the same deal was 11% with one point, no lockout, and renewal at a flat five percent spread. Over a twelve-month hold, the second deal saved him about seven thousand dollars. Another thing people get wrong is how to compare hard money against other financing options. You should not compare the rate to a conventional mortgage rate. You compare it to the value of speed and flexibility. If a deal requires closing in ten days because the seller will not wait, a hard money loan at 13% might make more sense than waiting three months for a conventional loan at 7%. The math depends on the spread between the purchase price and the eventual sale price, the carrying costs, and the opportunity cost of capital during the wait. I calculated this once for a duplex that flipped for a hundred thousand dollars in profit. Waiting six weeks for a conventional loan would have meant missing the contract. The hard money route cost about four thousand dollars in points and interest for a nine-month hold. The alternative was losing the deal entirely. Four thousand dollars to lock down a hundred grand in profit is not a bad exchange rate.
Get the Full Details

Some lenders advertise low rates to get you in the door. The rate is bait. The points and fees are where they make money. Always ask for a Loan Estimate that breaks down every charge before you sign anything. Not a term sheet. A full Loan Estimate with all costs itemized. Some lenders will give you a one-page summary that looks cheap until you read the addendum with the administrative fee, the underwriting fee, the inspection fee, the flood cert fee, and whatever else they tacked on. I once saw a lender list a 10% rate with no points and then add a seven-point broker fee buried in a separate document. The actual cost was 17% and nobody noticed until closing. There are situations where hard money is the wrong tool. If you have strong credit, stable income, and time on your side, a conventional or portfolio loan will always be cheaper. If you are buying a turnkey property with no repairs needed, hard money is overkill. If you plan to hold the property for more than two years, the cost compounds against you and you should be looking at a long-term loan instead. Hard money is for speed, for distressed properties, for deals that fall outside traditional lending criteria. One edge case that trips people up is the renewal process. Some lenders renew at the same rate. Most do not. Renewal rates are typically five percent above the original rate. If your original rate was 12%, expect to pay 17% on renewal unless you negotiate. I renegotiated my renewal on a rental flip by offering to refinance into a conventional loan within thirty days. The hard money lender accepted a reduced renewal rate because they preferred getting paid off sooner rather than locking me into a higher rate and hoping I could refinance.
If you are shopping hard money loans, get at least three quotes. Read every line item. Calculate the effective annual rate including points and fees. Ask specifically about renewal terms, prepayment penalties, and whether there are any lockout periods. Do not assume the first lender you talk to is the best option. The market is competitive and the differences between lenders are significant.